


Markit Recap – 10/17/2016

There are no shortage of factors that have troubled market participants this year: Brexit; US monetary policy direction; fragility in European banks; oil prices. All of these issues, and others, have caused credit spreads to widen at various intervals in 2016.
But the last few weeks have seen calmness return to the credit markets. The VolX Europe, which shows the realised volatility in the Markit iTraxx Europe index, hit 26.4% this week, which is the lowest level for almost two
years. Implied volatility, as indicated by the 1-month at-the-money CDS index option, is around 40%. The difference between the two represents the volatility risk premium, which is the compensation for bearing risk relating to sharp changes in volatility: risk aversion.
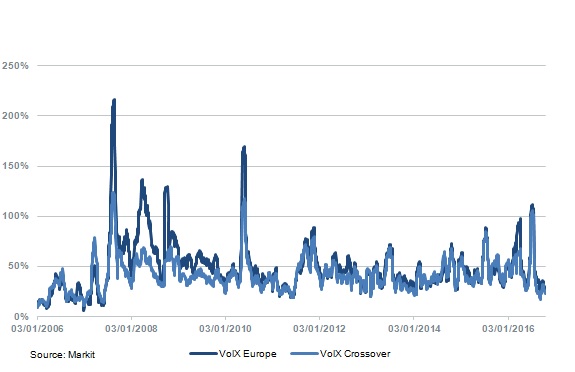
The volatility risk premium in the credit swaptions market tends to be quite large compared to other asset classes, but investors may be tempted to buy portfolio insurance at these levels. Post-Brexit, realised volatility was at its highest level since May 2010, just after the first Greek bailout. The ECB is now far more interventionist, which should curtail volatility. We are also going into year-end, and there are already signs that credit investors are locking in returns.
So what would be the catalyst that could shake the market from its stupor and trigger another bout of volatility? The possibility of ECB tapering QE is one, but Mario Draghi signalled in his press conference on October 20 that this wasn’t on the agenda and bond purchases may well continue past the March 2017 deadline.
A more likely candidate is the Italian referendum on constitutional change in December. The polls indicate that it is neck-and-neck, and former Prime Minister recently came out in support of the “No” campaign. A defeat for the government would probably plunge the country into political turmoil and revive doubts about the viability of the eurozone as a currency bloc.
Contact: Gavan Nolan
Gavan.Nolan@ihsmarkit.com



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…