After collapsing to a 10-year low of less than $30 in January, oil prices are now in the $50 per barrel range. While prices might have stabilized, the industry continues to suffer severe consequences. Defaults have escalated and recovery rates are down significantly from their historical levels. According to Moody’s, loans that are backed by reserves for exploration and production companies have fared better than other debt types, but recoveries were down from prior E&P bankruptcies. Loan issuance for exploration and production companies, which are mostly reserve-based revolvers, has been down dramatically this year.
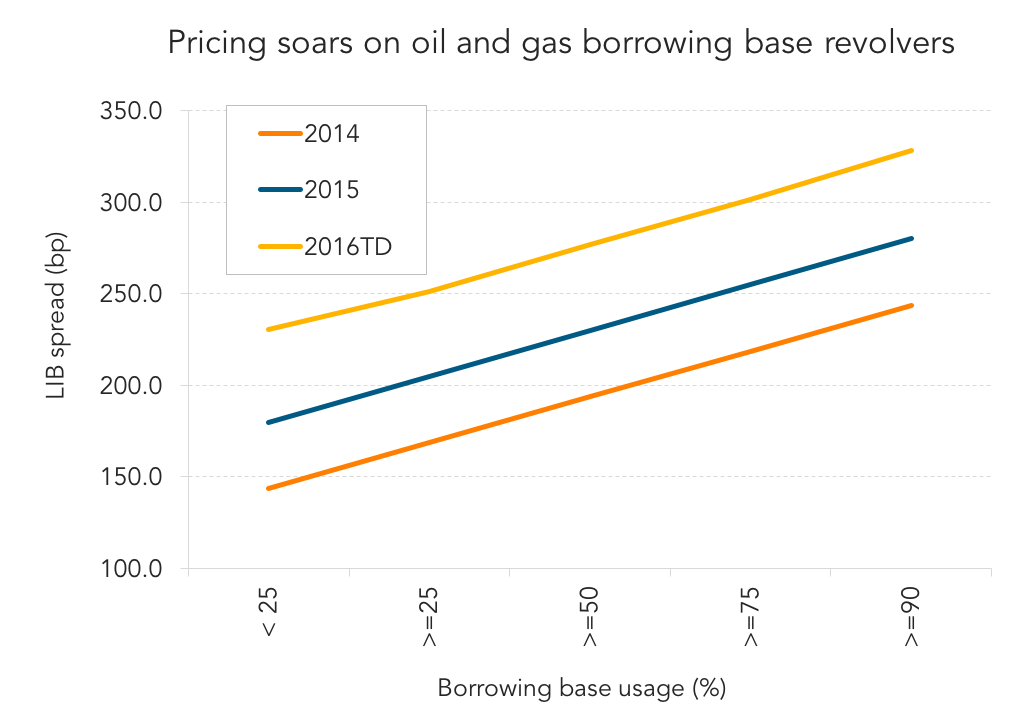
At US$19.5bn through September, issuance is trailing the total for 2015 by 69%. As banks remain cautious to lending to the industry, they are demanding more for taking on the risk. Pricing on reserve-based revolvers is usually tied to a grid based on borrowing base usage. So far in 2016, spreads have increased an average of 21% for all levels of the grid relative to 2015. With the fall borrowing base redetermination season underway –when banks reevaluate how much companies can borrow based on the value of their reserves, some issuers might also see borrowing capacity shrink.



Latest news

US Leveraged Loan Issuance Rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.