


Private Debt Intelligence – 11/7/2016

Private Debt Dry Powder by Fund Type
The past few years have seen a large amount of investor capital in private debt funds remain unspent by fund managers, with strong fundraising activity resulting in a significant ‘wall of capital’. In 2016 so far, private debt dry powder has climbed to $199bn, up from $191bn at the start of the year, although levels of uncommitted capital have fluctuated across different fund types.
Dry powder held by distressed debt managers has risen by nearly a third (31%) since the end of 2014 and now stands at $63bn, the highest of any fund type. This follows on the back of strong fundraising through 2016 so far, which has seen distressed debt funds secure $19bn of investor capital, on course to near the post-Global Financial Crisis record of $28bn raised in 2012. Mezzanine vehicles are the only other fund type to register an increase in dry powder through 2016, reaching a record $51bn up from $44bn at the end of 2015.
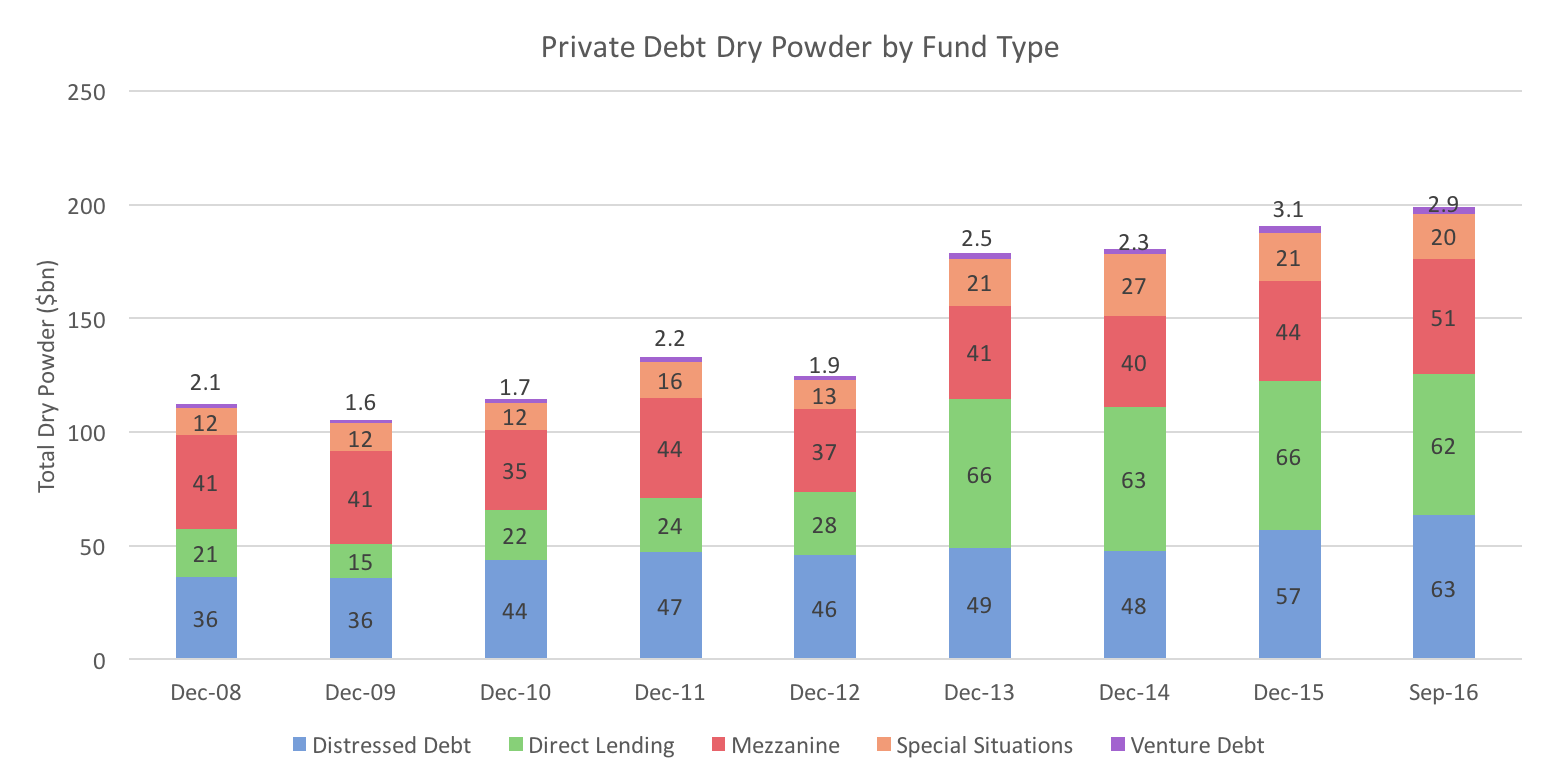
Conversely, following a surge in direct lending fundraising through 2013, dry powder for the fund type rose from $28bn to $66bn across the year. Since then, the level of un-invested capital held by managers focused on the strategy has plateaued, decreasing to $62bn as of September 2016, indicating that firms are now able to deploy investor capital as quickly as they are raising it.
Special situations funds are set to record a second consecutive drop off in dry powder held by fund managers with current levels standing at $20bn. This marks a decrease from the all-time high of $27bn in 2014, and has seen a further decline of $1bn since the end of 2015. Meanwhile, venture debt dry powder has fallen slightly from a record $3.1bn at the end of 2015 to $2.9bn as of September 2016.
While overall private debt fundraising has seen a slowdown through 2016, uncommitted capital has still increased and now stands on the cusp of exceeding $200bn for the first time ever. It is testament to the rapid growth of the industry that investor appetite remains so high, and fund managers will be hoping to put this capital to work over the coming months.



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.