


Private Debt Intelligence – 12/12/2016

UK-Based Private Debt Fundraising
It is perhaps unsurprising that the UK has become the predominant market for the European private debt industry ever since regulation fuelled the growth of the market in the aftermath of the Global Financial Crisis. The UK accounts for a higher proportion of fund managers than any other European country, with 133 of the continent’s 334 fund managers located in the UK, while 186 active investors are also headquartered in the country holding a combined $3.9tn in assets under management.
UK-based private debt fundraising has consistently risen in recent years and has seen six consecutive annual increases from 2009-2015, an indicator of continued expansion within the industry. 2013 marked a year of particular acceleration with 21 UK-based private debt vehicles reaching a final close securing an aggregate $6.7bn. Capital commitments reached an all-time peak in 2015 with a total of $16.2bn secured while so far in 2016, 16 funds have closed raising an aggregate $6.9bn in what has been a relatively quiet year for private debt fundraising, globally.
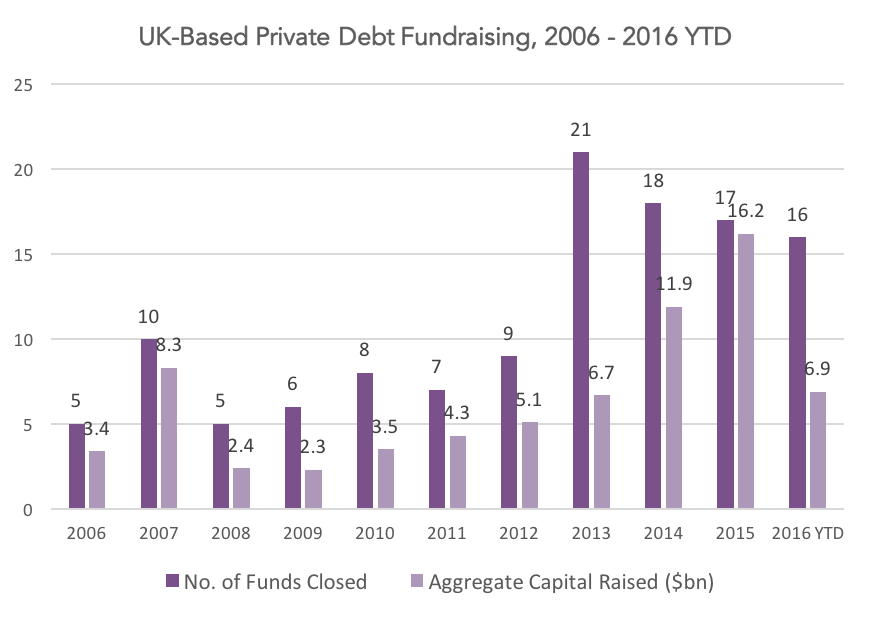
In the period 2013-2016 YTD, fund managers based in the UK have always secured more than half of the total investor capital raised by Europe-based private debt firms. Moreover, in 2015 when UK-based funds achieved their highest fundraising total of all time, the 17 funds closed accounted for more than two-thirds (70%) of the total capital raised, a sign of the UK’s pre-eminence in the region.
There are currently 29 UK-based funds on the road targeting an aggregate $16.6bn as firms within the country become increasingly aware of the opportunities within the non-traditional lending space. Furthermore, managers are able to call on significant investor appetite for the growing European market from North America; the majority of investors targeting UK-focused private debt funds are based in North America, with 38% located in Europe and 4% from elsewhere.
The private debt space is showing no sign of stagnation or shrinkage as investor appetite continues to grow and regulation increasing. Fund managers in the UK are capitalising on the opportunities that currently exist in the market, however it remains to be seen how events in Europe over the coming months and years will affect the economic and regulatory environment.




Latest news
The Recovery Shot
Trouble off the tee doesn’t always translate to trouble on the scorecard.

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.
Private Credit Defaults 101: Scrambling for Par
Seve Ballesteros won four majors in the 1980s despite being, by his own admission, one of the wildest drivers of the golf ball on tour.