


Middle market sponsor-backed issuers are seeing fewer repricings than large corp. issuers
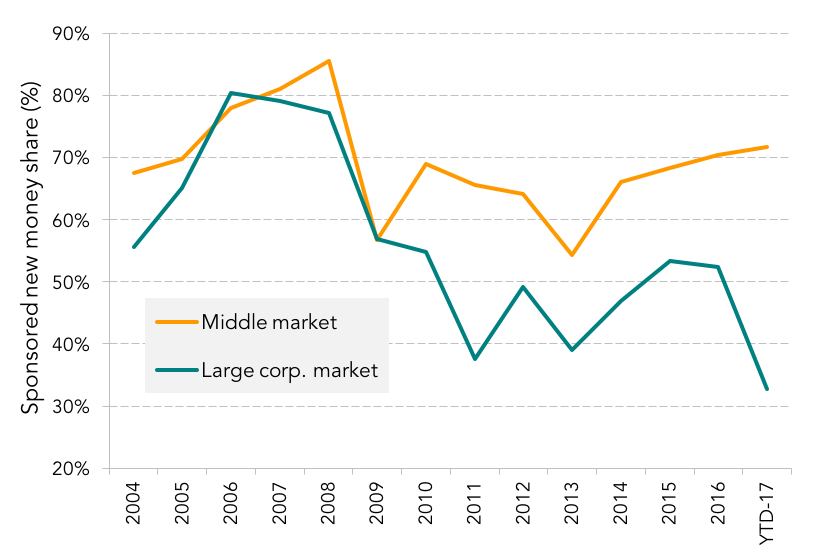
Private equity shops have taken advantage of strong liquidity in the loan market to refinance/reprice many of their portfolio companies into longer dated maturities, looser structures and cheaper pricing. However this repricing phenomenon has been more apprarent on large corporate portfolio companies rather than middle market issuers. The share of new money dealflow this year for sponsor-backed large corporate issuers has plummeted to an all time low of 33%. However, the middle market has held on strong with 72% of sponsored volume in 2017 coming from new money transactions which is the highest market share since 2008. Even so, middle market sponsored volume has not been that impressive and lenders continue to struggle with a supply demand imbalance. Keeping up with runoff has been a huge challenge for these players as their higher priced assets are being redone in the institutional loan market at pricing that is unsustainable for their yield targets. Middle market lenders’ outlook on new money dealflow in the second half has improved from the first half levels, however, lenders believe volume will only increase modestly. In the large corporate market, lenders are also hopeful that the repricing wave will slow down in the second half and new money M&A will make up a bigger share of the lending pie. However, strong demand from mutual fund inflows, CLO issuance and separately managed accounts will continue to keep the market extremely competitive.


Latest news
Software, technology and consumer sectors lose deal share in 9M’26
The software and technology sector, the second most active sector in 2025 at 17% of total deal activity, slid to fifth place in the first nine months of 2026.


Leveraged loan investors see gains in November
Following a 0.25% decline in October, the Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned 0.60% this month through…