


Markit Recap – 7/17/2017

Senior Financials dips below 50bps
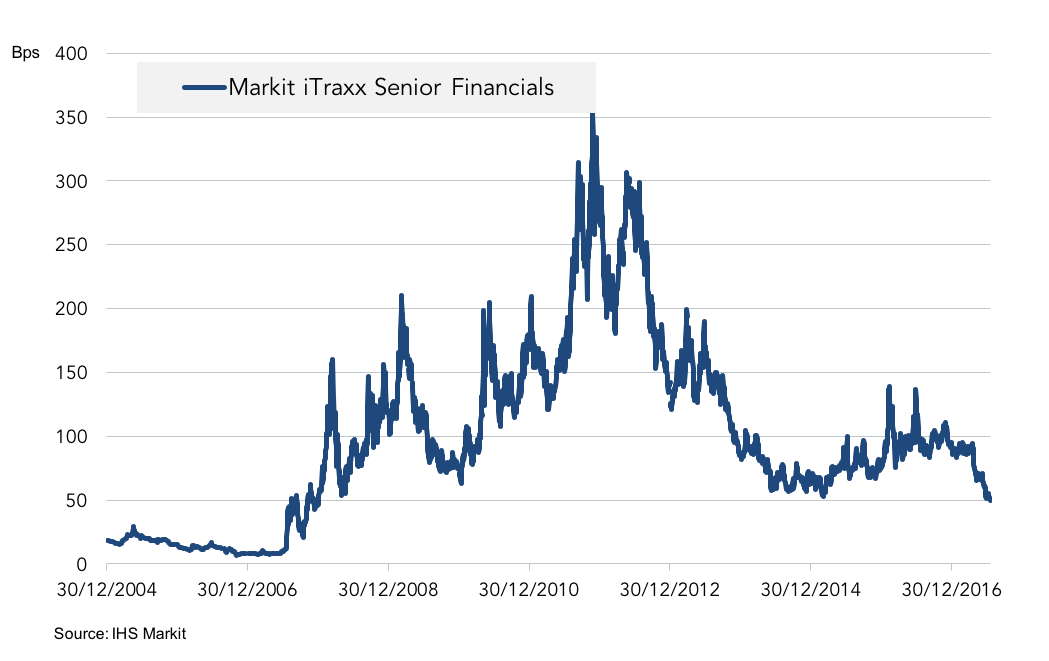
Few would question the supportive role Mario Draghi has played over the last six years. Under his presidency, the ECB quickly reversed the ill-advised rate hikes in 2011 and subsequently loosened policy – the refinancing rate has been at or close to zero since 2014. Extraordinary measures were taken to stabilize the Eurozone, not least several quantitative easing programmes.
Yet there was widespread speculation this week that Draghi would finally change his stance and signal a tightening in policy. The tapering of QE, in particular, was expected by many to be signaled in the ECB’s policy statement. This could be the tipping point for a change in sentiment and shake the credit market out of its soporific state.
But those that espoused this view point were disappointed. It was business as usual at the ECB, with no change in policy and the central bank reiterating its willingness to boost it bond purchase programme should economic conditions deteriorate. Draghi merely stated that a decision on QE will be taken in the autumn.
So it seems that one of the last hopes for volatility has been quashed, at least until the end of the summer. The Markit iTraxx Europe continued to outperform the Markit CDX.NA.IG, tightening by 0.5bps to 52bps. Perhaps more notable was the change in financials. The Markit iTraxx Senior Financials was trading at 49.5bps, a significant move given that the index hasn’t closed below 50bps since January 2 2008.
There are clearly fundamental reasons for the strong showing by this index. The European economy is improving and the long overdue cleanup of the Italian banking industry is underway. But there are technical factors – driven by regulation – that are also relevant. IHS Markit announced last month that Holding Company entities would be considered for inclusion from the next roll in September, and it was confirmed on July 12 that this would happen. This will apply to UK, Swiss and Dutch banks, where this structure is prevalent.
The initial announcement certainly coincided with a tightening in the index, which primarily contains Operating Company entities for banks in these jurisdictions. Liquidity is still poor in the HoldCo entities, but we can expect this to improve as the roll approaches.
Contact: Gavan Nolan
Gavan.Nolan@ihsmarkit.com



Latest news

Open Tab
Leveraged loans keep running up a tab. Senior direct lending already knows what it owes.


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.