


Markit Recap – 8/7/2017

South Korea widens as rhetoric ramps up
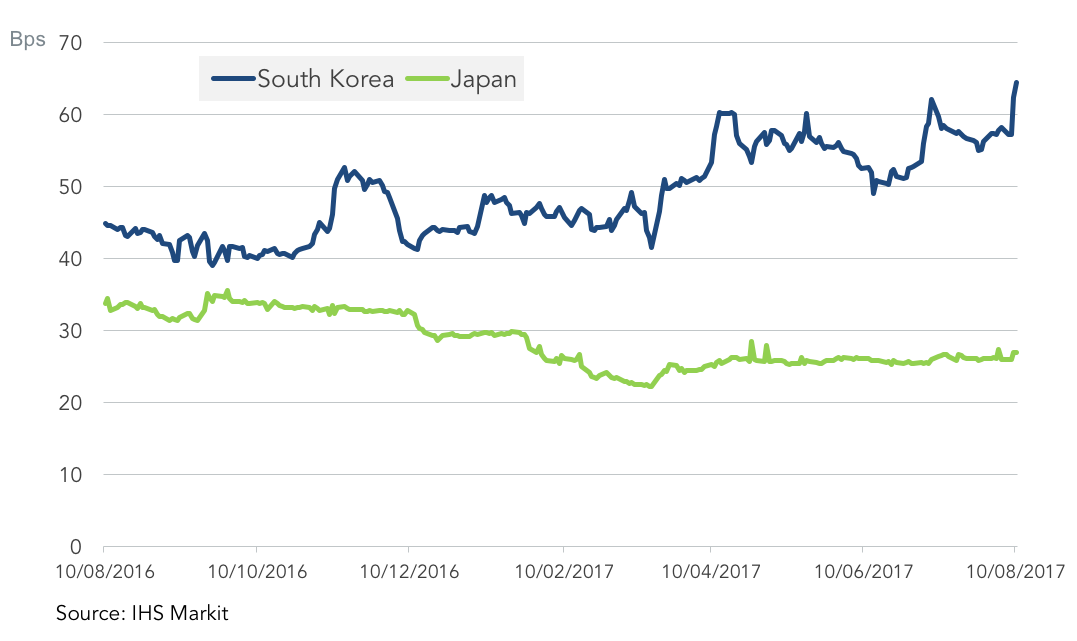
Donald Trump’s promise to bring “fire and fury” to North Korea if it continues to threaten the United States has certainly caused consternation across the world.
But has Trump’s rhetoric affected the credit markets? In the space of a couple of days it has had an impact, though it could hardly be described as incendiary. The Markit CDX.NA.IG index widened 2bps to 61bps, while the Markit iTraxx Europe gave up 5bps to trade at 57bps. Geopolitical risk has triggered panic on many occasions in the past, but this wasn’t one of them.
And yet there were signs that this latest contretemps can’t be dismissed entirely. Volumes in the indices were high – the 878 trades reported in the CDX IG on August 9 constituted the second highest daily turnover since the roll in March. The 5bps point move in the iTraxx Main, while modest in comparison to historical oscillations, was significant in today’s low volatility environment.
And then there is the country feeling North Korea’s aggression most intensely – its southern neighbor. South Korea’s sovereign CDS spreads widened 8bps to 65bps, a level not seen for well over a year. Japan has also been the subject of Pyongyang’s ire in the past, and any attack on Guam – a US island territory threatened by North Korea – would likely see missiles pass over Japan.
But Japan’s spreads barely budged, moving just 1bp wider to 27bp. In fact, there was little sign of contagion across Asian sovereign spreads. It seems that credit markets are taking the heated rhetoric in their stride and expecting it to blow over in the coming days. This seems to be the opinion of most experts that attempt to make sense of North Korea’s bewildering pronouncements.
If this is indeed the scenario that plays out, then we can expect spreads to recover the ground that was lost. But if Trump and Kim Jong-Un become more bellicose and the risk of an “accident” increases, then we could see a more severe and prolonged bout of volatility. Europe has failed to provide the political risk catalyst predicted by many at the start of the year. We can hope not, and it seems improbable, but the flashpoint may emerge from Asia.
Contact: Gavan Nolan
Gavan.Nolan@ihsmarkit.com



Latest news

Open Tab
Leveraged loans keep running up a tab. Senior direct lending already knows what it owes.


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.