


Private Debt Intelligence – 10/16/2017

Private Debt Dry Powder Reaches New Record
Chart
Download Data
[wpdm_package id=’14694′]
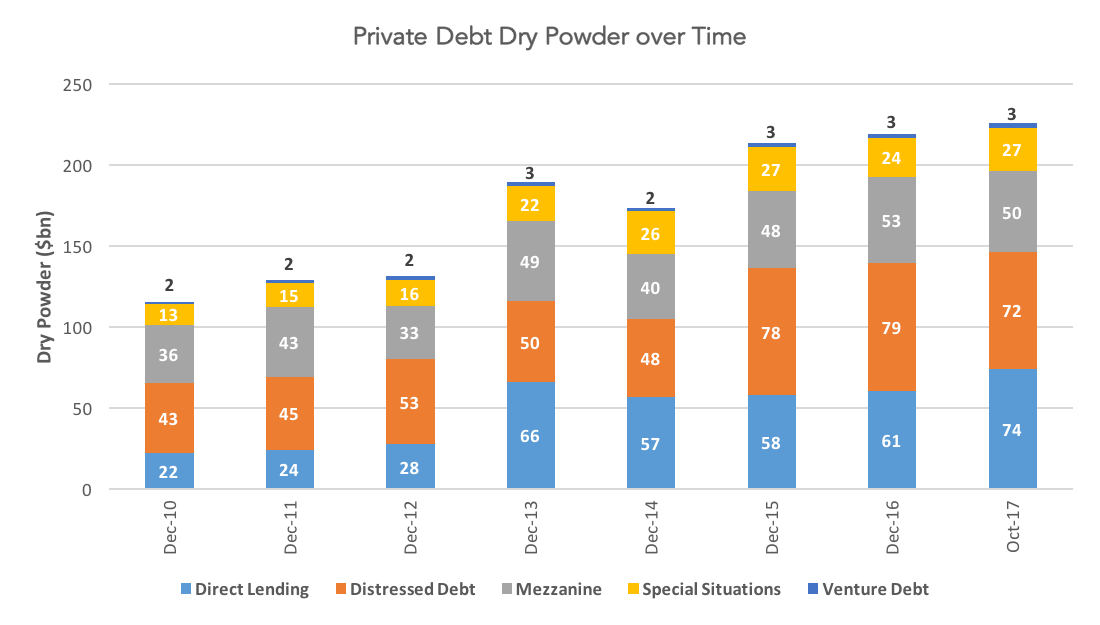
The capital available to be deployed by private debt fund managers has reached a new record in October 2017, peaking at $226bn. This is in part due to record fundraising in Q4 2016, followed by robust quarterly fundraising in 2017 so far – over the 12 months to the end of September, fund managers have secured $126bn from investors. It may also be indicative of a challenging deal making market, with high pricing making it more difficult for fund managers to find attractive opportunities into which to deploy capital. Ultimately, managers may deploy accumulated capital at a slower rate, as they endeavour to find the most effective opportunities available.
However, it is important to note that dry powder is not growing evenly across the industry, and in fact different fund types are seeing opposing trends in the build-up of available capital. Record-breaking dry powder is driven almost exclusively by direct lending funds: having stood at $61bn at the end of 2016, dry powder for direct lending funds has risen to a record $74bn as of October, an increase of over a fifth. This sharp uptick may be the source of some of the concern felt by fund managers and investors alike about the available capacity of potential deals for direct lending vehicles. However, Preqin research would suggest that robust deal making among small- and mid-cap private equity buyout funds is producing enough opportunities to more than absorb currently available dry powder.
By contrast, distressed debt and mezzanine funds have seen their dry powder decline from the end of 2016. Mezzanine dry powder fell from $53bn in December 2016 to $50bn in October, while available capital for distressed debt funds fell from $79bn to $72bn in the same period. This comes despite strong fundraising for distressed debt funds in 2016 and 2017 YTD, and record fundraising for mezzanine funds in 2016. This would indicate that fund managers of these vehicles are finding suitable deal opportunities into which to deploy capital at a faster pace than even record fundraising can keep pace with – a further strong indication of the potential and strength of the private debt market.



Latest news


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.