



Download PitchBook’s Report click here.
Our friends and clients in the PE industry are a cheery bunch. No matter how much we analysts fret about deal multiples or the tepid exit market, buyers and sellers find reasons for optimism. Exhibit A comes from our latest PE Deal Multiples Report, released just before the holidays (linked here in case you missed it). Asked if current deal multiples are within range to achieve “typical PE fund returns,” 52% of respondents marked one of the “yes” options, including 8% who said “yes, very much so.” The other 44% chose the slightly more modest “yes.” We’ve stopped being surprised about this one—the same question asked earlier in year came back with 68% somewhere in the “yes” column—but we still scratch our heads a bit.
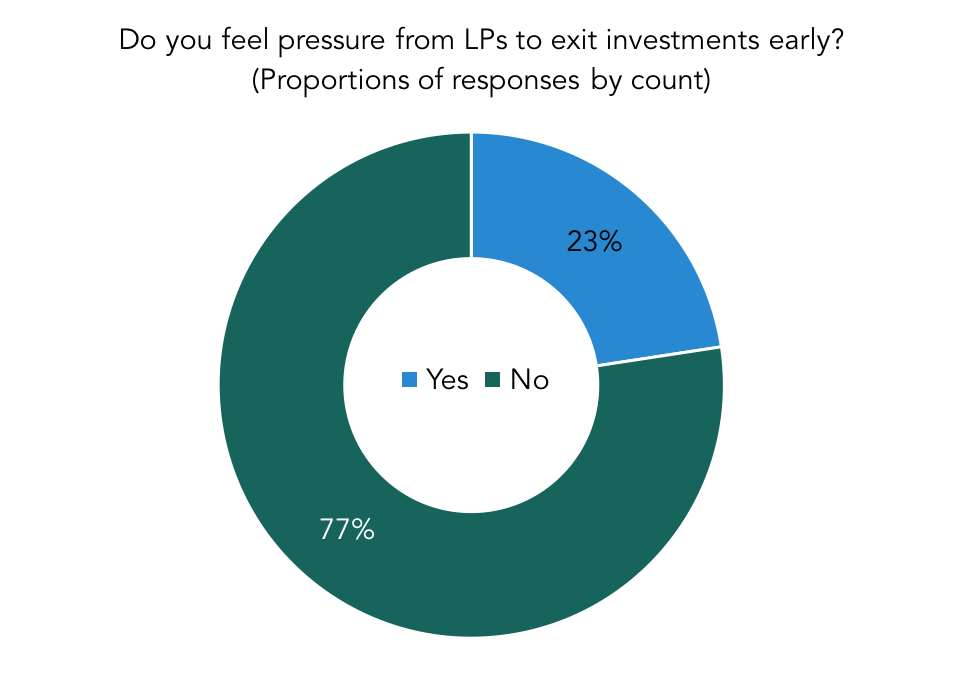
On the heels of the PE Deal Multiples survey was our annual PE Crystal Ball Report, which gauged investor sentiment heading into the new year. Among other standout responses, 77% of those surveyed felt no pressure from LPs to exit investments early. For investors who have held portfolio companies longer than expected, the number one reason for doing so was due to “assets continuing to appreciate/perform well.” That meshes with a similar question in the Deal Multiples survey: Over the past three quarters, at least 60% of respondents anticipated revenue improvements of more than 10% for their companies in their first 12 months under ownership. Taken together, to some degree, those rosy responses help explain the industry’s general mood—much of PE’s current inventory is performing well, and has likely been generating big dividends for its PE sponsors in a record-low rate environment. LPs aren’t lacking in cash, with record PE distributions being recycled back to them. Taken at face value, it’s a little easier to see the glass as half full.
Still, it’s worth wondering if the flood of LP distributions is masking underlying strains in the market. The customer seems happy at the moment, but that’s only part of the equation. Entry prices are high and show no signs of slowing, and the IPO and M&A markets are always one macro development away from closing. It will be interesting to see if all this optimism disappears if LPs find a reason to change their tune about the asset class.
Contact: Alex Lykken
alex.lykken@pitchbook.com




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
