



Download PitchBook’s 1Q 2018 US PE Middle Market Report click here.
As technology continues to upend market after market, private equity has shifted its focus from the bottom line to the top line. The onus to create value, in other words, relies more on revenue growth today than it has in the past. High doses of leverage combined with cost-cuts are no longer a reliable playbook. Focusing on efficiency measures in a sector like retail, for example, is like catching a falling knife. Technology is doing a fine job of that already.
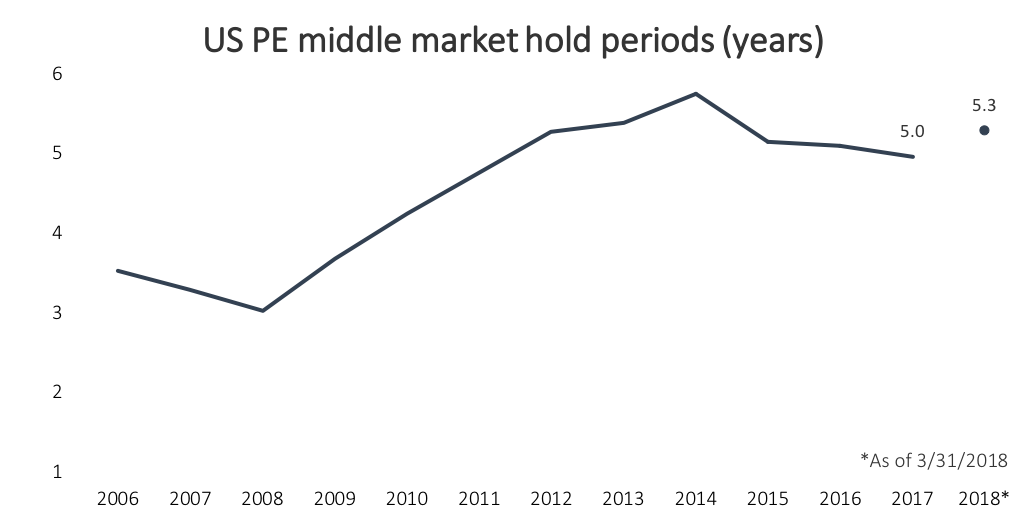
Growing is tougher than cutting, and it’s even tougher to grow meaningfully in five years compared to plucking low-hanging fruit via cost cuts. To generate sufficient revenues in today’s market—and, when it comes time to sell, in tomorrow’s market—more deliberation is necessary in the due diligence phase. We’ve discussed in the past that PE sponsors are identifying add-on targets ahead of closing their platform acquisitions. Add-ons are an easily tracked datapoint, but there’s a similar trend that often flies under the radar: PE firms are getting much better at due diligence, particularly using predictive data analytics. A fancy term, predictive analytics in PE context boils down to analyzing how specific clients or users interact with a target company’s product or service.
Age, income and location are all helpful datapoints, but perhaps most insightful of all is a customer’s buying history. Which customers buy more or more often, and which customers are a bit less active? Which clients or client-types come with higher margins, and which are costlier to serve? Most important, how are company resources being allocated to those specific products, services or clients? This isn’t quite the same as identifying a factory to close or a business line to shut down. Those were blunt instruments that worked effectively when those situations were more common. But private equity has been active for almost forty years, and we shouldn’t be surprised to see fewer “easy” cases after such a long and profitable run. The opportunities today are less obvious, and more likely to hinge on boosting specific revenues or margins by 10%, 20%, or 30%. That might not seem like much, but knowing that certain resources can be allocated differently can make the difference between bidding confidently for a target versus passing on it altogether. Or even worse, winning the bid and figuring things out as you go.
Contact: Alex Lykken
alex.lykken@pitchbook.com


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…