



Download PitchBook’s 2Q 2018 US PE Middle Market report here.
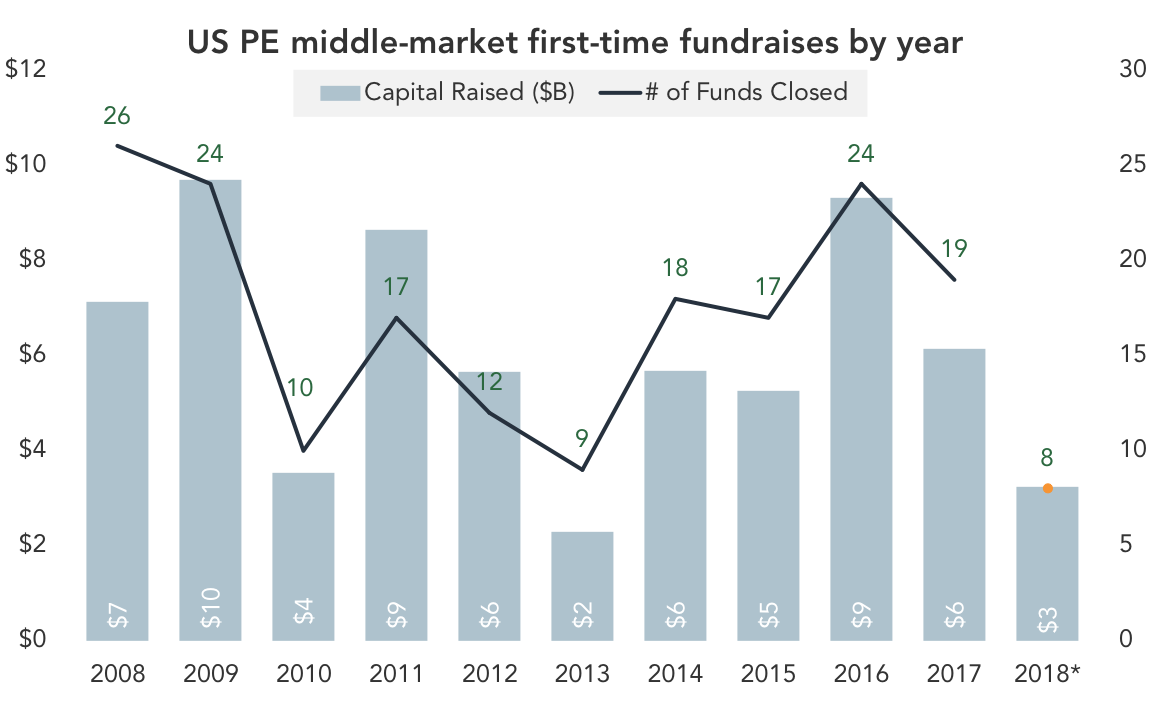
We discussed last week the faltering fundraising market in the overall private equity market. But like most PE-related discussions, there’s usually a discrepancy between the PE middle market and the PE market as a whole. That’s especially true when looking at first-time fundraises, which continued their strong run through H1 2018. Another eight debut PE funds have closed so far this year, raising a combined $3.2 billion. Unlike the broader PE fundraising market, which is on pace for a significant decline this year, first-time fundraising in the middle market is humming along. All things considered, it makes sense that new firms would make their debuts in the middle market. Fund sizes are more modest and strategies are more attuned to smaller companies in more niche segments. That said, the relative health of the first-time fundraising market bodes well for the industry going forward. The teams that opt to put out their own shingles take an opportunity risk in doing so. Those new executives, now masters of their own domains, are leaving comfortable positions at brand-name firms.
But they’re hungry to prove themselves, and somewhat paradoxically, they’re often more inclined to strike out on their own when times are good. In many cases they may have benefitted personally from a large exit or two and now have the wherewithal to go solo. In other cases, new managers are looking to “go back to their roots,” especially when it comes to check sizes. Today’s high-end market and its correspondingly high funds often require minimum equity contributions targeting only the largest of opportunities. But there’s a difference between being pressured to write $250 million checks due to fund economics and writing $25 million checks for smaller, more compelling opportunities. Anecdotally, first-time managers help recycle entrepreneurial energy back into the private equity industry, which has grown so large that many of the biggest names are converting to C-corps. New blood is needed, and another sign of health is the LPs who are signing on to these new strategies. First-time funds need to demonstrate, if not prove, that they’re capable of closing on deals, no matter how green they are. The numbers suggest that rookie managers are persuading LPs to take a chance on them, a good sign.
Contact: Alex Lykken
alex.lykken@pitchbook.com


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…