



Download PitchBook’s 2Q 2018 US PE Middle Market report here.
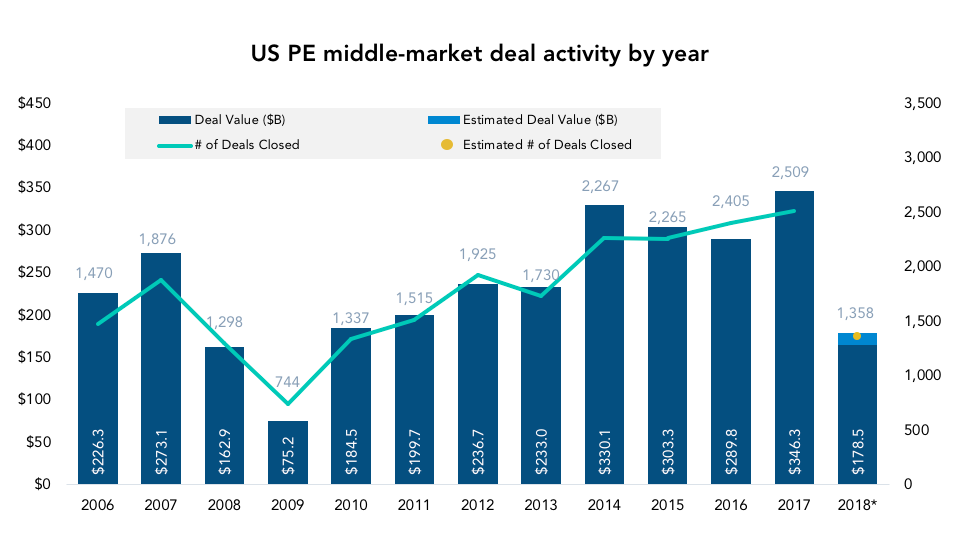
There are many themes worth discussing in the middle market, but one trend we can’t ignore is its consistent strength over the years. On cue, 2018 is on pace for yet another record year for both counts and value, coming on the heels of a blockbuster 2017. Both figures were ahead of H1 2017 figures—the 1,358 deals worth a combined $178.5 billion were 16% and 5% increases, respectively, over the same period last year. If past is precedent, the back half of 2018 will be stronger than the first half, as several past years saved their best quarters for last. Going back to 2010, fourth quarters posted the highest quarterly value totals six out of eight times, and one of those exceptions (2014) saw its best quarter in Q3. Moreover, there’s little reason to expect a change of pace in the near-term when taking recent fundraising numbers into account. Since 2010, only four quarters have seen at least $40 billion raised for MM-focused buyout funds. Three of those four quarters have been recent (Q4 2015, Q1 2016 and Q4 2016), so the next two to six quarters should see high levels of investment activity as those new pools are deployed.
The middle market has accounted for nearly 70% of all PE capital invested year-to-date. We don’t expect that percentage to stay that high by year-end, as several announced multi-billion-deals have yet to close. That said, with more attention and LP capital heading to the middle market, we expect to see at least half, if not more, of all 2018 PE activity to reside in the $100M-$1B range. Two macro developments are worth considering going forward: the ongoing tariff situation that will affect broad swaths of the middle market, and the steady increase in interest rates coming from the Fed. Interest rates in particular are worth noting, as higher interest payments can have an outsized impact on cash flows over time. Cash flows are an important component when valuing portfolio companies, and if interest payments siphon off enough cash flows under ownership, sponsors run the risk of exiting at a lower valuation than anticipated. Operational improvements will be more important than ever in the years ahead.
Contact: Alex Lykken
alex.lykken@pitchbook.com


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…