



Download PitchBook’s Report here.
Secondaries fundraising continues apace, gathering another $26.3 billion through early Q4. That puts 2018 slightly behind last year’s record, but this year will still mark a third consecutive year with strong numbers. As a strategy, secondaries have garnered attention recently—buy-side LPs are pushing for PE exposure at the right price, as secondaries offer discounts that could produce sizable profits down the road. In aggregate, secondaries funds have consistently produced positive net cashflows over the years, help mitigate the oft-cited J-curve, and provide a valuable tool for LPs looking to keep their allocations intact. On the other hand, many sell-side LPs are making a concerted push to sell their holdings to lock in existing profits, especially for older vintages. For many of them, tail-end returns have not been as strong as hoped, and in some cases are unnecessarily weighing down portfolios. Many sellers are heading to market now while prices are healthy—in the event of a downturn, holding on to older, underperforming funds for another cycle is less than ideal, to say the least.
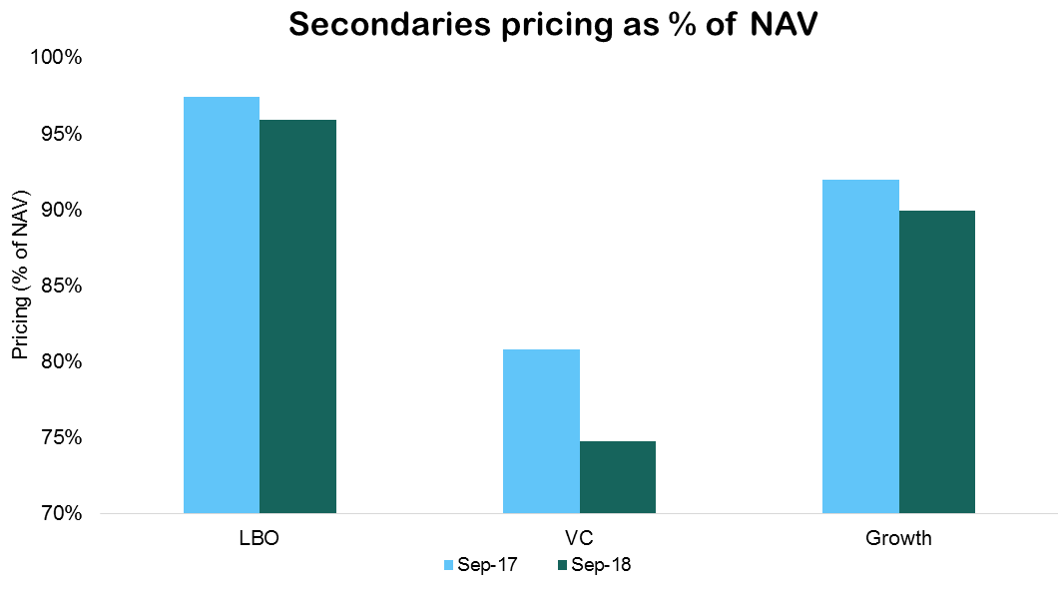
The accompanying chart comes courtesy of Setter Capital, which highlights the consistently strong demand for PE secondaries in particular. YoY, discounts to NAV have fallen only marginally, 97% to 96%. Secondaries strategies in other markets aren’t blooming in the same way they are in private equity, where buyers are jockeying over more fully priced stakes and much narrower discounts. The sheer size and importance of the PE market to alternatives portfolios explains much of this discrepancy. But beyond that, secondaries transactions are largely circumstantial between the buyer and seller, and aggregate numbers don’t provide a helpful narrative in the same way that other data points do. The numbers depend on the handful of opportunities that come to market, which will continue to trickle in as long as different LPs face different circumstances within their own portfolios.
Contact: Alex Lykken
alex.lykken@pitchbook.com


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…