



Download PitchBook’s Report here.
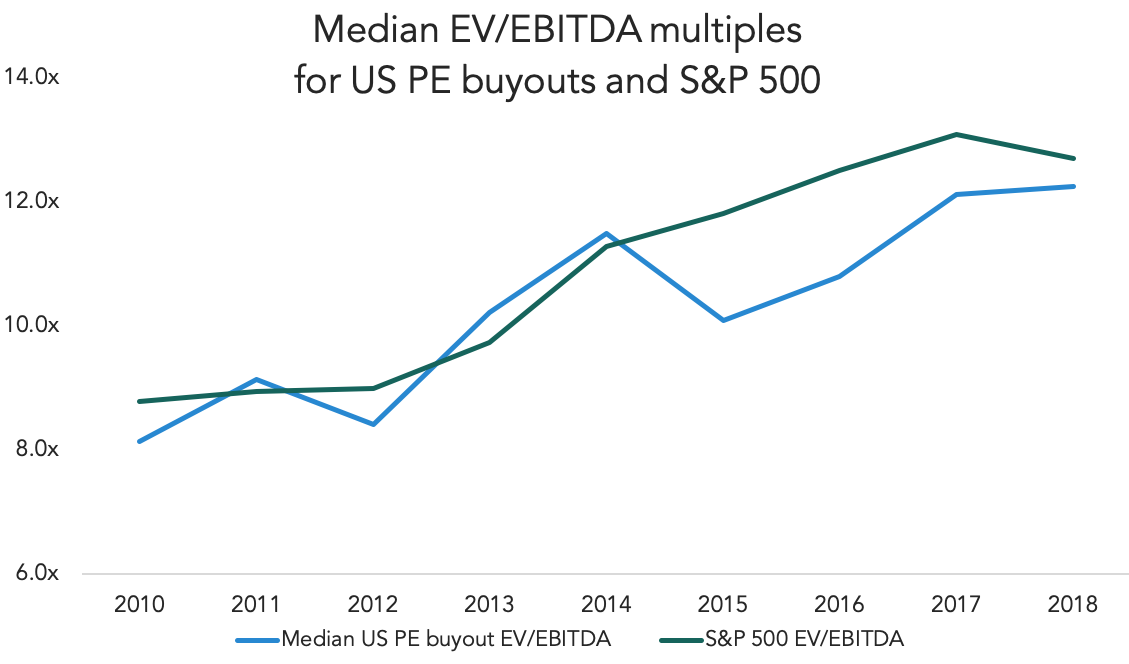
Middle-market PE multiples barely budged last year. We didn’t expect them to, and we don’t expect them to come down much in the near-term either, barring some significant macro development.2018 marked the sixth consecutive year with double-digit purchase price multiples, clocking in at 11.4x against 12.0x in 2017. A decline, but not much of one.
PE valuations and dry powder levels are the two most discussed aspects of the industry today, and they are not unrelated. They symbiotically feed off each other, driving investors to pay higher markups for deals and raise more capital to prepare themselves for more of the same going forward. But PE valuations don’t operate in a vacuum, and the LPs who ultimately finance them are free to look elsewhere to park their money. They don’t particularly want to—alternatives are a staple in most portfolios and provide much-needed, uncorrelated returns to equities. But in exchange for the liquidity tie-up, PE’s selling point is higher returns. That becomes significant and much harder to achieve when entry prices are higher. If LPs are paying comparable prices for their private and public holdings, PE’s lack of liquidity comes into focus. The Financial Times pointed out the problem last year: “Industry observers also said that a narrowing of the gap would lead some to reassess their exposure to private equity.” That’s true, though it would be overstatement to etch it into stone ahead of time.
Contact: Alex Lykken
alex.lykken@pitchbook.com


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…