



Download PitchBook’s Report here.
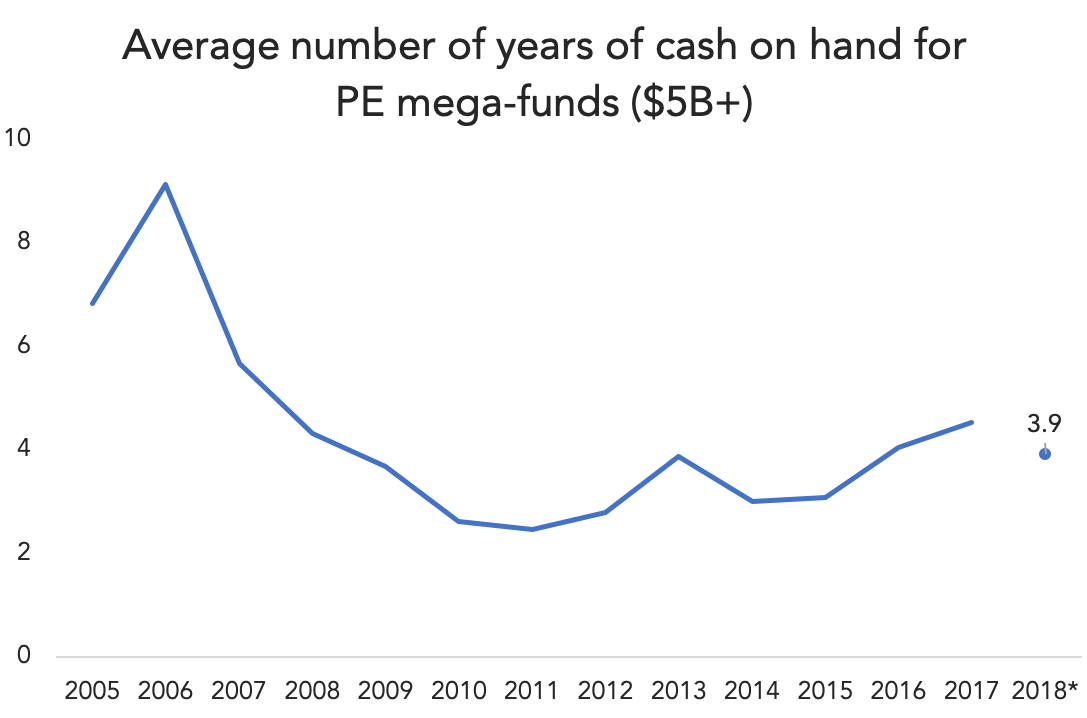
It seems remarkable now, but in 2006, PE mega-funds (of over $5B) had almost ten years of cash on hand to invest at that year’s investment pace. A decade of dry powder is a lot, even for private equity. To see the average drop down so quickly in 2007-2008 is just another testament to how crazy the pre-crisis years were. The 9.1-year average in 2006 was down to 4.3 years’ worth of dry powder by 2008. Say what you will about PE managers at the time, but they certainly didn’t sit on their hands.
Headlines in recent years have heralded the return of the mega-fund, justifiably. Apollo broke the all-time fundraising record in 2017, raising $24.7 billion for its ninth flagship fund. Other firms are back in a big way, too. But despite the records, cash-on-hand levels are actually below where they were pre-crisis. What’s more, drawdown rates have been consistent and consistently reasonable going back to 2010, oscillating between 2.5 to 4.5 years of cash on hand in that timeframe, according to PitchBook’s most recent analyst report. The mega-market (if we can call it that) more than doubled its dry powder stockpile between 2015 and Q3 2018, rising from $177.8 billion to $322.3 billion. To square all these datapoints, the largest PE managers are investing at an efficient pace despite a rush of new capital and relatively few investment targets. It helps to have large teams in place to handle all that money, and in some cases more than one mega-fund under the same roof. Still though.
One possible interpretation of all these rosy datapoints—this is probably the best of times for mega-funds, and not necessarily in the bubbly sense. The current climate is certainly much more stable than pre-crisis days. Somehow we got acclimated to all those multi-billion-dollar headlines that were written—on average, once every other week. 27 US deals of at least $5B were done in 2007 alone, while only 7 have been done halfway through 2019, despite mega-fund dry powder levels being substantially higher this time. The animal spirits are gone, even if the dry powder came back.


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…