



Download PitchBook’s Report here.
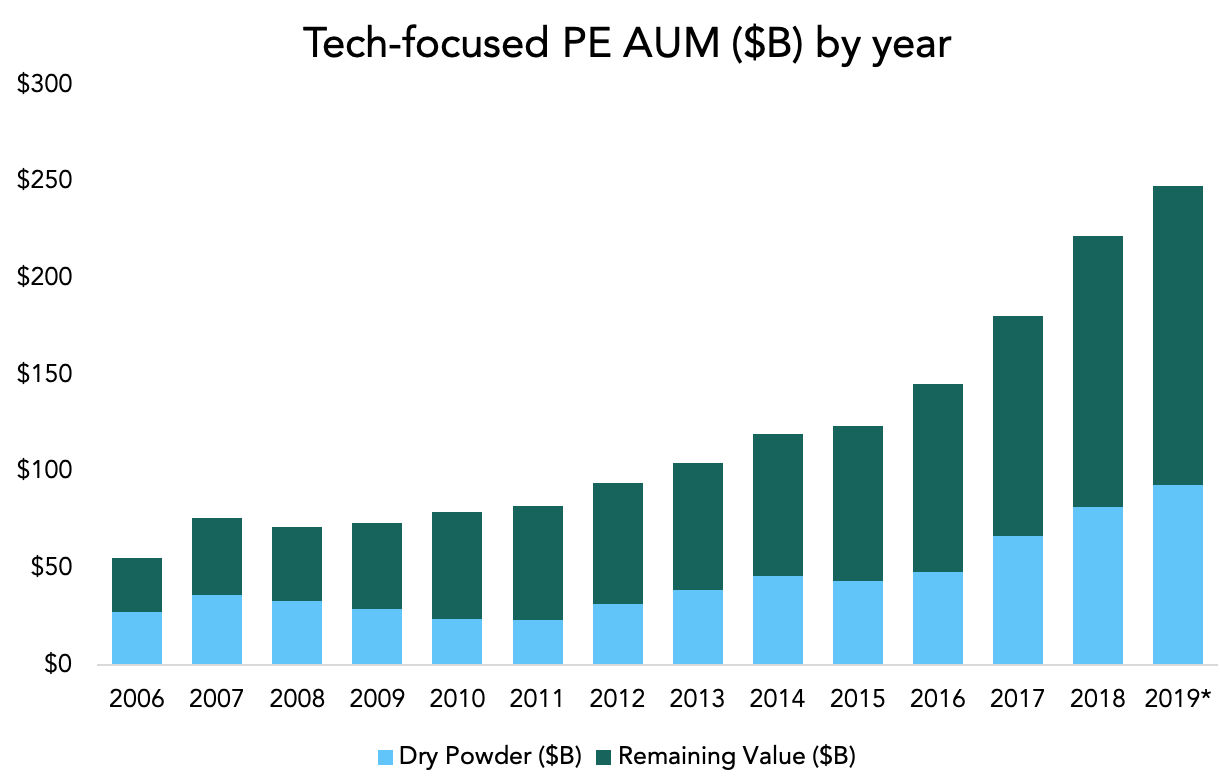
Tech-focused dry powder has almost doubled since 2016. The latest returns data available is through March of this year, when it totaled $93.1 billion across North America and Europe. That marked a 93% increase since 2016’s cumulative $48.2 billion, according to PitchBook’s latest analyst note on tech funds. The vast majority of PE tech AUM is housed in the US; over the past 20 years, North America has contributed over 95% of tech-focused PE capital between the two continents. Tech funds themselves are starting to command a bigger share of the overall PE fundraising market, comprising nearly 22% of all PE capital raised so far this year. Boosting that percentage were mammoth raises by Thoma Bravo and Vista Equity, two of the so-called “Big Three” tech firms. Silver Lake is the third, but it will probably be a Big Five at some point, with firms like Francisco Partners and Insight Partners gaining speed.
Tech buyouts have mostly been high growth/high price-tag affairs in recent years. Relatively few of them are “struggling,” negating PE’s historical role as the rescuer. Tech more broadly is also volatile, and market trends can always change with little notice. Add to that the fact that a large swath of tech companies are venture-backed, and Silicon Valley is awash in available capital. Many tech companies don’t need PE’s traditional skillset or its money, but the numbers continue to rise at a rapid clip. Buyout activity from the likes of Vista, Silver Lake and Thoma Bravo seems on par with M&A activity from the likes of Google, Amazon and Microsoft.
The landscape has changed, not only because of technology’s promise as a sector but also because PE-focused tech funds’ outperformance. Over the past decade, tech-focused PE funds have produced IRRs more than five percentage points higher than non-tech buyout funds and ten percentage points higher than non-tech PE growth funds. Results like those all but guarantee a strong fundraising market for the next ten years. Perhaps we’ll see more tech companies position themselves as buyout targets instead of M&A targets going forward, emphasizing a healthy balance of growth and profit instead of groundbreaking ambition and possible post-IPO disappointment.


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…