



Download PitchBook’s Report here.
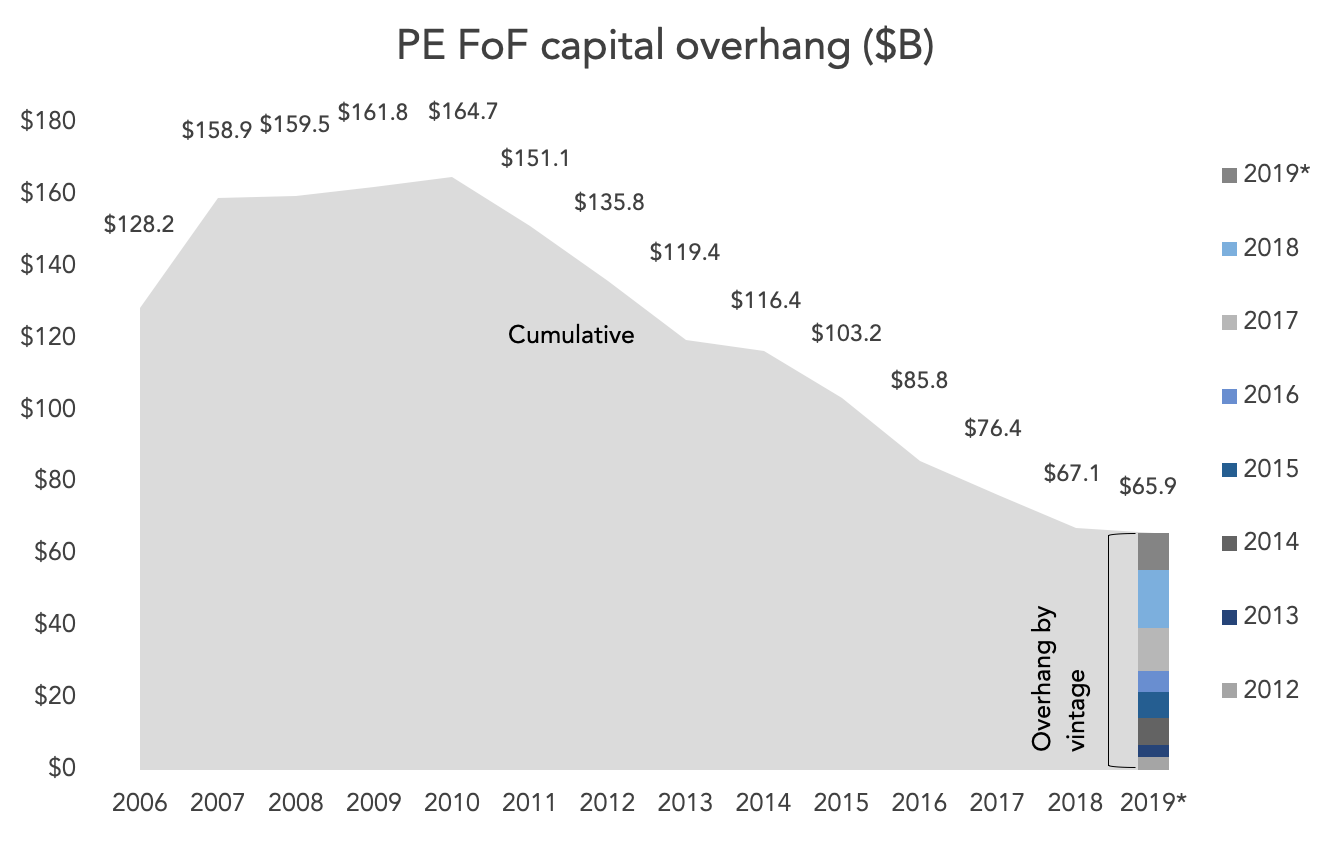
We’ve wondered before if funds of funds are becoming obsolete. Perhaps a hyperbolic word choice but probably only a couple standard deviations from the truth. FoF fundraising has nosedived over the past decade, as has its industry clout. Our most recent overhang numbers, dissected in PitchBook’s just-released Private Fund Strategies Report, are a fraction of what they were in 2010. The FoF industry had accumulated $165 billion by then; today’s figure is a mere $66 billion. It’s one of the few private equity datasets that has consistently been down and to the right, year after year.
Industry survivors had to adapt to new demands. Their clients—LPs—have more options in terms of intermediaries; investment banks like Goldman Sachs have developed in-house manager selection teams that operate like quasi-FoFs. A few big LPs can throw their weight around in different ways. CalPERS, for instance, has a series of funds in its Domestic Emerging Program, managed exclusively by GCM Grovesnor. Fee terms are presumably much better than the standard FoF structure. For LPs that don’t have CalPERS-level resources, FoF managers have bent over backwards to woo them. One approach aimed at smaller LPs has been the creation of annual programs, which guarantee that commitments can be made regardless of timing. A product is always available to LPs, in other words. Other managers have acquiesced in their own ways. Azalea Investment Management recently closed on $650 million, well north of its $400 million target, thanks to high demand from HNW clients and commitments as low as $200k. Azalea developed a “well-defined exit mechanism” that offers clients a shorter investment tenure compared to typical FoFs, “thus overcoming another traditional deterrent of investing in PE funds.” There must be dozens of other examples out there of FoF managers getting creative to get more funds off the ground.
Funds-of-funds may not play the role they once did—the market has found alternative ways of diversifying that don’t involve that expensive, second layer of fees. Off-the-shelf products are easier to manage but harder to sell compared to ten years ago, but there’s always demand for tailors.




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
