



Download PitchBook’s Report here.
At the outset of the quarantines, at least one market observer—yours truly—believed add-ons would hit the pause button after two torrid years of deal flow. The assumption: it was hard to imagine too many add-ons being done when existing portfolio companies had so many sudden issues of their own. Any acquisition typically takes several months to complete, and healthcare officials were penciling in several months of quarantines ahead. Why add more uncertainty to the mix, especially when add-ons frequently turn sour even in the best of times?
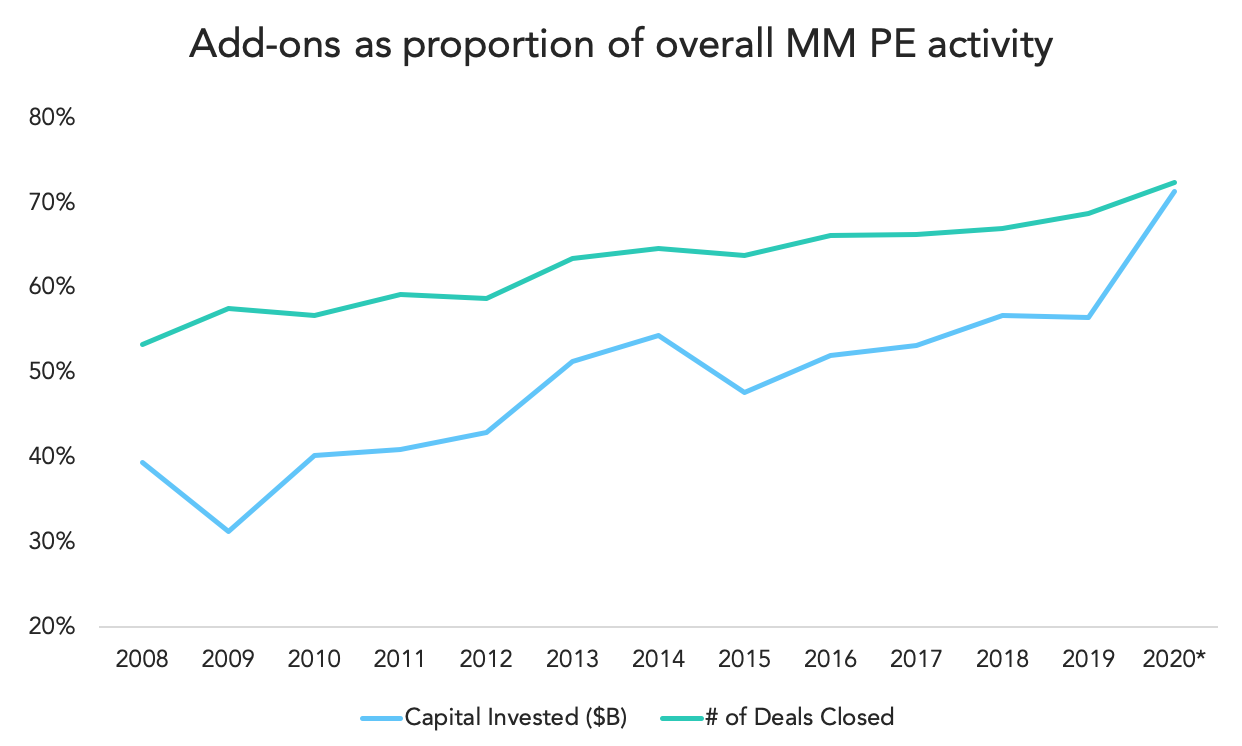
The middle market didn’t agree. According to PitchBook’s latest US PE Middle Market Report, Q1 add-ons accounted for the highest percentage of capital invested in the industry’s history. Through the first quarter at least, an estimated 71% of all PE dollars went toward add-ons, while almost 73% of all Q1 transactions were add-ons compared to platform buyouts. By comparison, only 56.6% of all 2019 dollars went to add-ons, an almost 15 percentage point swing. Of course, that ratio is partially boosted by the fact that LBOs came to a halt in March. The denominator got a lot smaller, in other words. But the numerator—add-on volume—was relatively intact. 469 were done in Q1 totaling an approximate $70.1 billion. Neither figure is too far off 2019’s pace, which saw 2,264 done for a combined $269.6 billion. By the end of 2020, add-on totals may be the closest of all PE datapoints to historical numbers.
Market share is up for grabs, and many portfolio companies are starting to look ahead 6, 12, 18 months down the road. While sponsors undoubtedly see new platform opportunities on the horizon, they are intimately aware of how their existing companies are performing and how they can prepare them post-COVID. The numbers suggest they can walk and chew gum at the same time.


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…