


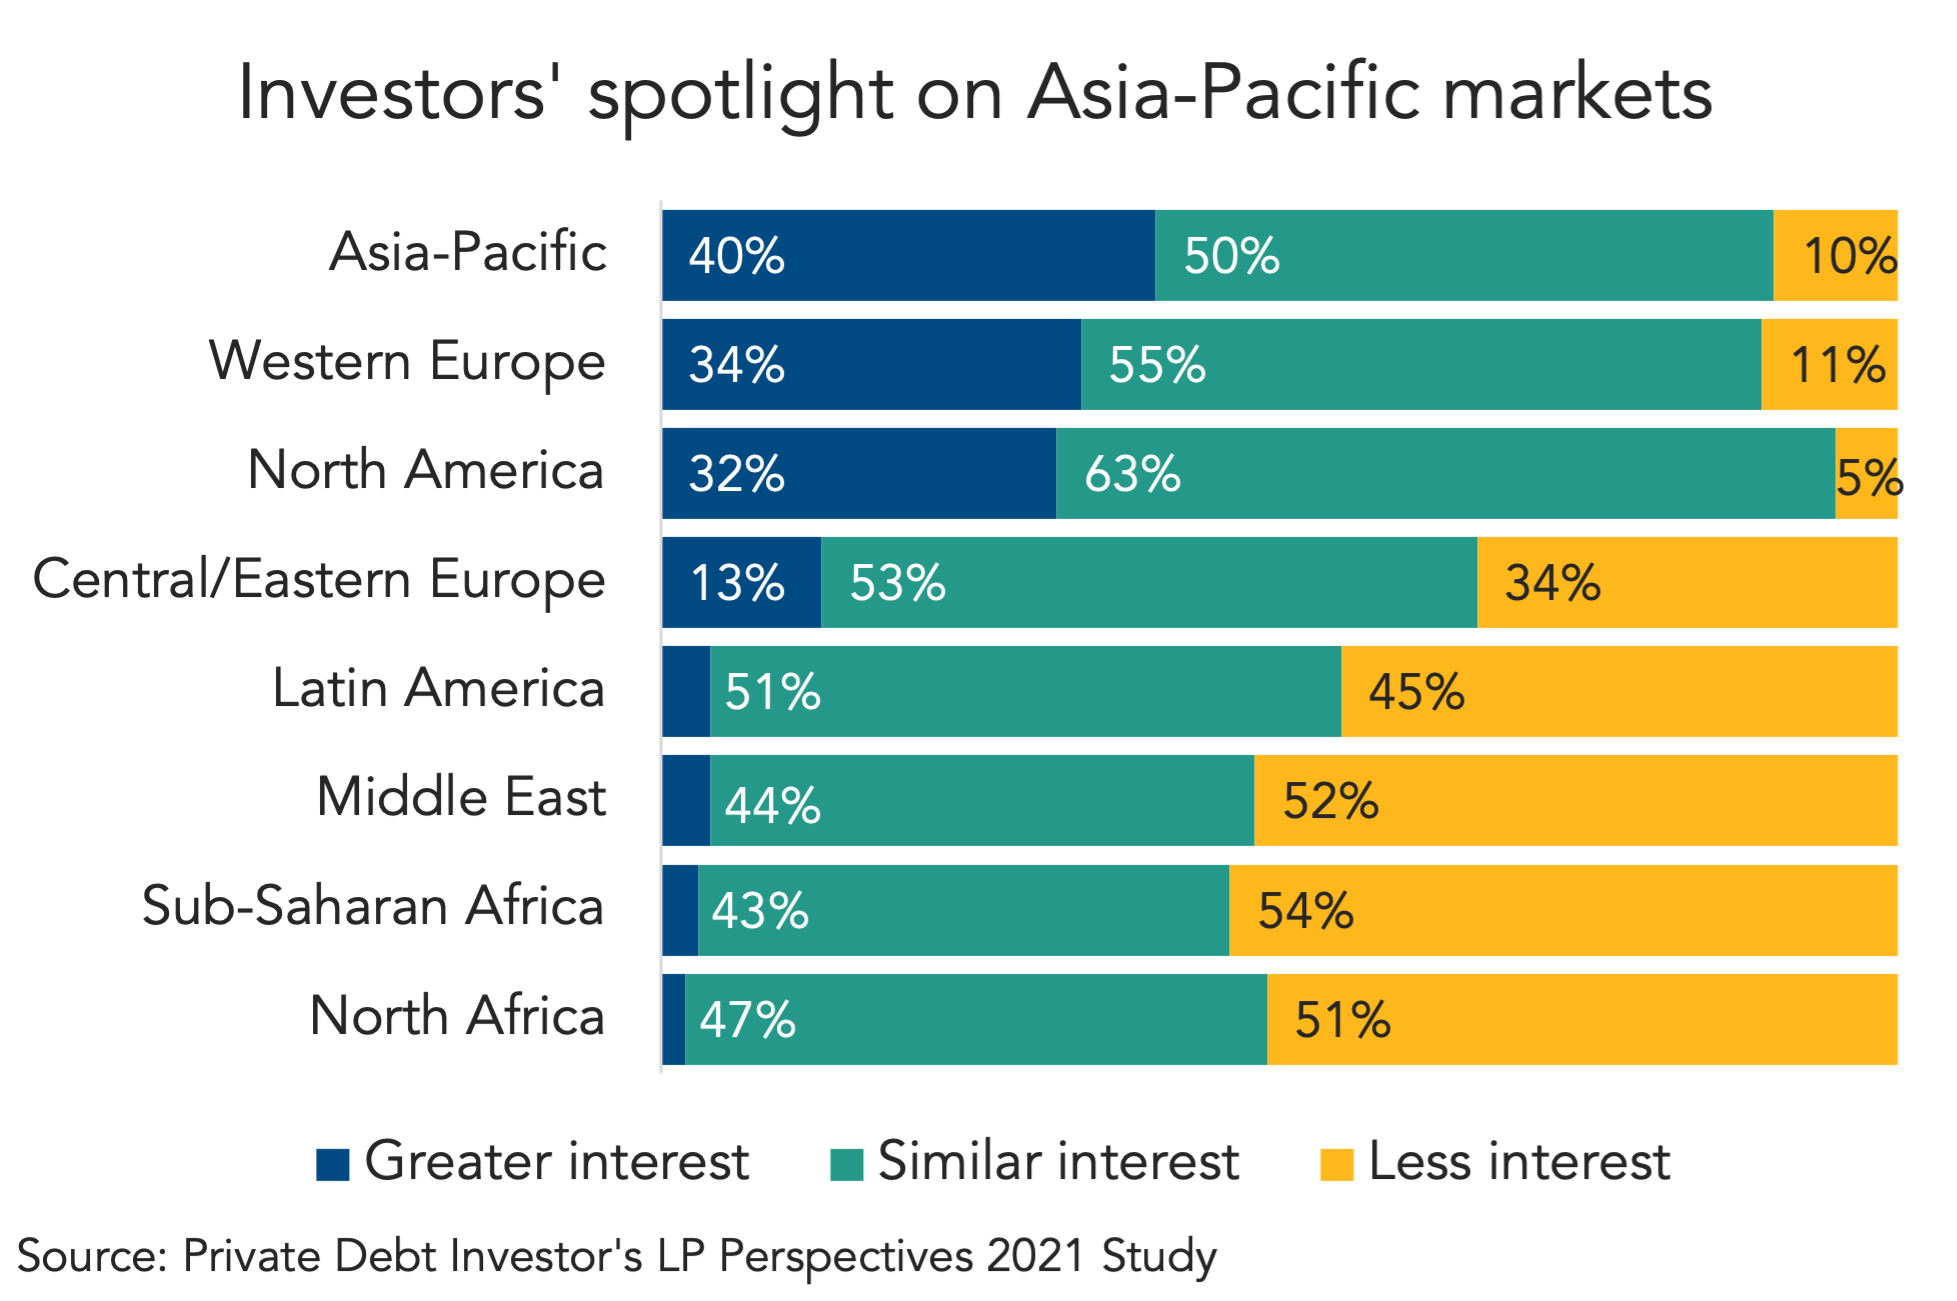
Investors have set their sights on the region, perhaps noting the tightness of the documentation.
Past research by Private Debt Investor has found Asia Pacific only accounting for around 5 percent of global private debt fundraising, with capital committed to the region a drop in the ocean compared with North America and Europe.
However, as our chart above shows, investor interest in Asia Pacific is perhaps greater than it has ever been. One of the reasons for this may be that documentation for private debt deals in the region has proved remarkably tight.
“It’s quite amazing, how different the documentation in Asia is compared to what you see in Europe and North America,” Nitish Agarwal, chief investment officer at Orion Capital Asia, a mid-market direct lender in Singapore, told us for a recent feature. “We still get away with very tight covenants. We have very strong cashflow ring fencing in our structures.”
In the areas in which Orion operates – every Asia Pacific market aside from onshore China – he says that every deal done by the firm has a debt to EBITDA maintenance covenant. There is also an interest coverage (EBITDA over interest expenses) covenant for 90 to 95 percent of deals, and a debt service coverage ratio (EBITDA over interest expenses plus principal payments) for about half.
These stricter terms apply not just to the headline issue of how many maintenance covenants there are, but also to the fine print. Private debt investors in the US and Europe often complain of finding the devil in the details. Perhaps the biggest area of controversy in these two regions is how EBITDA is calculated with respect to covenants.
As Agarwal puts it: “You can almost do a PhD in trying to figure out how to compute EBITDA: what to include, what not to include, and how to adjust this figure. But in Asia, things are relatively simple: we don’t do many of the adjustments that we have seen in Europe and North America.”
Of course, it would be wrong to characterise the US and Europe as covenant-free and weak on documentation across the board. Many managers in the mid-market would say they still routinely include at least the most important covenants. However, there’s no denying borrower power in these markets is nowhere near as advanced in Asia Pacific.


Latest news
US leveraged loan primary market stalls in 4Q26
Primary market activity in the US leveraged loan market has slowed sharply in the fourth quarter. Just $34.9b of new…

Direct lending M&A declines QoQ and YoY except in upper middle market
M&A activity declined 12% in the third quarter of 2026 to 296 deals, from 336 recorded in the second quarter.