



Download PitchBook’s Report here.
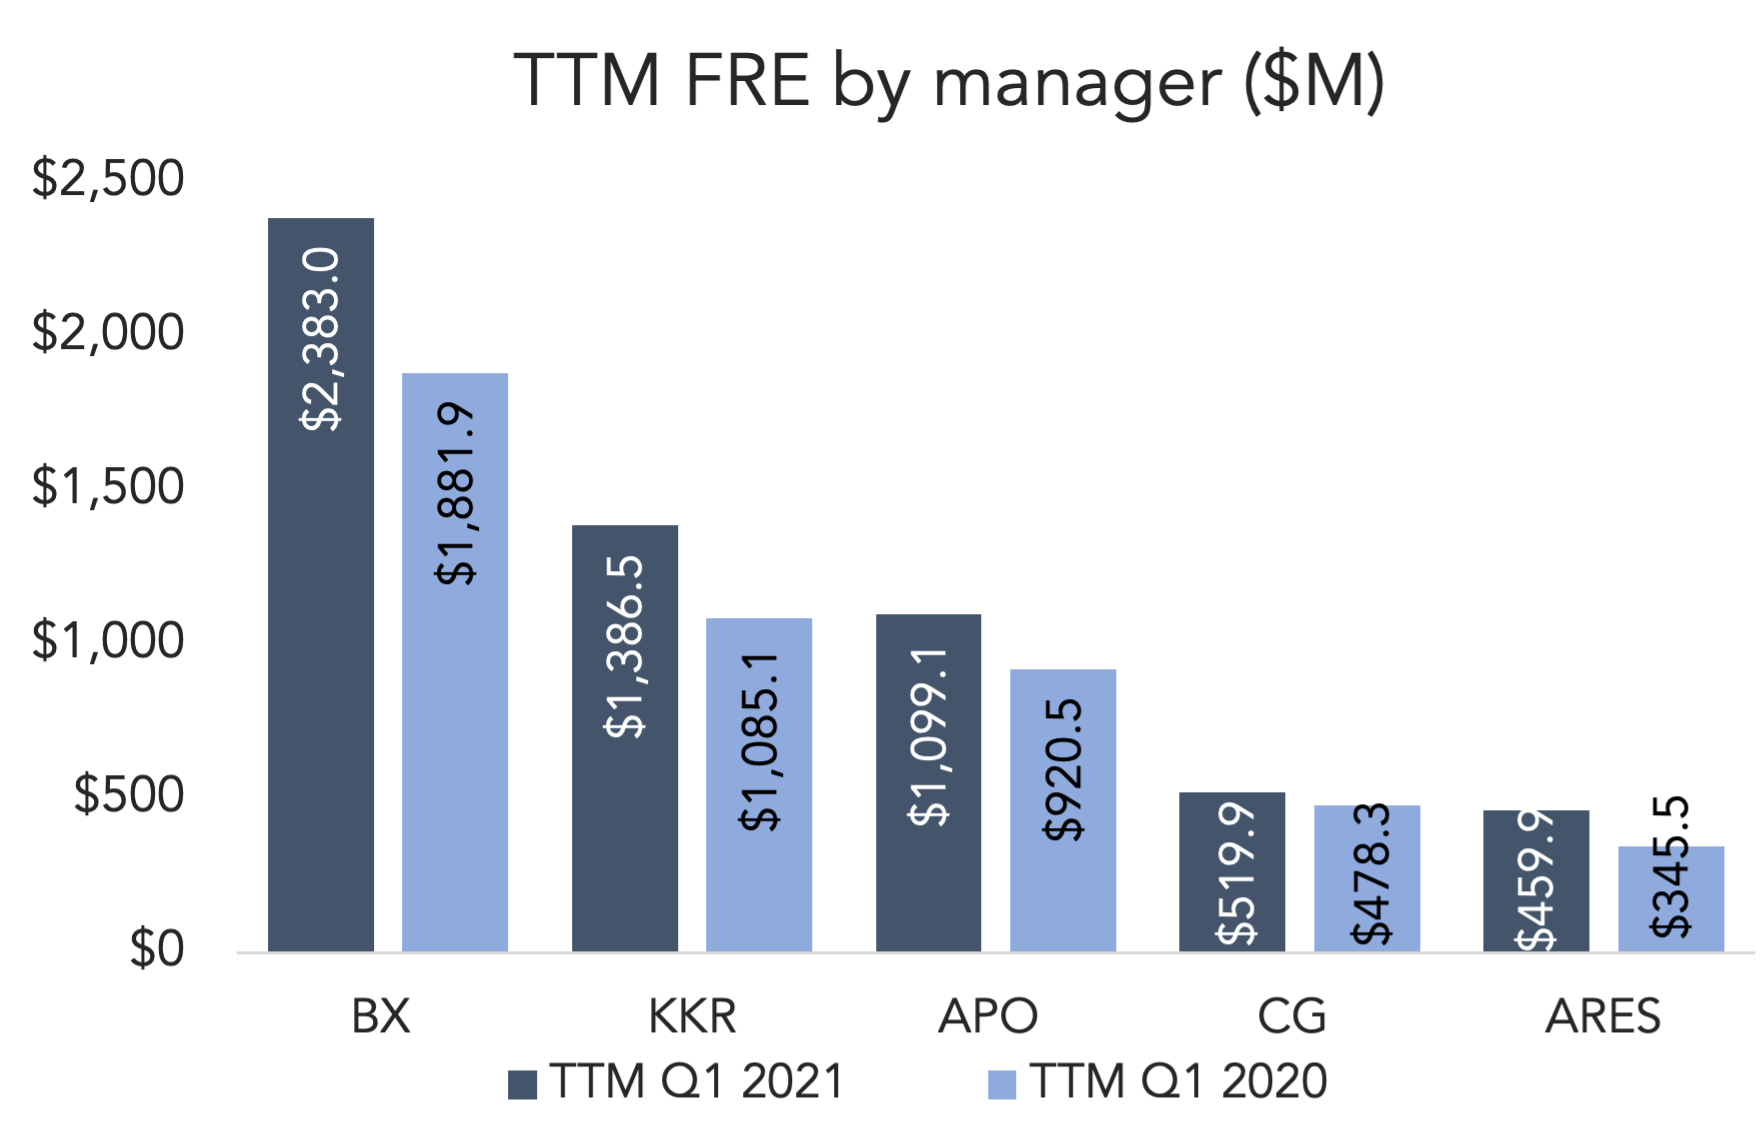
The “Big Five” PE firms that trade publicly—Blackstone, KKR, Apollo, Carlyle and Ares—had an impressive start to 2021. PitchBook’s latest analyst note takes a close look at their Q1 2021 financials, which showed sustained momentum coming out of the pandemic late last year. All five increased their trailing-twelve-month (TTM) fee-related earnings (FRE), a key metric for public PE managers. Blackstone’s YoY performance stood out, gaining 37.6% over Q1 2020, driven largely by the growth of its real estate core plus business and its record-setting buyout fund exiting its fee holiday.
Performance fee revenues were also up—almost across the board, with only Apollo missing. Blackstone’s performance revenue and investment income were so strong that fees were slightly lower as a proportion of TTM revenue compared to Q1 2020. All five firms notched gross performance of 15% or higher in Q1 2021, and all five had annual gross performances of 40% or higher. Apollo’s PE funds were up a staggering 66.5% in the past year.
Four of the five outperformed the S&P 500 (7.4%) in the first quarter, with KKR posting a whopper 24.4% return. Even if we’re talking a few share prices, there’s something to be said for beating the public markets in an environment like this.
(Past performance is no guarantee of future results.)


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…