



Download PitchBook’s Report here.
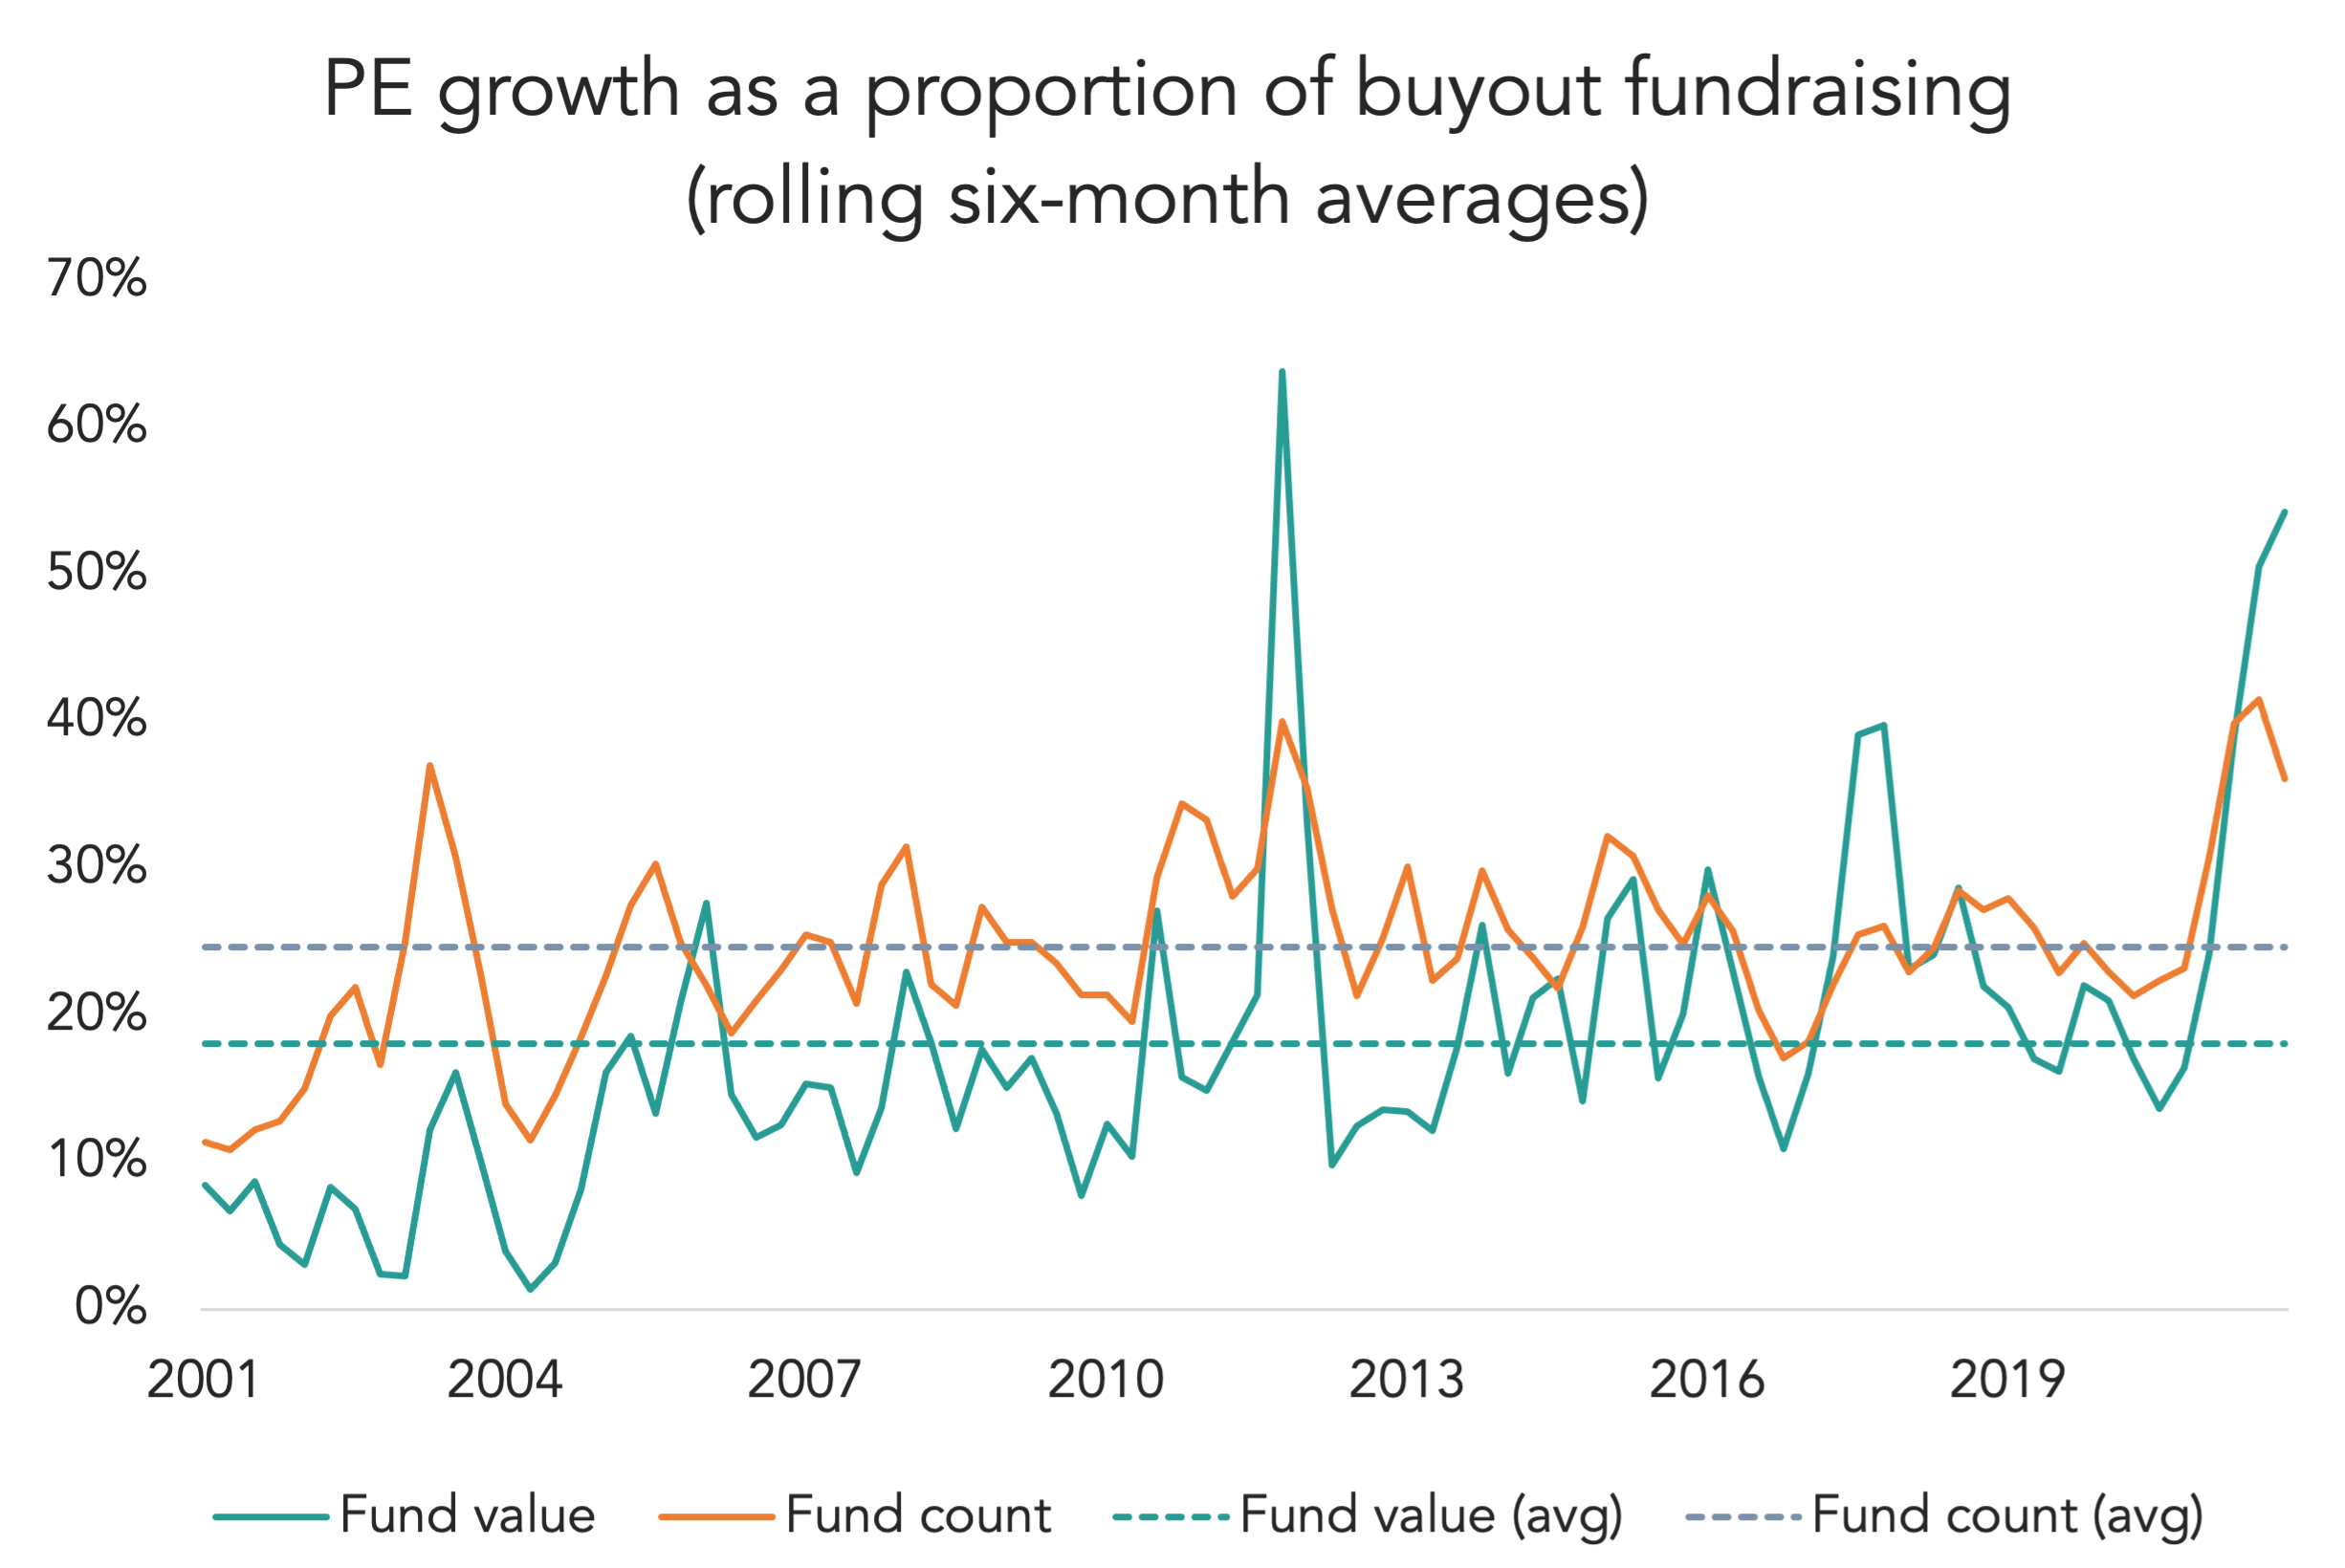
One of the many consequences of COVID was a shift in strategies among investors. The chart above is from PitchBook’s Quantitative Perspectives: US PE Enters a New Regime. It shows a relative spike in growth funds starting in mid-2021, relative to all fundraising done that year. The landscape had shifted at the time, with GPs finding growth-oriented opportunities and LPs anxious to get exposure to them. Both fund counts and fund value leapfrogged their historical averages as a result.
Fast forward a few months, the landscape feels like its shifting yet again. While there is a lot of dry powder out there, its worth remembering what much of it is earmarked for. In this case, growth-oriented funds that were raised in response to the COVID recovery. In other words, many of the funds available today were raised under different circumstances, even if those circumstances weren’t that long ago.
(Past performance is no guarantee of future results.)


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…