As the plain vanilla part of the private debt market comes under pressure, investors are turning their attention to more specialised approaches.
As we usher in 2023, PDI has been canvassing industry sources to glean a sense of the prevailing mood. Some of these conversations will make their way into our February cover story, which concerns the views of limited partners specifically. Without giving too much away, we can share some of the main takeaways.
The theme that became most abundantly clear was the caution around the market in general – unsurprising given the constant barrage of dour economic news. To compound this, even some of those LPs inclined to be supportive of private debt are finding themselves hampered by the denominator effect – wherein poor performance in public markets has resulted in LPs being proportionately overweight in their allocations to private assets.
While reporting of this phenomenon has mainly focused on private equity, it’s worth bearing in mind that not all LPs boast a specific private debt bucket from which to allocate. If the private debt portion is part of a private equity or even wider private markets programme, then the denominator effect is just as keenly felt.
Another observation is the challenge from high yield – at least to the relatively safer, lower-returns parts of the market. Sources pointed out to us that a yield of 8-10 percent from private debt was enticing while interest rates were bumping along at unprecedented lows. But that’s not the world we’re living in anymore, and returns on high yield are now back up at competitive levels.
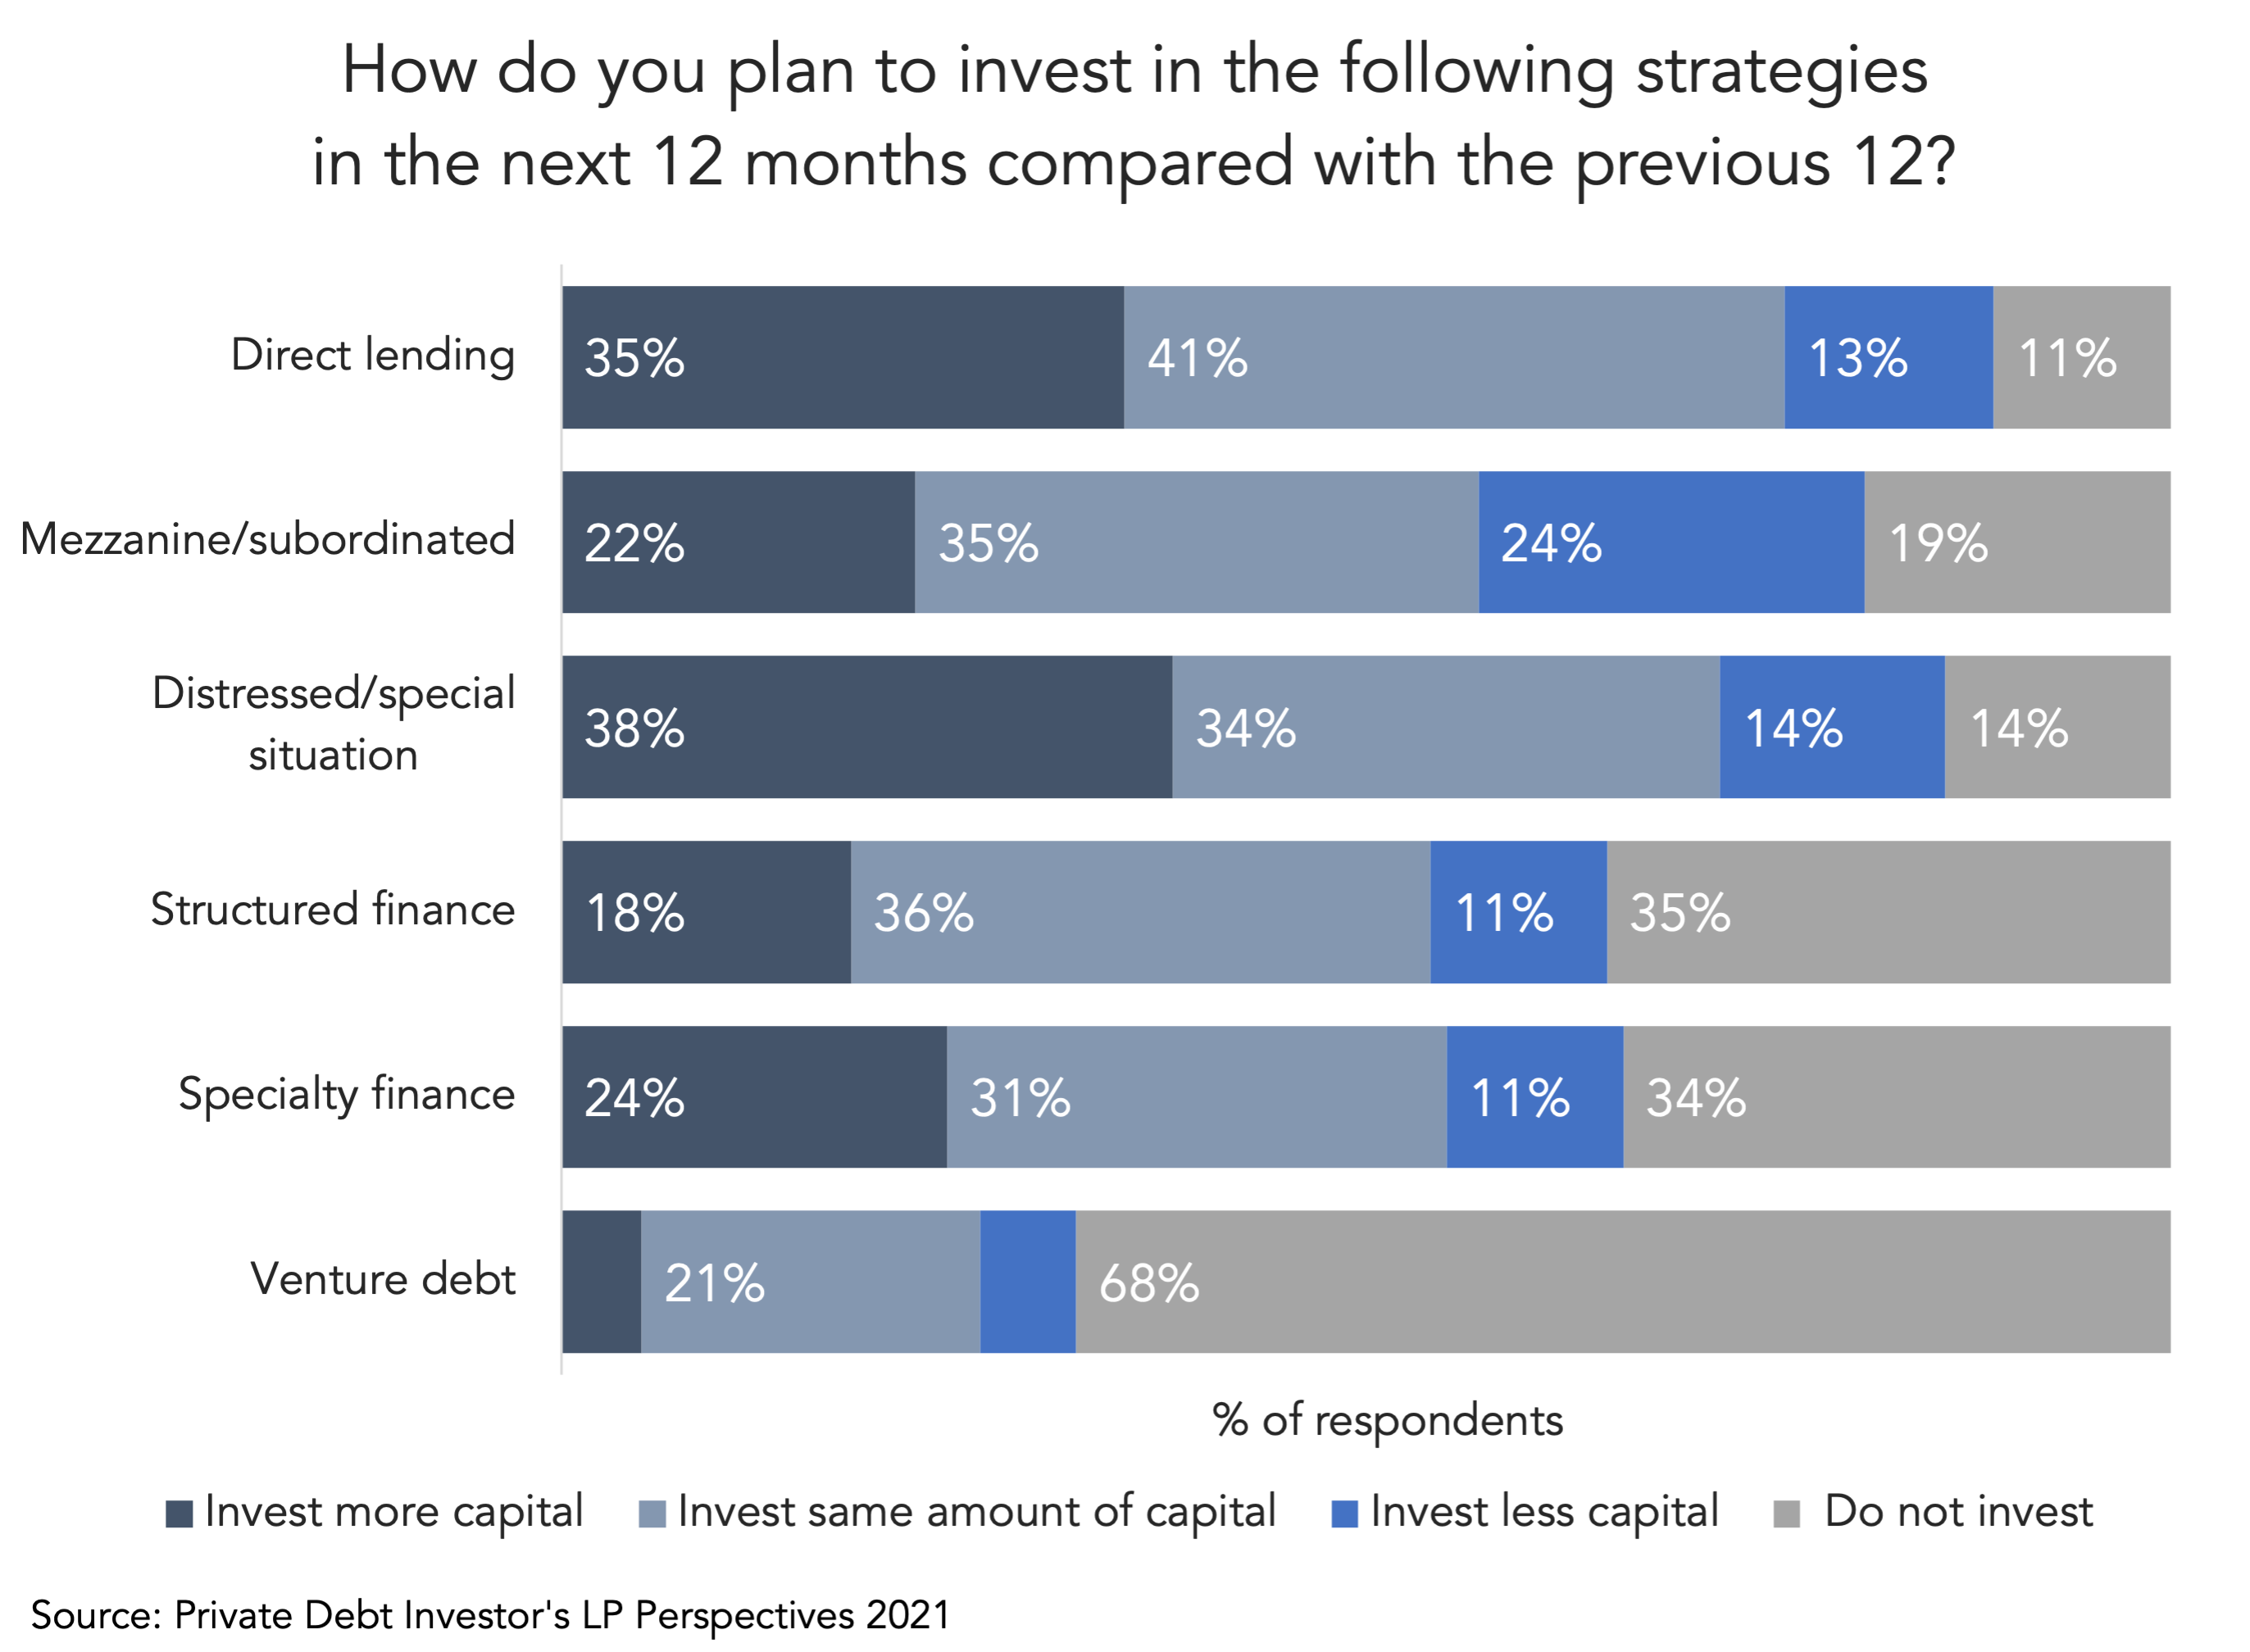
To maintain traditional spreads, investors are being encouraged to consider opportunistic strategies where private debt still maintains both a significant spread and differentiation. Areas reportedly attracting interest include structured credit used as a replacement for equity and stressed situations (including where you have a highly viable borrower constrained by a lack of access to capital).
“I think you’ll see a shift back from the plain vanilla strategies to more specialised strategies,” was a remark widely echoed. “These strategies have higher returns in all weathers and can even increase those returns during this part of the cycle.”
(Past performance is no guarantee of future results.)


Latest news

US leveraged loan issuance stalls in October amid secondary market rout
US leveraged loan issuance took a significant hit in October amid deteriorating secondary market conditions. Approximately $41.3b of loans have…