


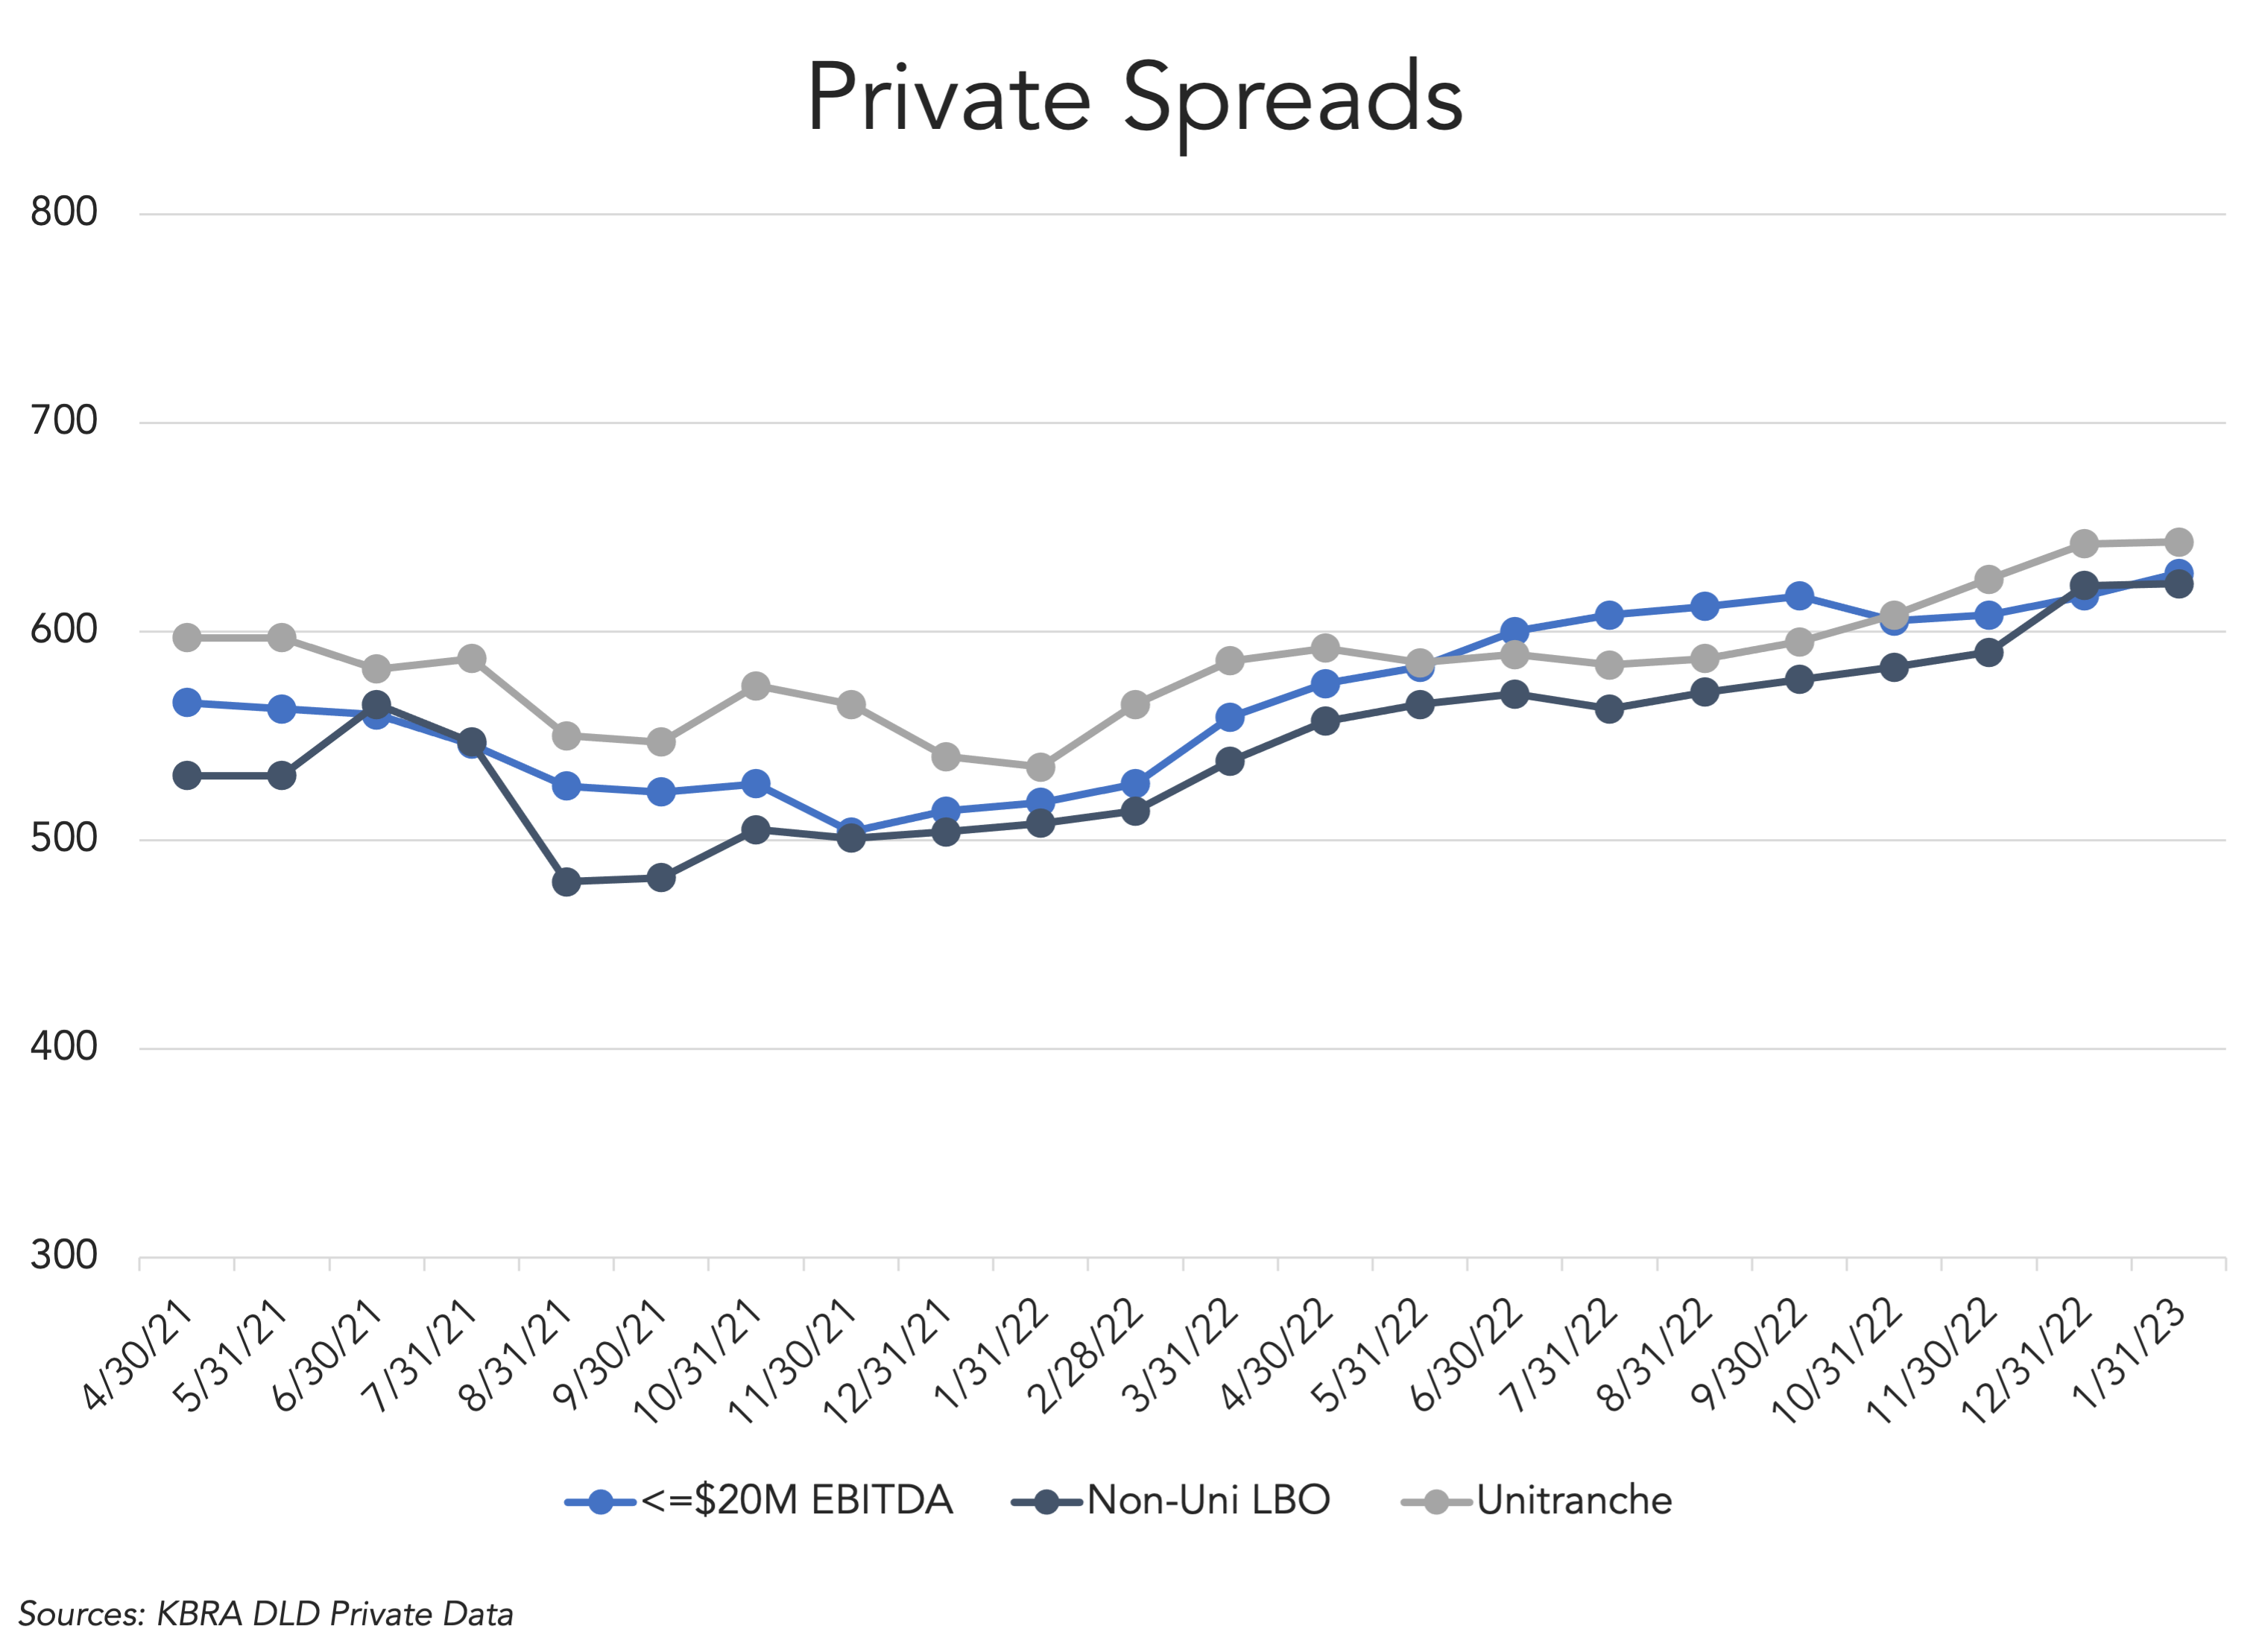
Unitranche yields in the KBRA DLD Private Data portfolio averaged 12% for the 90-day period ended Jan. 31, up from 6.6% a year ago. The current reading is the highest in our two-year, $270 billion library and potentially the highest since the GCC. The underlying spread averaged S+643 for the 90-day period ended Jan. 31, marking a sixth consecutive month of increases and resetting the two-year high from December’s S+642.
With yields at 12%, unitranche spreads have reached an inflection point, with many in the direct lending market believing the forward trajectory is flat to downward.
The are several factors at play:
1. The broadly syndicated market has improved since the end of January. Three dividend recaps tightened terms on strong demand from investors. That suggests a reopening, however little supply has emerged outside of opportunistic financings. Yields averaged 10.7% in January, according to LCD.
2. After dipping in December, the gap between single-B paper and unitranche loans widened in January, to 120 bps. That’s inside the 150 bps average over the last two years and far from the 230 bps recorded in June 2021 — the largest premium in our two-year data set — but sensitivity to premiums is more acute on skyrocketing base rates, particularly for jumbo M&A financings that have more financing options than middle-market borrowers.
3. The high yield market rebounded in January, with lower cost, unsecured debt averaging 8.5%, according to LCD, and several issues this month printed in the low 7% range.
4. Fundraising in 2022 still topped the five-year average, according to Preqin, and there’s plenty of capital needing investment. Underwriters ended last year on a selective tone, but a weak M&A pipeline has intensified competition for strong credits, between both nonbank lenders and banks, which increasingly are setting up private credit platforms to offer unitranche debt.
5. The M&A math for sponsors is tough at 12% debt, and the Fed has more rate hikes on the way.
Heading into 2023, the range was S+650-675 for new unitranche debt backing strong borrowers. Now, arrangers say new deals are starting at the tight end of the range and could be headed 25 bps lower by March.
Looking at just January transactions, the average unitranche spread in DLD’s Private Data portfolio was S+636, although nearly all of those credits backed add-on acquisitions. None funded new LBOs.




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
