


When the economy turns, infrastructure investment has often been seen as a safe harbour from tailwinds affecting other parts of the market. Infrastructure projects are typically long-term investments with government support, usually fulfilling essential needs which consumers cannot easily cut out of their budgets.
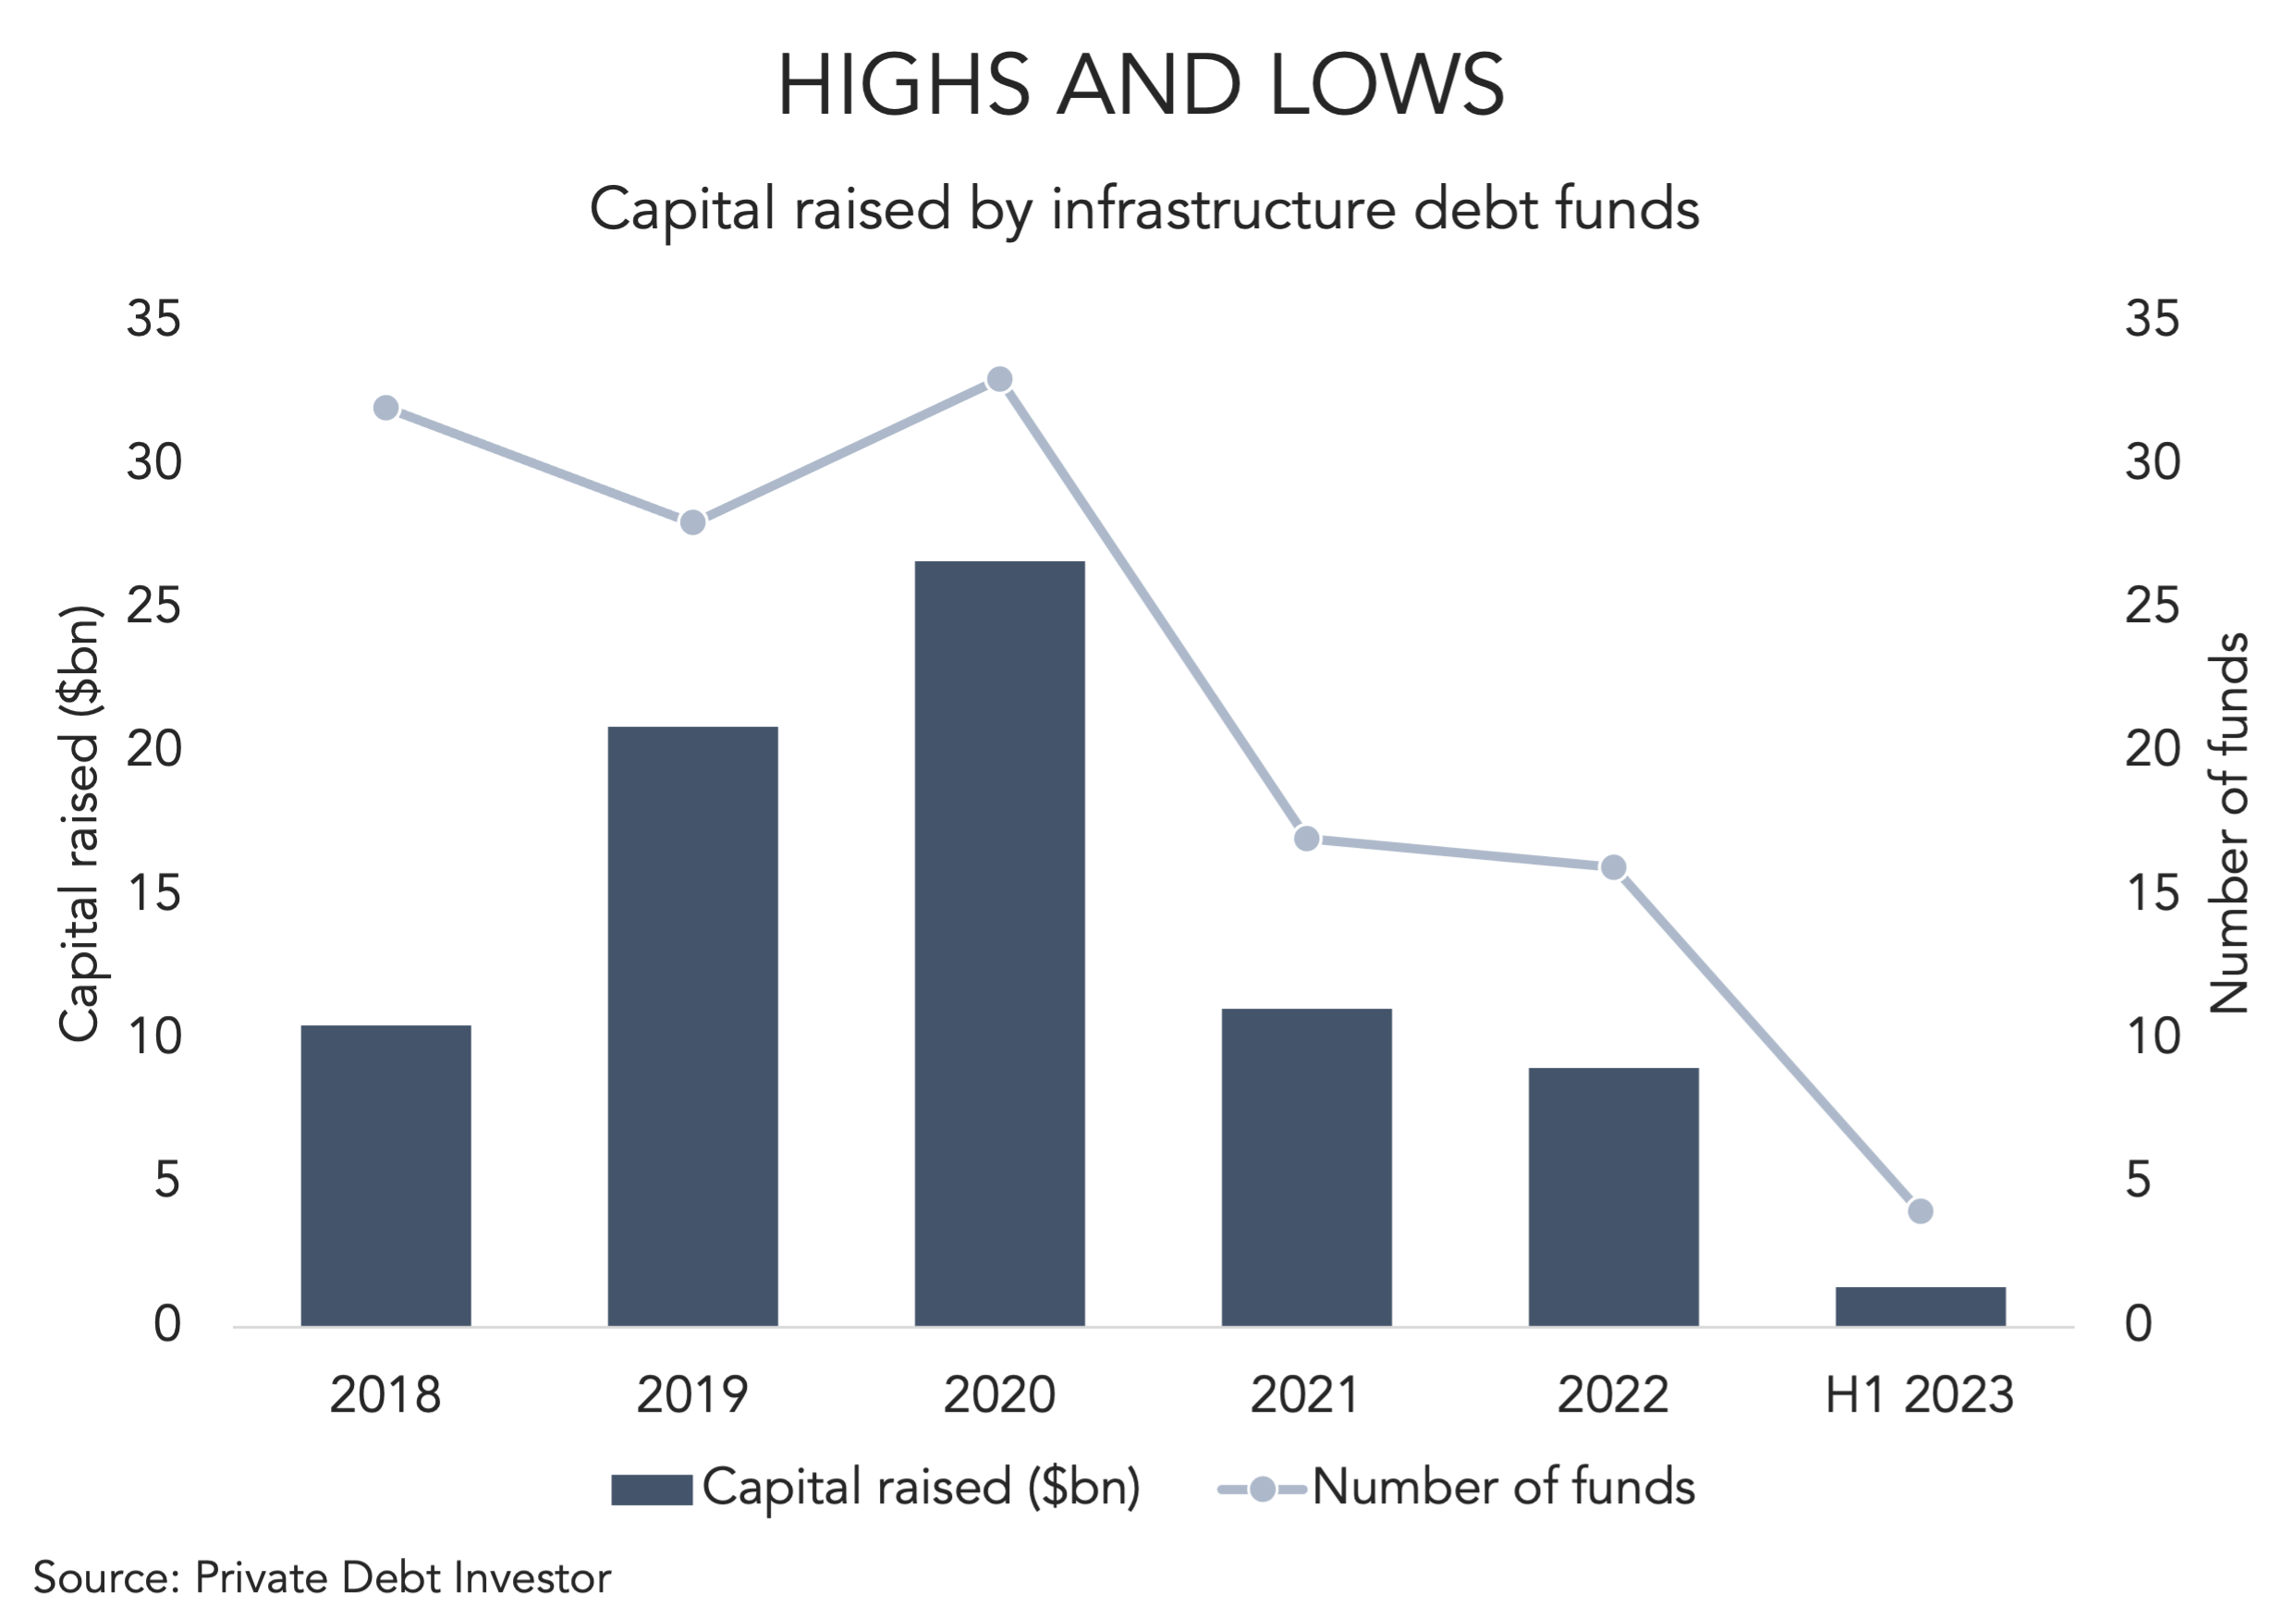
But investment in infrastructure debt cannot ignore what is going on in the wider market and issues such as depressed M&A activity and a sluggish fundraising market (see chart above) are taking their toll.
Moreover, refinancing risk is increasing across the board for private credit investments as both inflation and rapidly rising interest rates hit firms’ profitability and their ability to service their debt. For infrastructure lenders this is one area where strong underwriting discipline can help to prevent problems.
A particular issue for deals in the energy market today is the volatile price, which dropped considerably when the covid-19 pandemic broke out, then spiked when Russia invaded Ukraine in early 2022 but has since fallen again. This can make it difficult for investors to agree a fair price for assets and more complex for traditional debt providers to underwrite.
While there is less M&A activity today, a lot of borrowers are instead opting for capex facilities to grow their business organically but with non-dilutive capital at a time when equity values are low.
While infrastructure debt is far from immune to the wider issues facing private debt as a whole today, it is relatively insulated from many of these concerns simply by the fact the projects managers back are seen as critical services that cannot be given up. With many governments signed up to strict international treaties to reduce emissions, energy transition will continue to be a major investment theme in the decades ahead, and improving connectivity in the telecoms sector is also seen as essential for bolstering growth as the economy begins to recover and market conditions normalise.
For investors, infrastructure debt funds are offering good returns in light of interest rate increases but with low risk of default. However, issues are affecting LPs which could hamper their ability to increase their commitments to infra debt funds.
(Past performance is no guarantee of future results.)




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
