


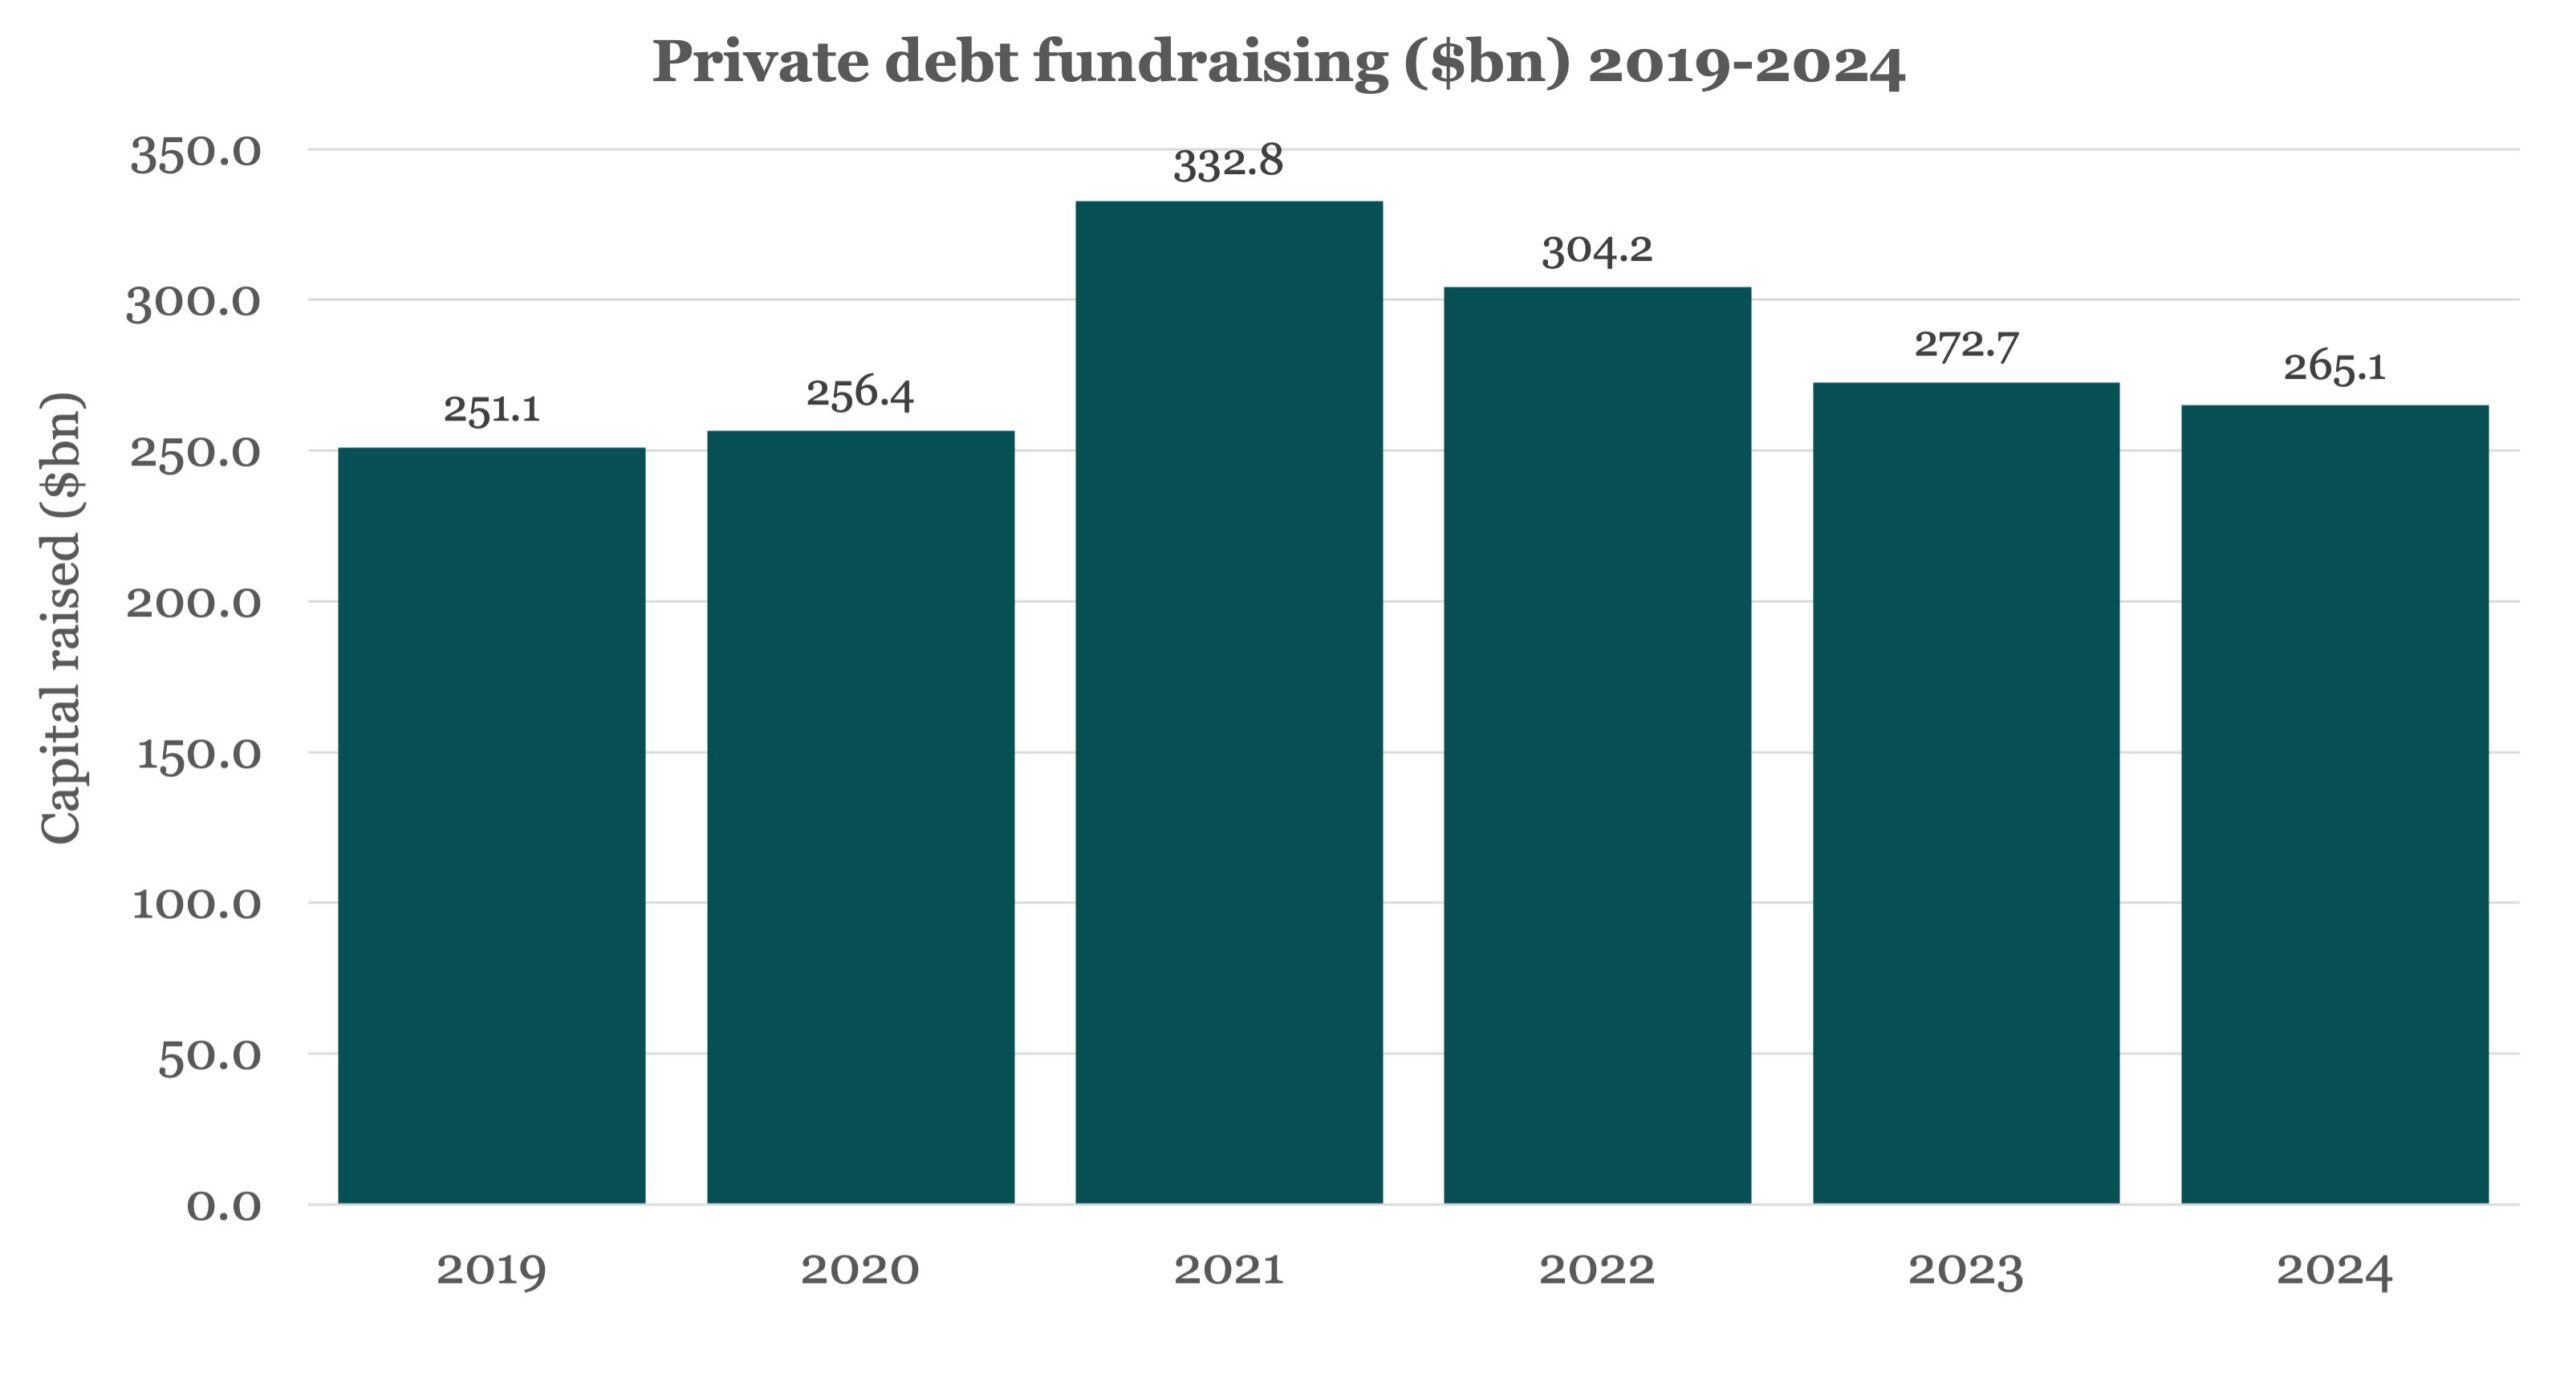
Global private debt fundraising fell slightly last year, having fallen each year since reaching a high of $332.8 billion in 2021, according to the latest Private Debt Investor data. The total of $265.1 billion was below 2023’s figure of $272.7 billion as the decline begins to slow.
In truth, while fundraising dipped, it has remained reasonably strong by historical standards and a new fundraising record could well be set in the coming years, particularly with funds in the market today targeting well over half a trillion dollars.
Perhaps the most remarkable trend seen in 2024 was the enormous surge in the popularity of senior debt funds, which accounted for a huge 60 percent of all capital raised, well above any previous year. This may be due to higher interest rates helping to boost the returns of relatively safe senior debt products.
This trend seems mostly to be at the expense of subordinated debt funds, which made up just 19 percent of funds raised.
The other dominant theme of 2024 was the growing prevalence of multi-billion-dollar funds.
Average fund size in 2024 approached the $1 billion mark at $984 million, up from $826 million in 2023 and almost double what it was five years ago. The trend towards larger funds looks set to continue with many funds in market now seeking at least $10 billion.
The recovery in fundraising has, however, been highly uneven. North America is a clear winner, with vehicles that target the region accounting for more than half of all funds raised.
By contrast, Europe has continued to struggle as a variety of economic and geopolitical headwinds dampen demand for investment in that continent, and just $41.7 billion was raised during the year.
Corporate credit has long formed the backbone of the private debt space, but has been of growing importance since the covid-19 crisis, as other sectors – particularly real estate – have struggled to attract investment due to tougher market conditions.
In 2024, 83 percent of capital raised was for corporate credit, the highest proportion recorded, but that dominance will likely ebb in the coming years as conditions for infrastructure and real estate debt improve.




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
