


As par-plus loans begin to drift lower, new repricing candidates prove no easier to find

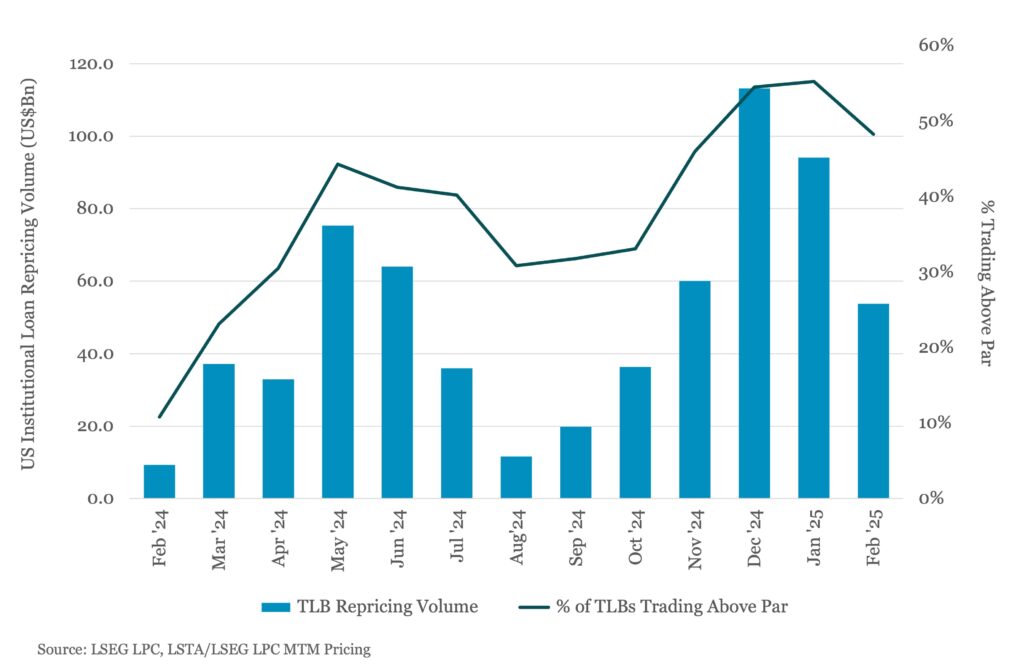
Regardless of where one points the blame – a slight downshift in technicals, cracks in broader market conditions, or the self-fulfilling dynamic that the vast majority of issuers that could reprice have already done so – the share of institutional loans trading above par has begun to move noticeably lower. Par-plus loans now account for 48% of the secondary market, still a commendable share although trending below 50% for the first time since November. And term loan B repricings have begun to slow in parallel, with February issuance trending nearly 50% lower since January, at US$54bn versus US$94bn, respectively. There’s still one week left in February for a final push, although one can’t help but ask: Is the Great Repricing Wave beginning to finally turn? Or simply taking a much needed breather? Two related themes seem fairly certain: (1) Straight refinancings are beginning to take prominence over mark-to-market repricings, as repricings now account for nearly 50% of total institutional loan refinancings versus about 75% in January; (2) Investors are still holding the floor for institutional loan pricing at S+175bp, at least for now.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…