


Download PitchBook’s Report here.
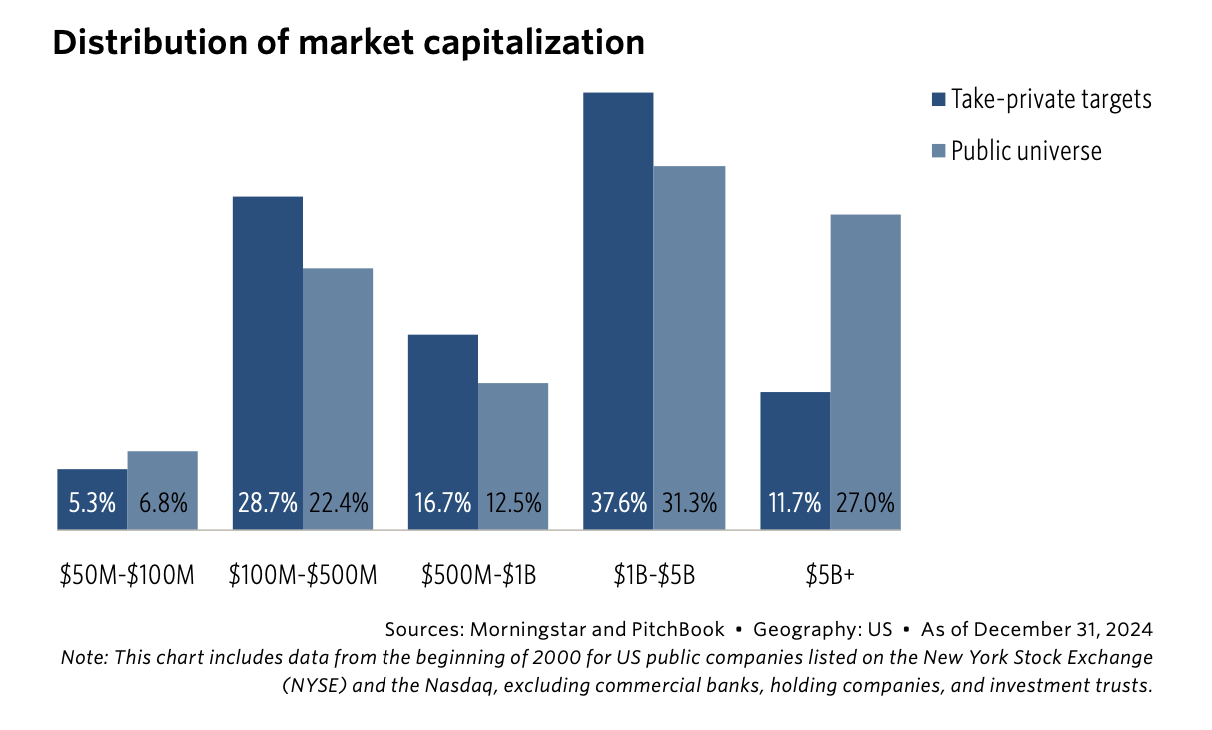
Since the inception of the buyout strategy in the 1980s, buyout managers have maintained a core playbook: At a reasonable price, invest in relatively small, underperforming companies that still generate enough free cash flow (FCF) to service an increased debt burden. Evidence from take-private transactions over the past 30 years confirms this playbook is being used. We found that take-private targets are more likely to be relatively cheap with respect to a variety of equity price ratios despite relatively neutral EBITDA and cash flow margins. Underperformance is apparent in both the trailing one-year stock return of these take-private targets as well as their operating efficiency in terms of revenue generated per employee.
(Past performance is no guarantee of future results.)


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
