


Q1 2025 saw a reversal in fortunes, with direct lending making a slow start to the year.
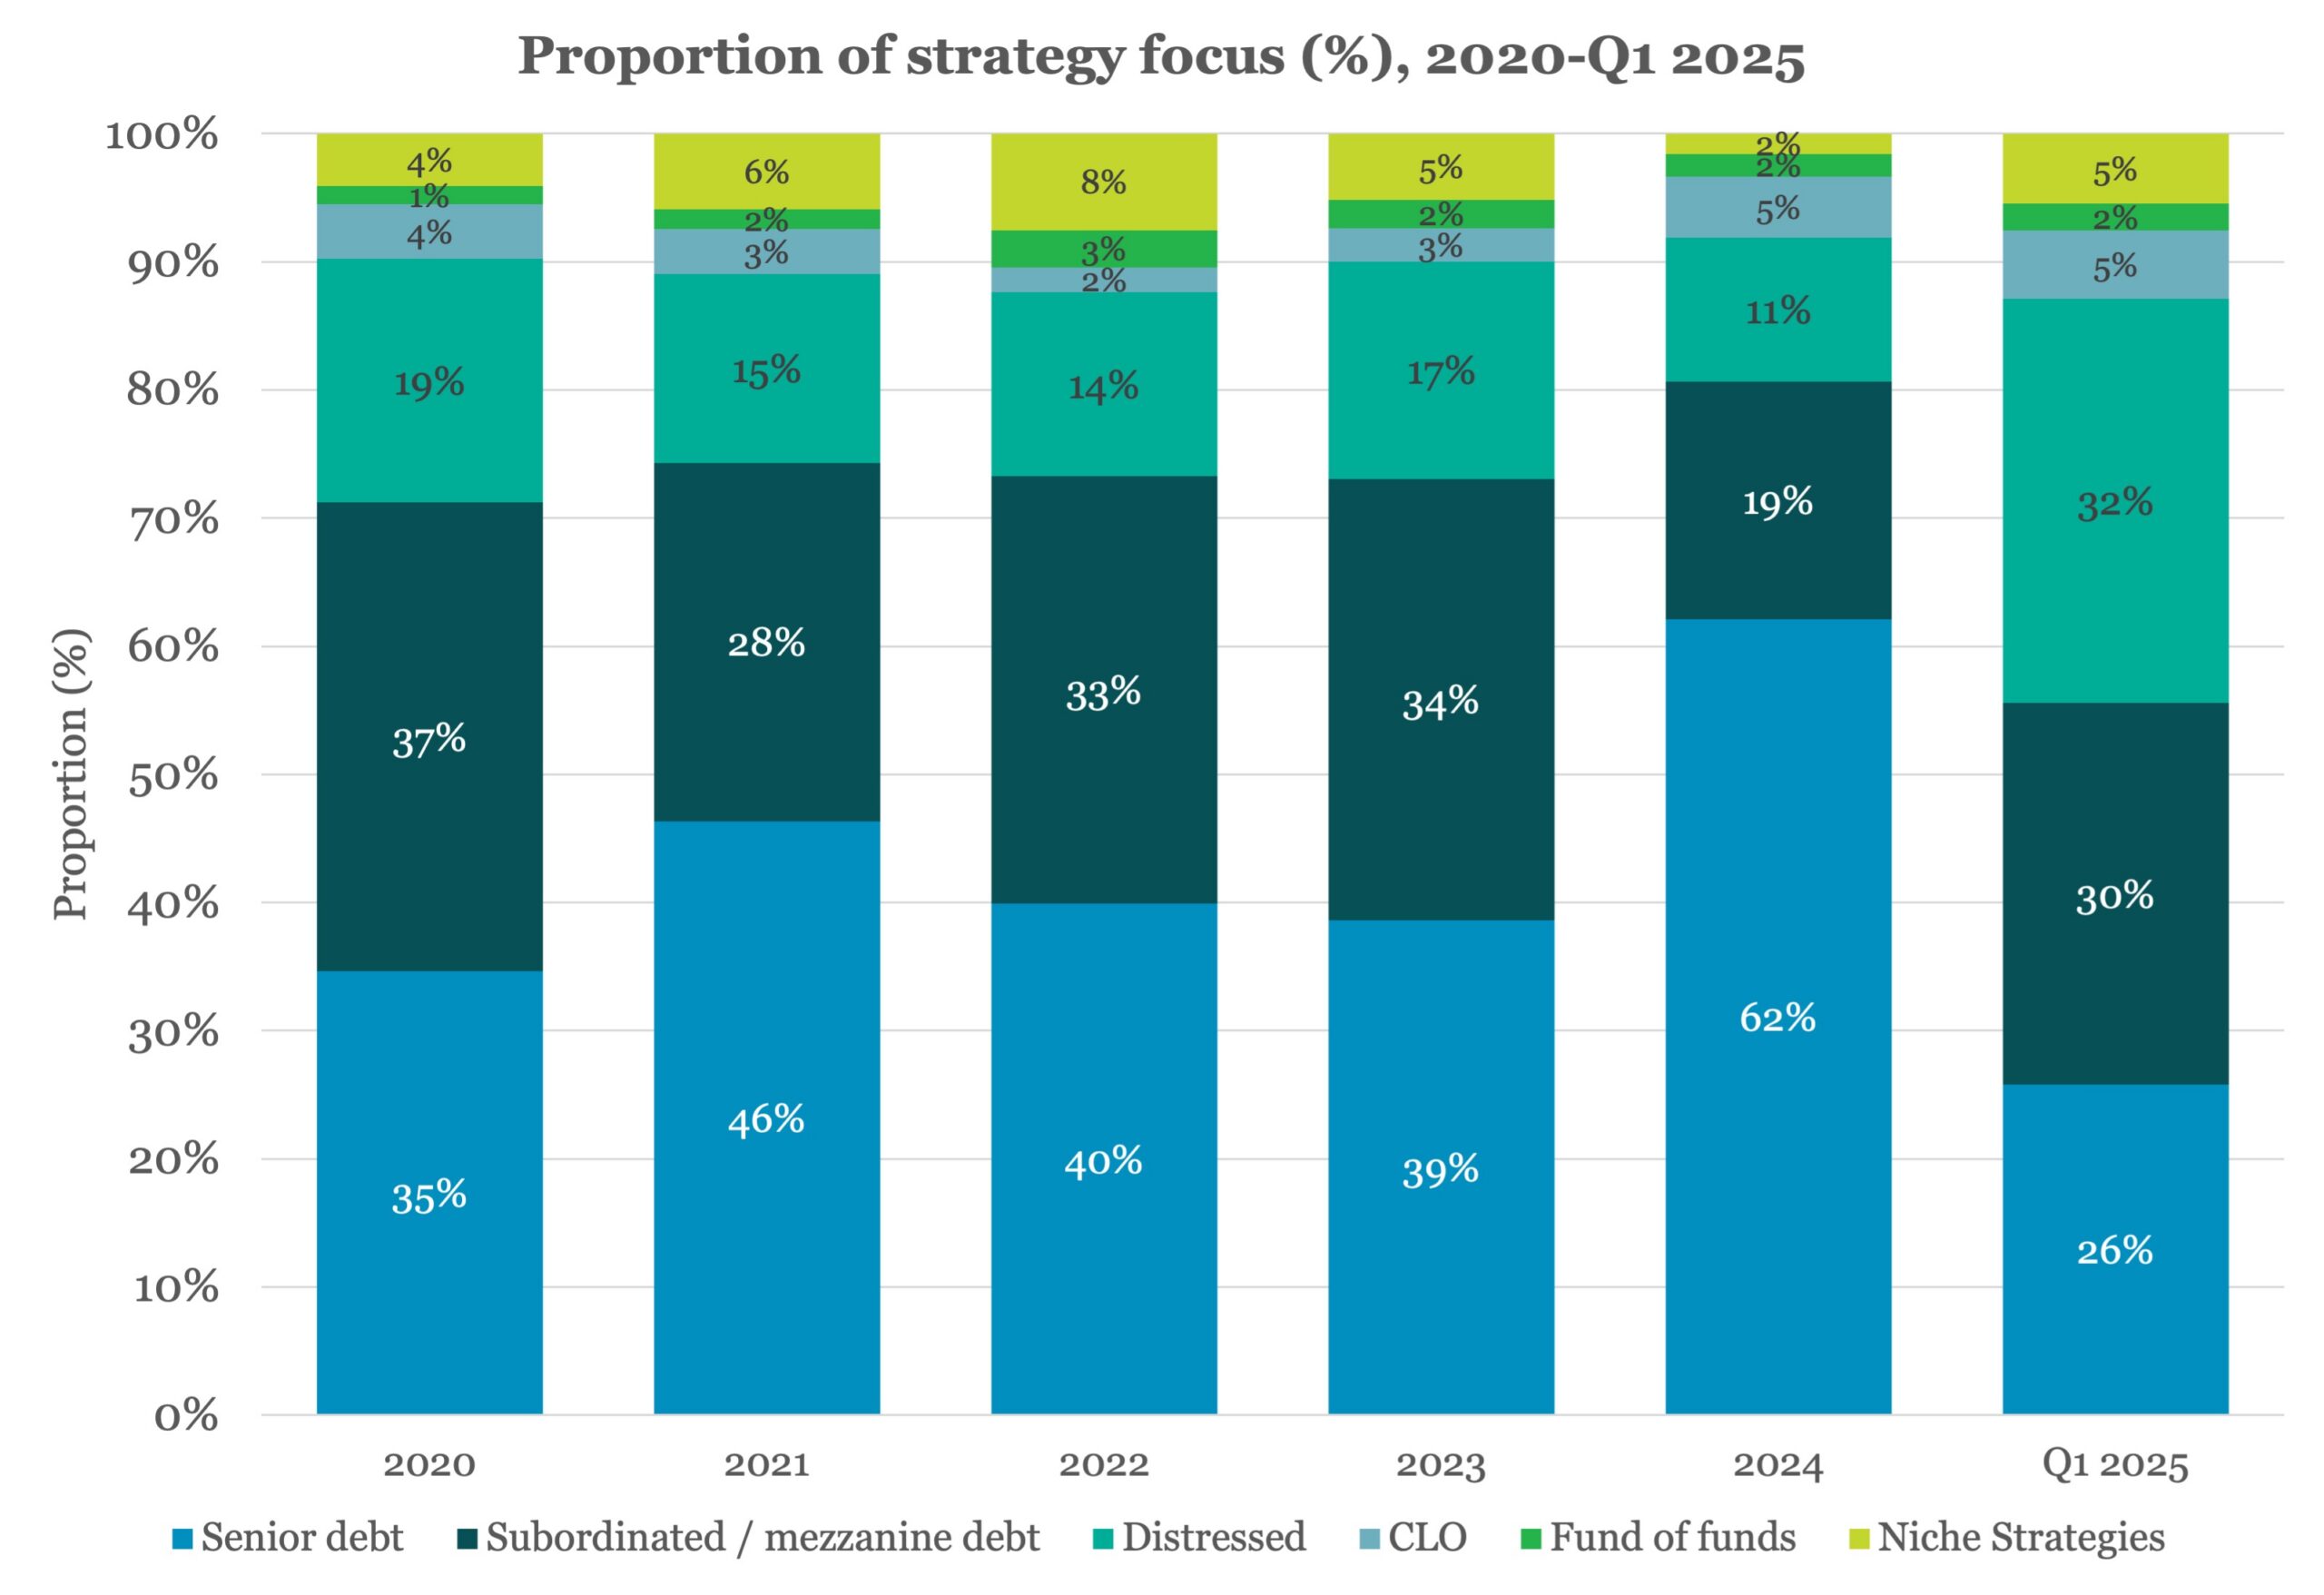
In recent years it’s almost felt as if direct lending has been the only game in town. Whenever Private Debt Investor collects global fundraising data, we always break it down by target strategy. Over the years, we’ve found direct lending to be the most favoured strategy, typically with around 40-45 percent of the fundraising total. Last year, its share soared to a remarkable 62 percent.
In the first quarter of this year, distressed debt – which has accounted for less than 20 percent of the total in every year since 2020 – turned the tables, with market share of 32 percent. Direct lending didn’t even claim the runner-up spot, with subordinated/mezzanine debt claiming that accolade with 30 percent and direct lending trailing on 26 percent.
Of course, no one should draw too many conclusions from just three months’ data. Moreover, the period included a distressed debt mega-fund as Oaktree Capital Management closed its latest vehicle on $16 billion. It seems very likely that the market shares will shift over the coming quarters – not least, there are always some large-sized direct lending funds in the market and not far away from final closes.
Nonetheless, with the global tariff situation having exacerbated an already volatile macroeconomic and geopolitical environment – and with talk of possible recession hanging in the air – it’s no surprise that investors are taking a closer look at strategies which thrive on complexity and outright difficulty.
Despite strong economic growth, labour market strength, and tight credit spreads, higher-for-longer interest rates will strain credit quality for a meaningful portion of US issuers, a report by Moody’s Asset Management Research recently noted.
It found that the average risk of default, not the default rate itself, was 9.2 percent at the end of 2024. It says in the report that default rates will struggle to improve, and that US corporate credit risk has not shown a clear peak. More distressed restructurings, as opposed to full-on defaults, are expected.
For those focused on distress, these are interesting times.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…