



Download PitchBook’s Report here.
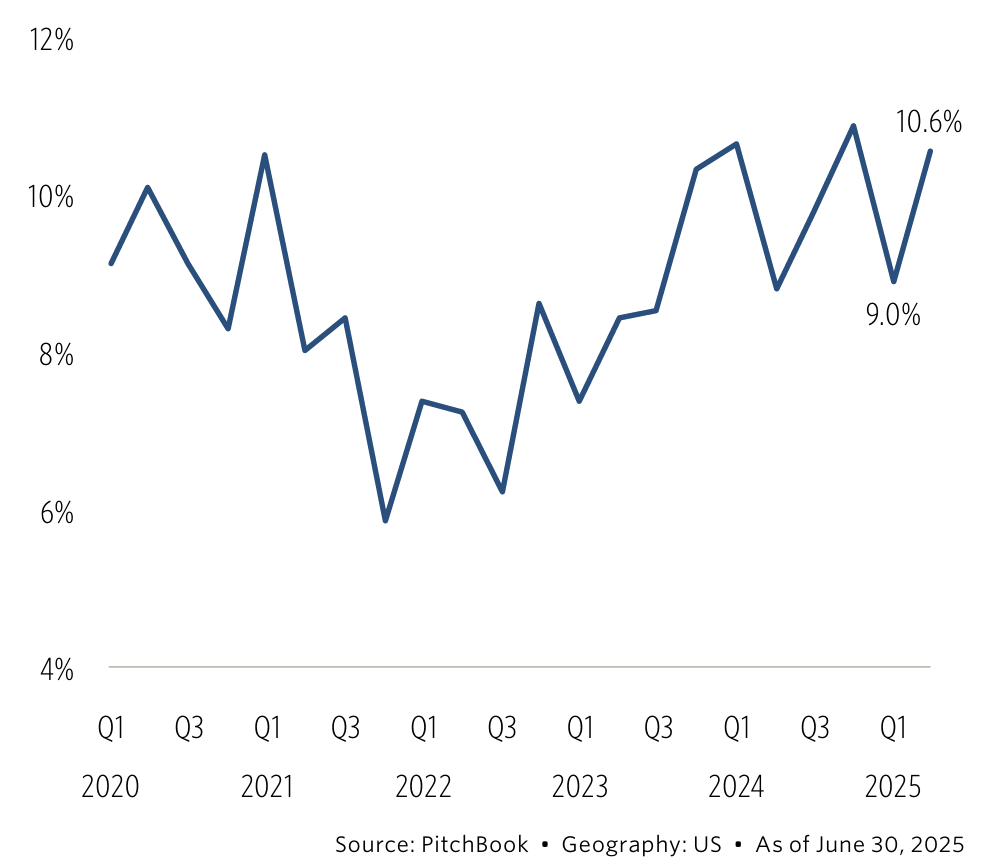
Carve-out transactions are running at 10.6% of all buyout deals in 2025, which is comfortably above the five-year average of 8.7% and last year’s 10.1%. Still, we are hearing that sellers are opting to wait out the current volatility caused by tariff-driven supply chain gyrations rather than divest into volatility. Examples include companies that are unable to economically provision process inputs or finished goods, and are waiting for clarity on US tariff policy and broader trading relationships before green-lighting spinouts—which could set the stage for a stronger second half as public-equity indexes hover near their recent highs and valuation confidence returns.
(Past performance is no guarantee of future results.)




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
