


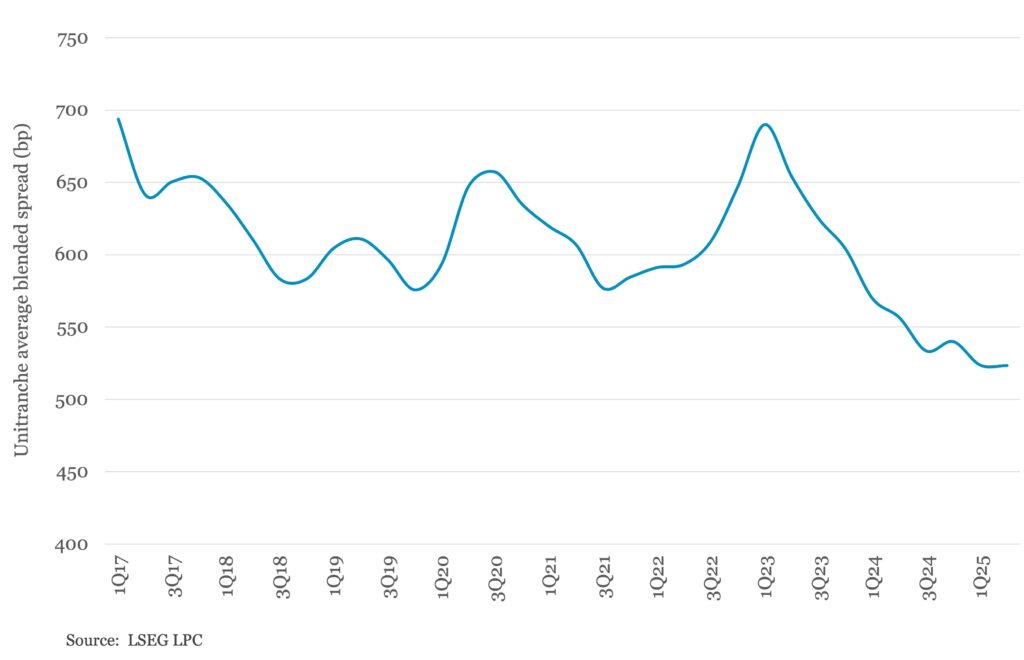
The most recent quarter was marked by intense competition among direct lenders and lower than hope for deal flow. In turn, spreads continued to hover around recent lows despite sporadic wider market volatility. Average unitranche blended spreads averaged 523bp in 2Q25, flat q-o-q. Just under half (48%) of unitranche deals had a blended spread of 500bp or lower in 2Q25. Year-over-year, the unitranche blended spread was down 33bp, or 6%, from 2Q24. Looking across market segments, the average spread on unitranches for large corporate issuers tightened 16bp to 510bp in 2Q25. In comparison, middle market unitranche spreads increased by 7bp quarter over quarter to 529bp. At the beginning of this quarter, many direct lenders in LPC’s Middle Market Outlook Survey pointed to low minimum thresholds for unitranche transactions heading into 3Q25, with 38% of respondents saying their minimum unitranche spread is 475bp or below, down slightly from the 44% who said this in the prior quarter, but still well above the 18% of survey participants who pointed to this threshold a year-ago.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…