

U.S. Private Credit: Sizing Up Defaults

FR icon
Content hub / Article / Fitch Ratings / U.S. Private Credit: Sizing Up Defaults

Click here to download report.

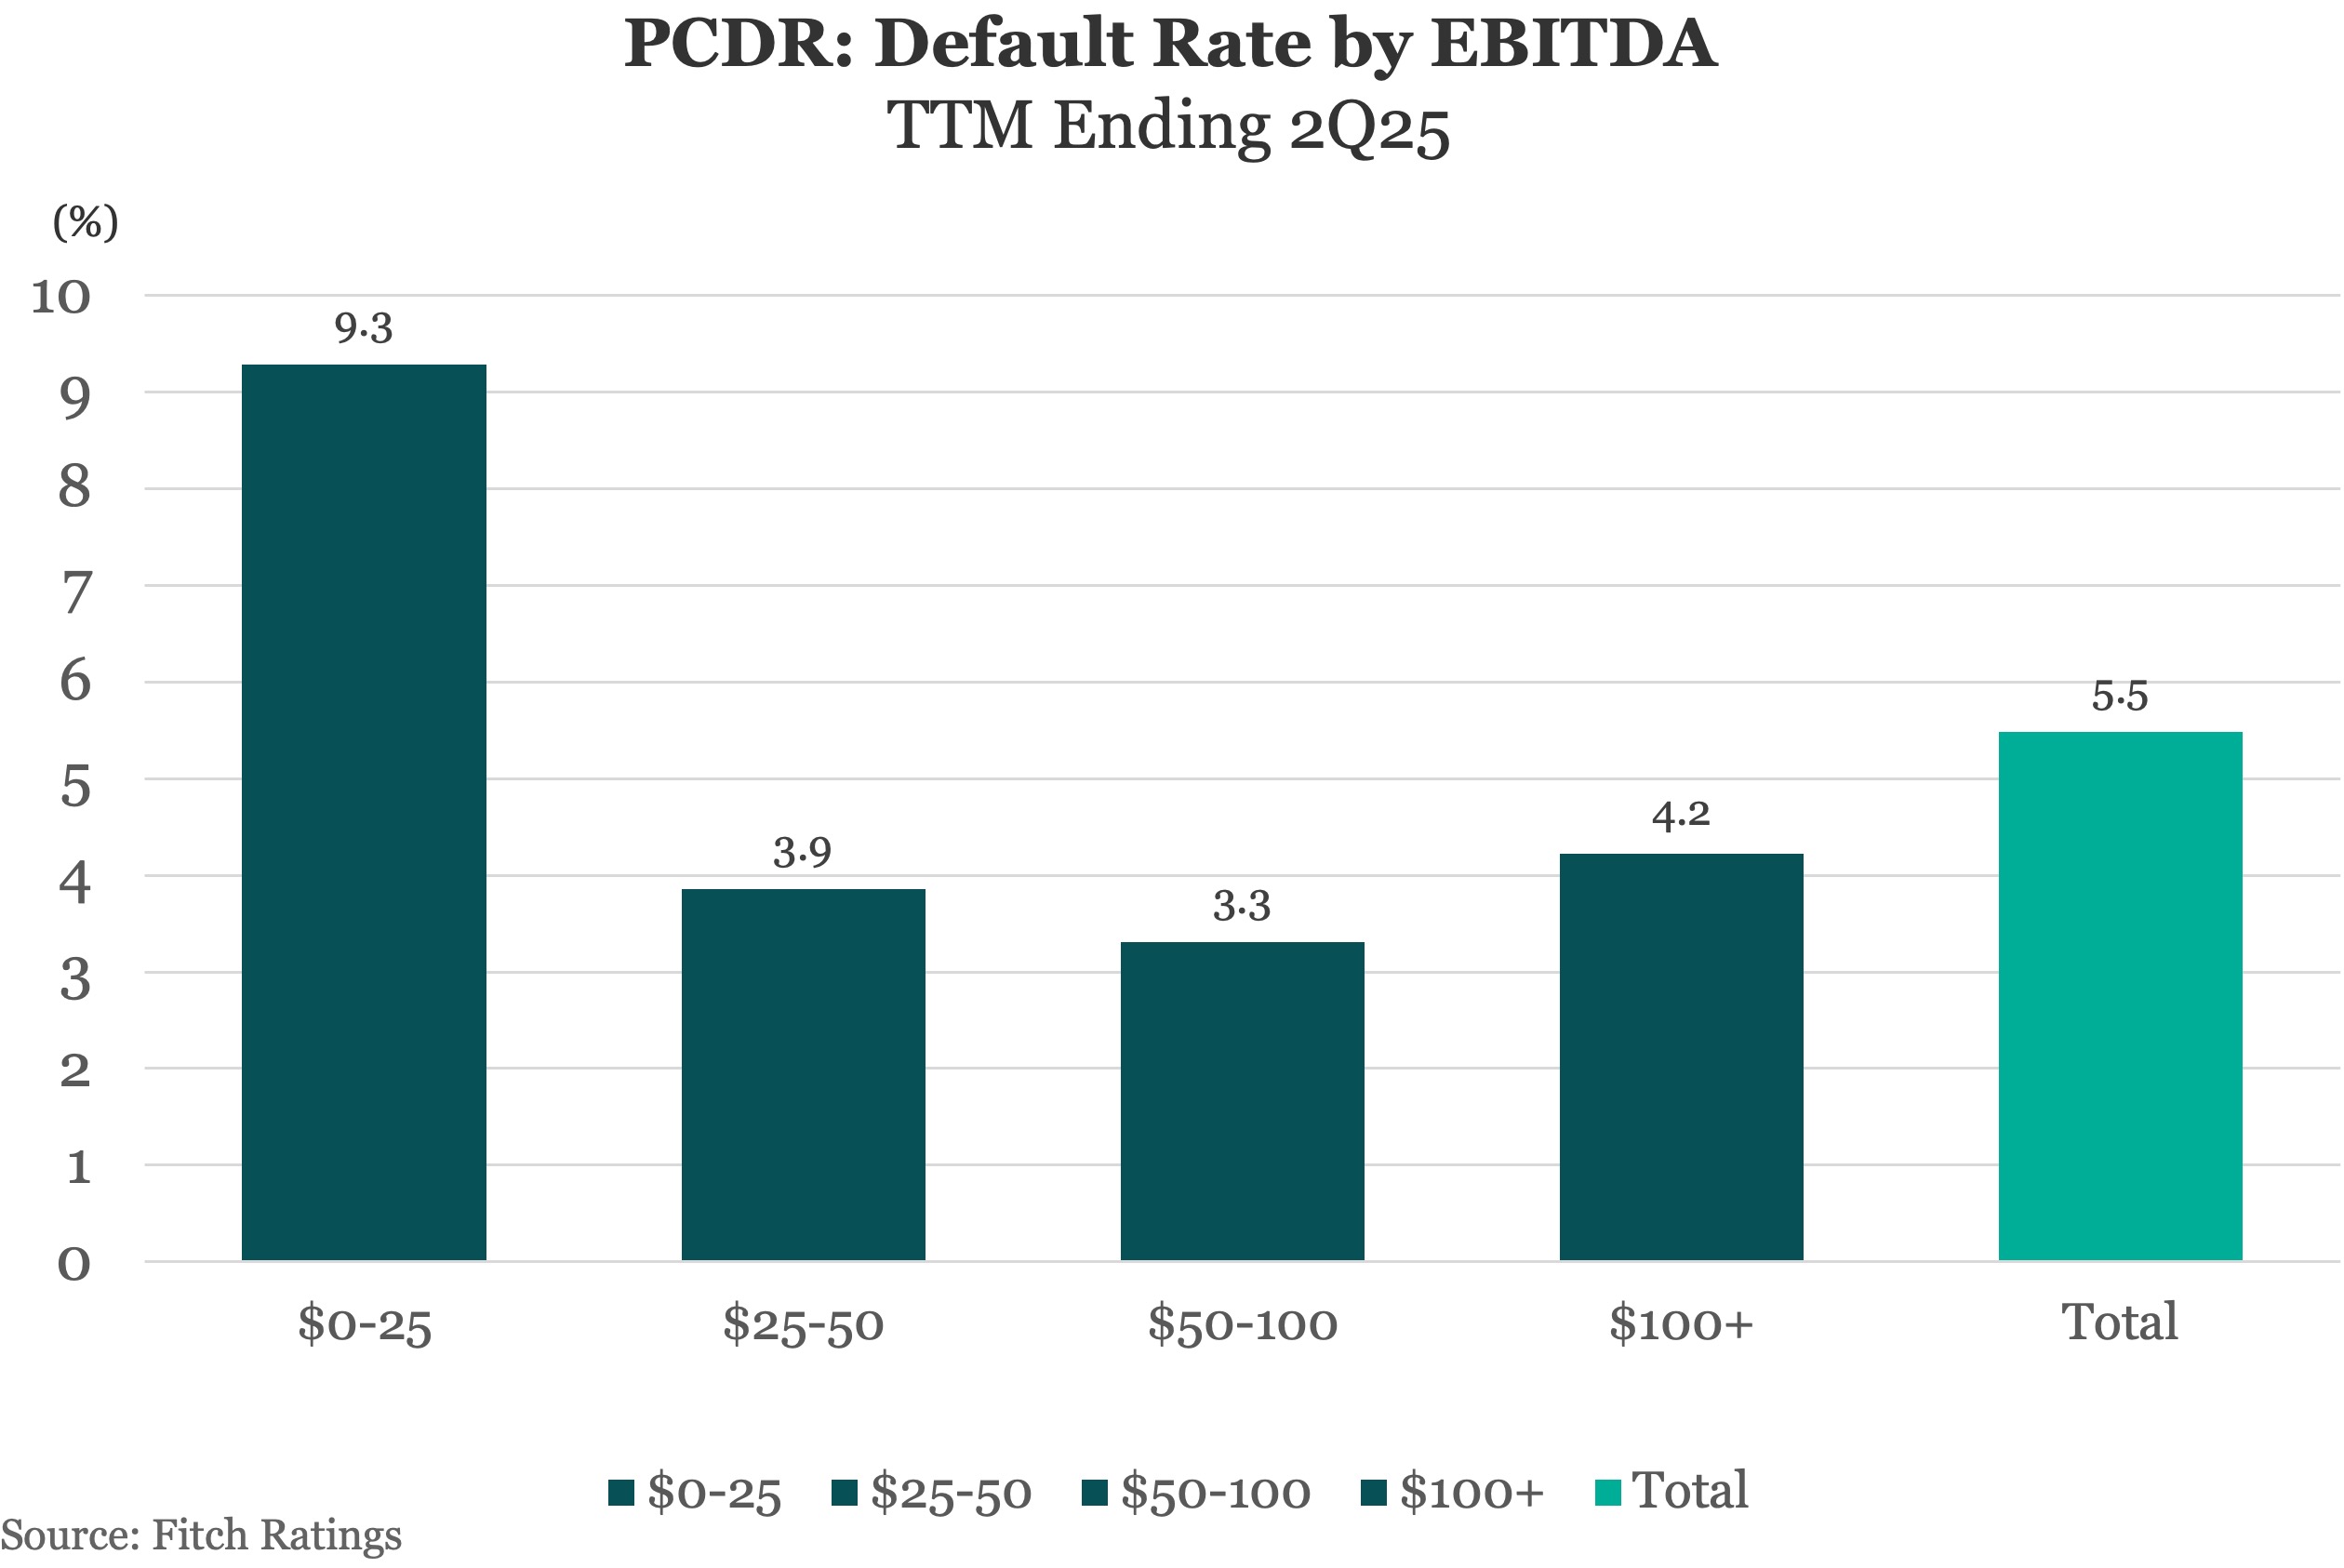
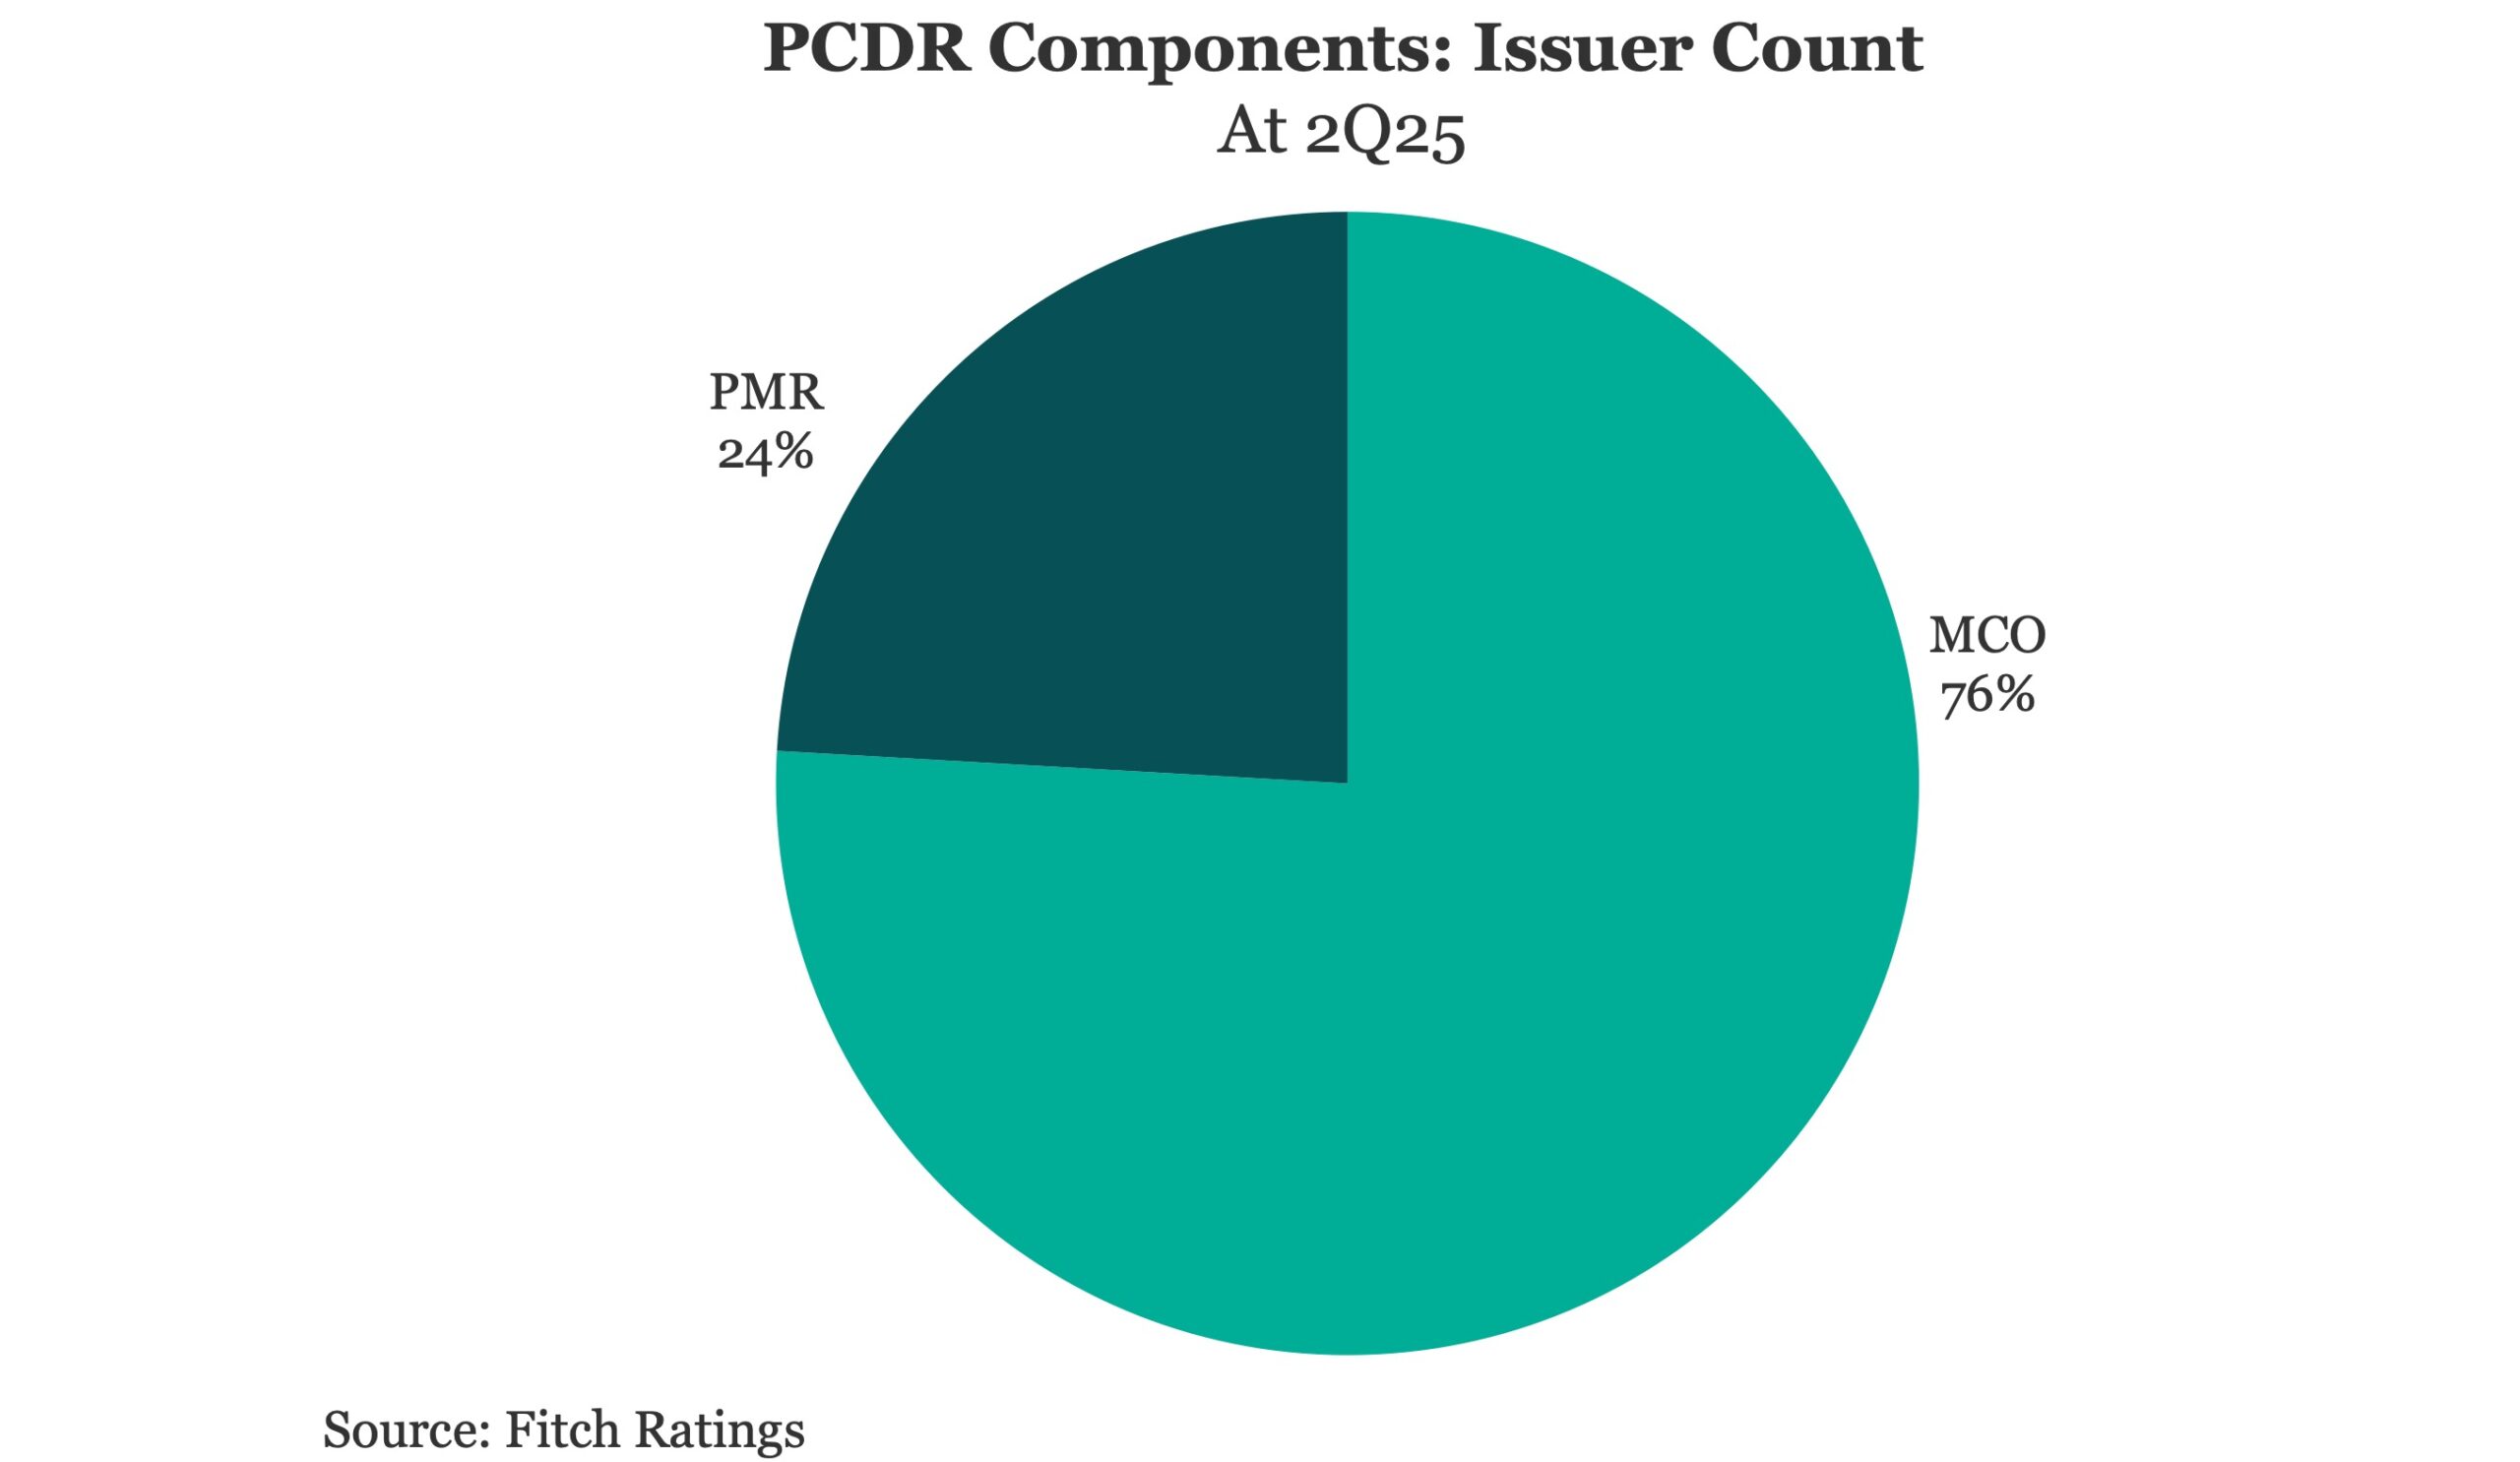
Small issuers generating less than $25 million EBITDA defaulted at more than double the rate of larger issuers in Fitch Ratings’ Private Credit Default Rate (PCDR) universe during the trailing twelve months (TTM) to 2Q25. This report examines private credit defaulters by EBITDA size, compares default rates across the two component Model-based Credit Opinion (MCO) and Privately Monitored Ratings (PMR) portfolios, and details default reasons.


2026 Private Credit Investor Survey

Share your perspective

2026 Private Credit Investor Survey

Institutional investors, RIAs and financial advisors - we want to hear from you. Take this two-minute anonymous survey and receive the results report.
Take the survey
LSEG LPC Large Corporate Leveraged & Middle Market Loans Conference

Thursday October 29, 2026 | New York City

LSEG LPC Large Corporate Leveraged & Middle Market Loans Conference

Join 250 delegates - including investors, borrowers, bankers and legal advisors - for a day filled with insightful discussions on the most important issues facing the loan market.
Learn more
PitchBook's H1 2026 Global Private Debt Report

Report

PitchBook's H1 2026 Global Private Debt Report

Strong fundamentals, but uncertainty remains.
Download

Latest news

    High-Yield Bond Statistics

    Read More

    Information technology topped nonaccruals on a cost basis

    Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

    Read More

    US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges

    Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.

    Read More


