


Our data for private credit capital raising by strategy shows investors once again diversifying their commitments rather than concentrating them.
At first glance, it appears that last year saw investors significantly re-align their strategic priorities when it comes to private credit. But a closer examination of the PDI full-year fundraising figures reveals that it was in fact more of a reversion to the historic norm.
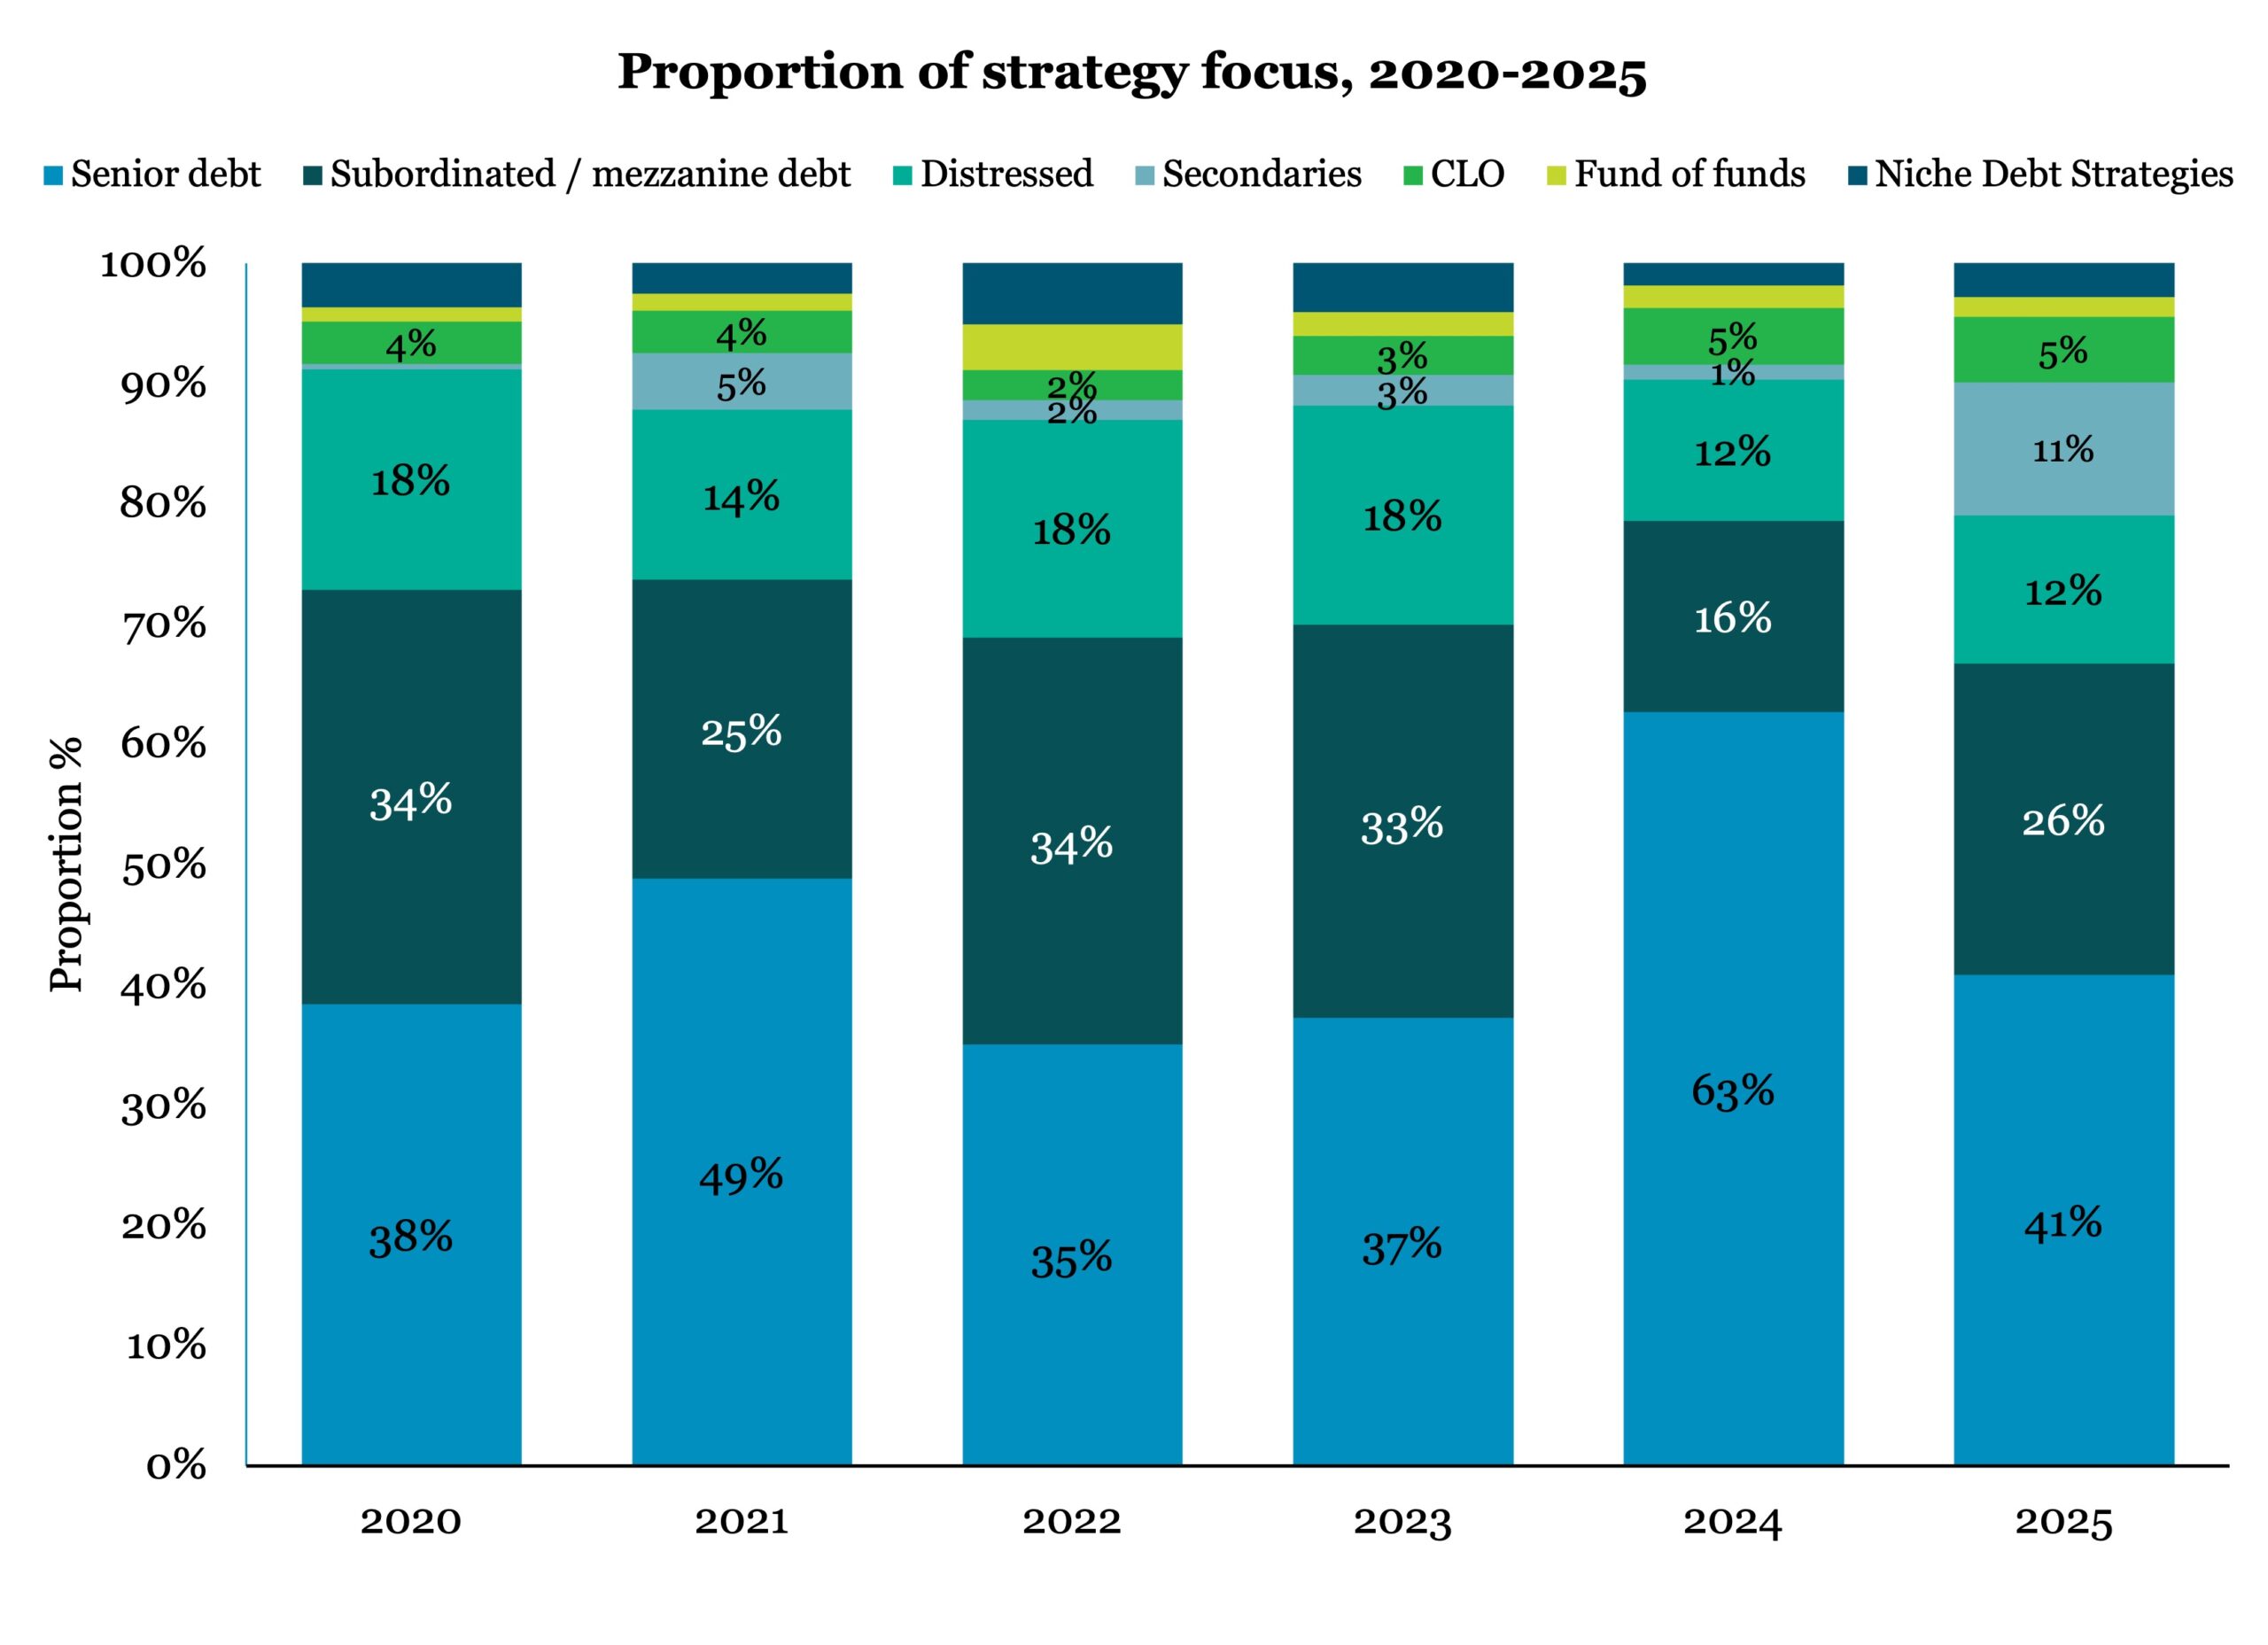
2024 was, in retrospect, an outlier. Investors flocked to senior debt strategies in numbers never seen before – with the safest part of the capital stack accounting for 63 percent of all global private credit fundraising during the year.
Looking back over the period 2020 to 2023, the average proportion raised by senior debt strategies was 39.8 percent of the total – much more in line with the 41 percent recorded last year.
What senior debt’s dominance meant last year was that other strategies were squeezed in terms of capital raised. Again, at first glance, it looks as if 2025 saw a striking recovery for subordinated and mezzanine debt – with 26 percent of the total versus only 16 percent the year prior.
But if we examine the same historical context, we find that the average raised by subordinated and mezzanine strategies between 2020 and 2023 was 31.5 percent. Thus, the strategy is arguably still raising rather less than we might expect rather than significantly more.
But while subordinated and mezzanine debt fundraising got back to normal levels last year, the same could not be said for distressed debt – which stayed at the same suppressed level of 12 percent that it recorded in 2024. This compares with a 2020 to 2023 average of 17 percent.
While 2024 was the outlier year, 2025 had one specific outlier of its own – and that was secondaries. Having accounted for between 0-5 percent of the fundraising total each year between 2020 to 2024, it raced to 11 percent of the total last year amid a handful of multi-billion secondaries fundraises.


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
