US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
Click here to learn more.
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says. Distressed debt exchanges (DDEs) comprised 79% of observed defaults held by rated CLOs year to date, putting 2026 on track for the highest annual share since Fitch began tracking the data. This exceeds the previous high of 69% in 2024.
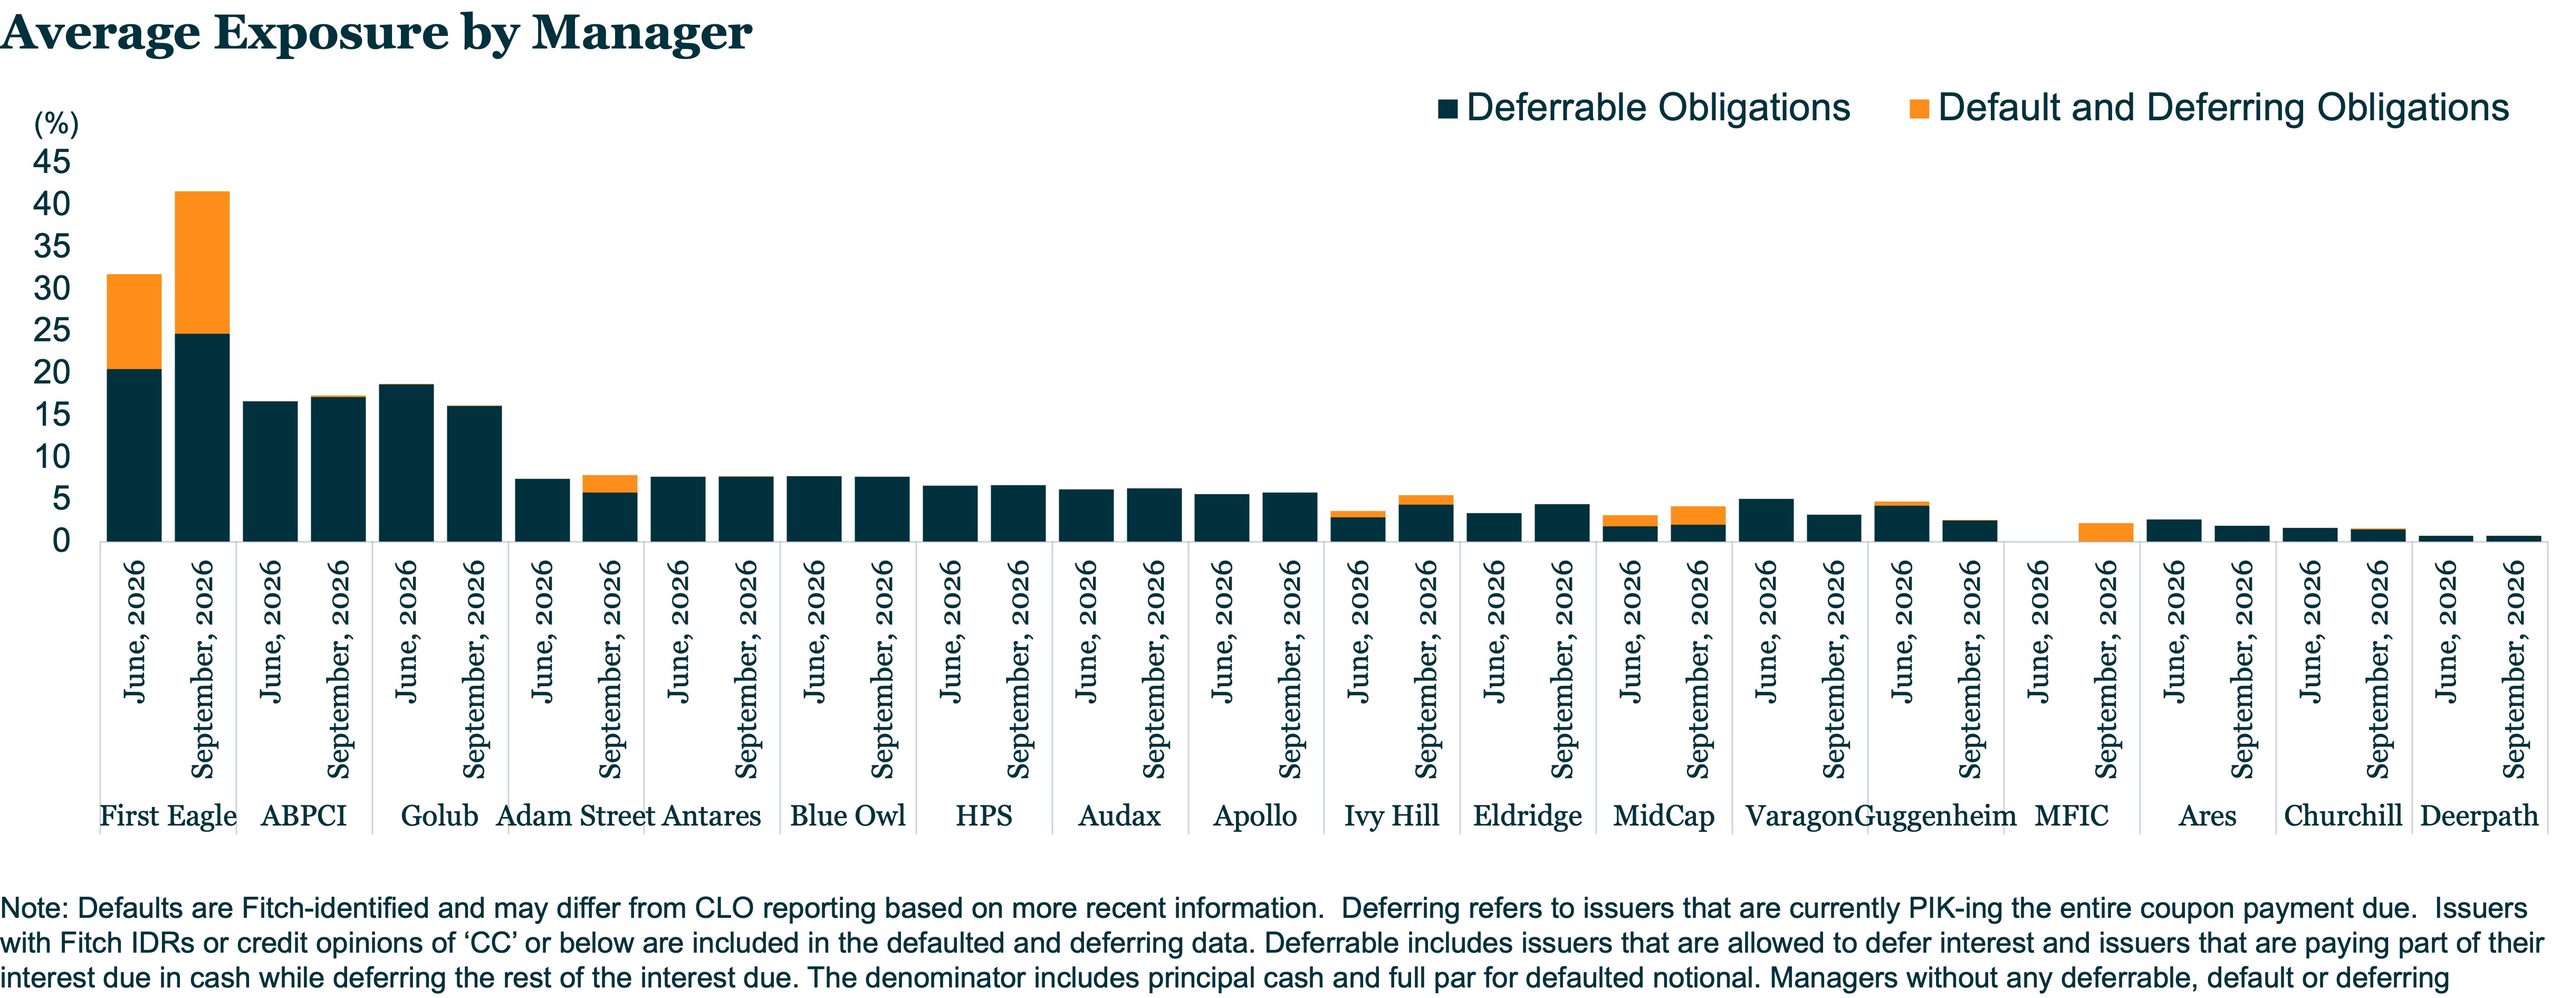
Fitch recorded six obligor default events in U.S. BSL CLOs in September, all of which were DDEs except for Leslie’s Poolmart which had filed for Chapter 11 on Sept. 30 and was held in 4% of Fitch-rated CLOs. A total of 16 defaults were recorded in 3Q26, down slightly from 20 in 2Q26 and unchanged from 3Q25. Average default exposure for U.S. BSL CLOs increased slightly to 0.3% from 0.1% in the previous month.



Latest news


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.