


Click here to learn more.
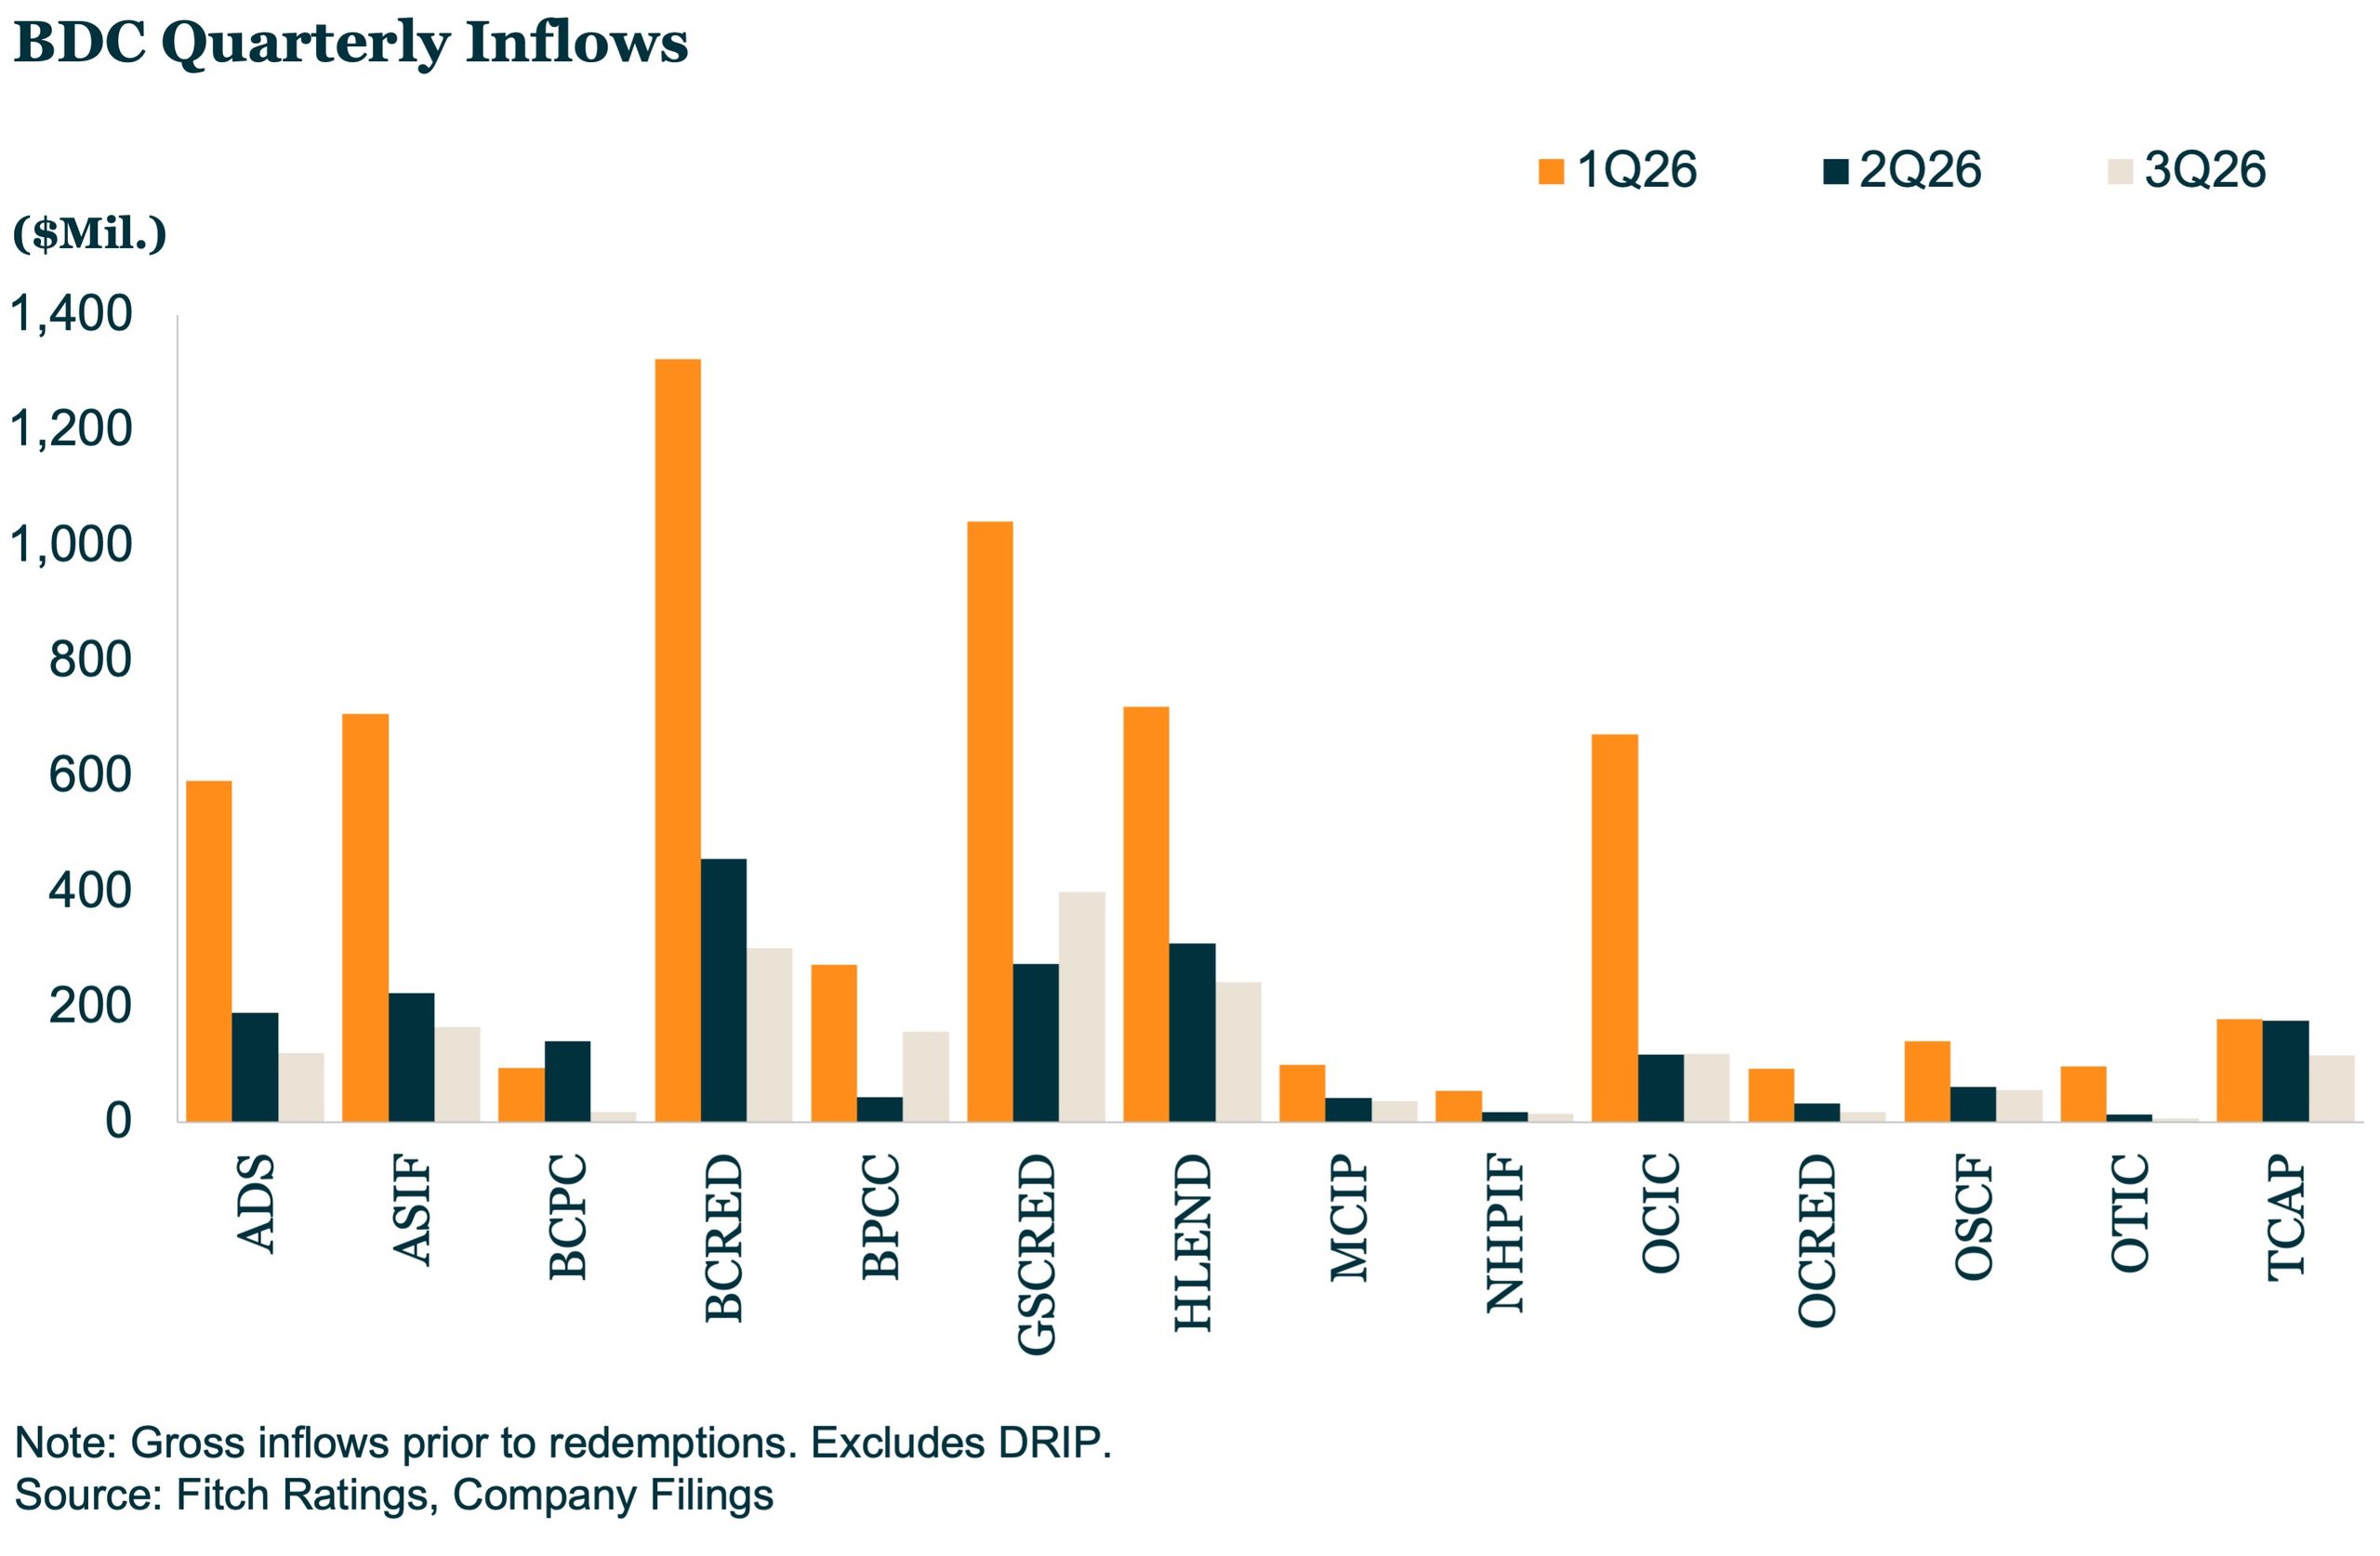
Redemption requests declined quarter over quarter for 13 of the 15 perpetually non-traded BDCs tracked by Fitch Ratings that reported 3Q26 tenders. However, requests remained elevated, averaging 9.8% of shares and exceeding the 5% cap at nine BDCs. Fitch expects redemption requests to decline further on average in the coming quarters. Requests will likely remain elevated compared to pre-2026 levels as firms continue to work through previously pro-rated requests.
Perpetually non-traded BDCs continue to cap redemptions at 5% of shares. Fitch considers this prudent because it preserves liquidity and leverage metrics. Rated perpetually non-traded BDCs have sufficient liquidity to cover several quarters of tenders at the stated maximum. Sustained tenders above 5% are not expected; however, they could pressure asset coverage cushions and ratings, particularly if inflows remain slow.




Latest news
Direct lending volume fell 3% q-o-q to US$61bn in 3Q26
US direct lending issuance weakened in 3Q26, marking its third consecutive quarterly decline. Volume fell 3% quarter-over-quarter to US$61bn, 30%…
US private debt rolling one-year horizon IRR by type
Overall, private debt returns for most asset classes in 2025 are showing a decline compared with 2024 levels. Interest rate cuts are part of this story, but the drivers vary by asset class, with the most common explanation being spread compression due to crowded debt strategies, such as direct lending.
