


Markit Recap – 2/15/2016

The shrinking of balance sheets has become a common theme in recent years, particularly in the financial sector. Investors are punishing banks that either unwilling or unable to implement a more conservative financial strategy.
It is increasingly clear that the same phenomenon is now observed in the commodities sector. Mining firms need to scale back their ambitions if they are to survive the new era of low prices. The questions credit investors are asking, however, is can firms deliver on their promises?
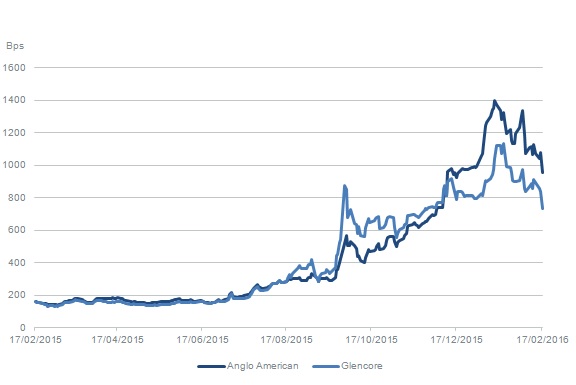
UK-based miner Anglo American has been under intense pressure since commodity prices embarked on their precipitous decline last summer. Its five-year CDS spreads widened from 150bps in June 2015 to 1,400bps (in practice 27points upfront) last month, making a mockery of its investment grade rating. Moody’s duly downgraded the firm to Ba3 from Baa3, while Fitch followed suit with a more modest cut to BB+. This brings the ratings close to the CDS market, though they still don’t match Markit’s CCC implied rating.
Both agencies left Anglo American on negative outlook, a reflection of the difficulties in turning around a firm with high capital expenditure, high debt and falling revenues. But there are tentative signs that the market may buying into the management’s new strategy. The company announced ambitious new debt reduction targets, asset disposals and a focus on just three products – copper, platinum and diamonds. It also said that it will be positive cash flow this year, compared to previous forecasts of $1bn negative cash flow – music to the ears of credit investors. Anglo’s spreads reached 920bps on February, the tightest level since December.
A similar spread pattern has been observed in Glencore, which up until December was trading wider than Anglo. But the firm has started to recover in recent weeks and received a further vote of confidence when it agreed new loan syndication agreements that will replace an existing revolving credit facility. This alleviates near-term liquidity concerns and may help it cling on to its fragile investment grade rating.
Contact: Gavan Nolan
Email: Gavan.Nolan@markit.com




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
