


PE Still Outperforms in the Long Run
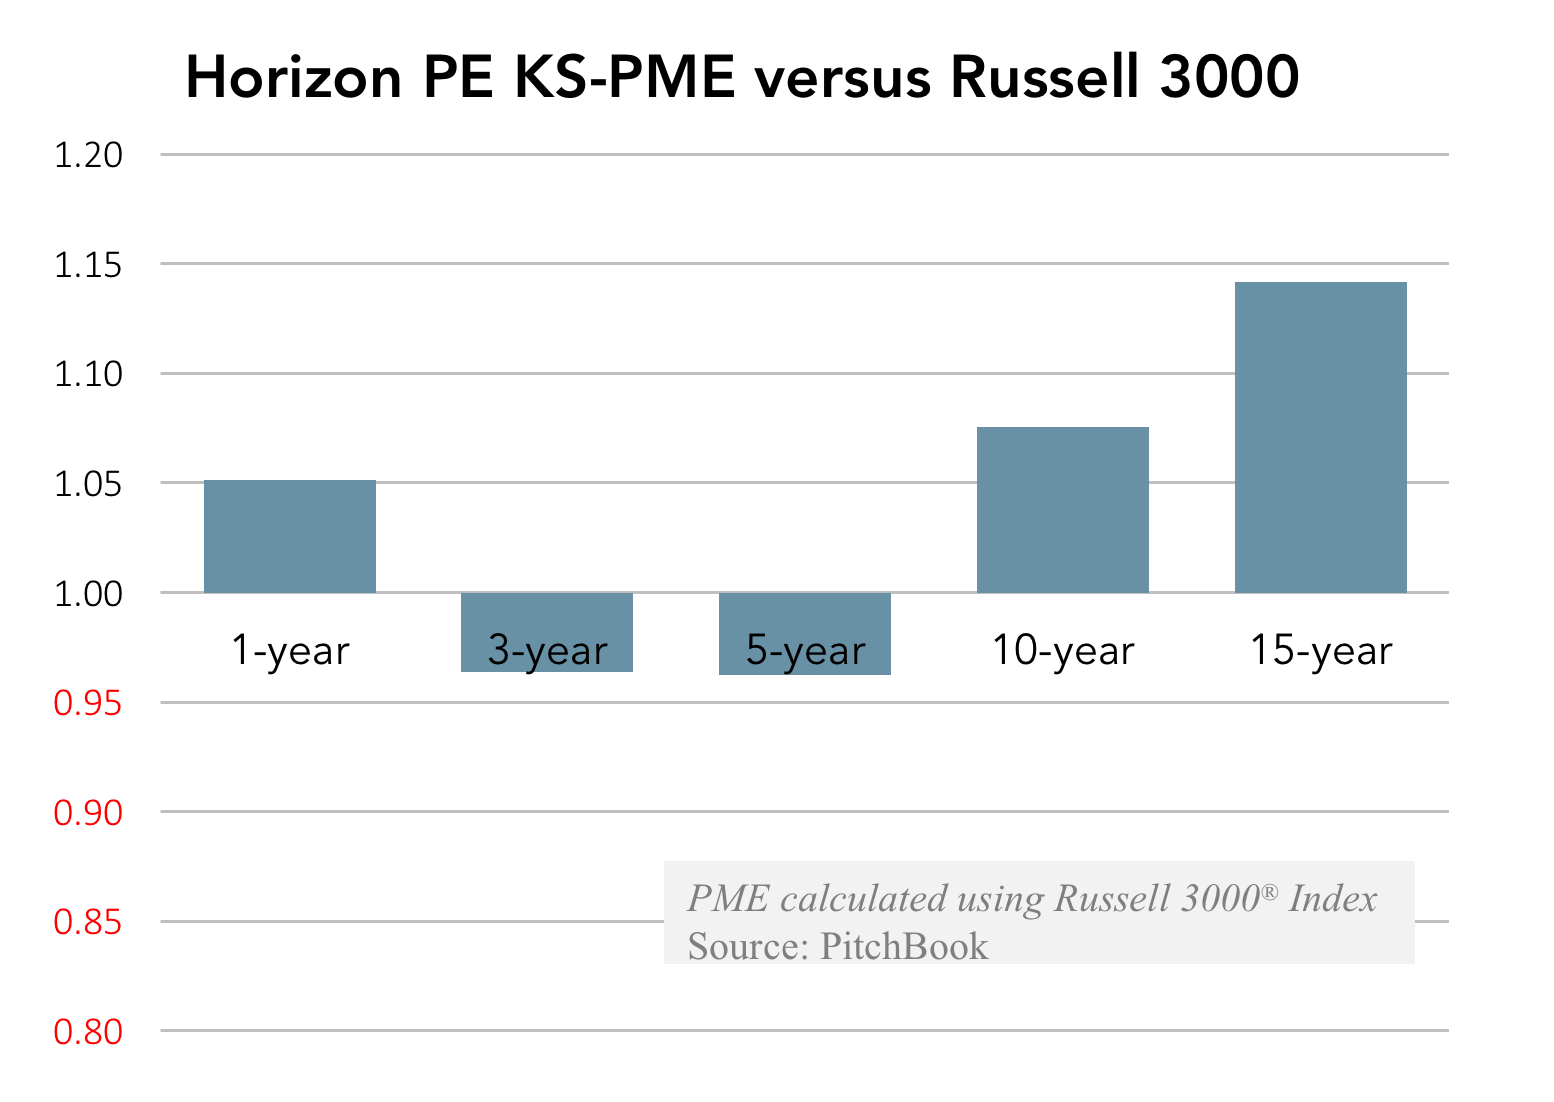
The key value-adding proposition of private equity fund managers is that they offer more stable, market-beating, safer returns across longer timelines that of course lead to relative illiquidity. And thus far, PE managers have made good on that value proposition. In addition to tracking vintage PE funds against comparable public market indices with KS-PME benchmarks, breaking out PE returns into horizon IRRs versus public markets can provide a perspective on population performance. As is clear from the above, midterm PE fund performance falls short of public markets’ performance, yet in the long run, PE fund managers have beaten public performance by a fair margin, up to nearly 15% at the longest horizon.
Such numbers help explain continued strong fundraising by PE firms, but also contain much greater implications when considered within the broader macroeconomic landscape. As volatility and low interest rates remain much more significant factors—for public pension funds in particular—the illiquidity PE investment strategies entail may seem like a small price to pay for outperformance and stability. Is such outperformance guaranteed? No more than any other investment strategy, but the PE industry’s results speak for themselves, particularly when considering that such long-lived investments underwent the financial crisis. Given the asset class’s appeal, PE managers have to contend with a considerable level of competition and consequent costly auctions for quality companies nowadays, making outperformance all the more difficult, however. Accordingly, lofty returns of the like seen above may not be experienced again by many, but the thing is, will limited partners in PE funds be satisfied with lower performance as long as it still beats the market? In today’s market, they well might be. So PE fundraising will likely continue apace, even if eventual saturation takes a toll and activity diminishes somewhat. As for PE managers being able to deliver on their proposition in a fashion at least somewhat similar to the past, only time will tell, although there is a clear historical basis for optimism, particularly when considering the nature of current PE buy-and-build strategies.
☞ Read PitchBook’s Benchmarking Report here.
Contact: Garrett Black
garrett.black@pitchbook.com


Latest news
US leveraged loan primary market stalls in 4Q26
Primary market activity in the US leveraged loan market has slowed sharply in the fourth quarter. Just $34.9b of new…

Direct lending M&A declines QoQ and YoY except in upper middle market
M&A activity declined 12% in the third quarter of 2026 to 296 deals, from 336 recorded in the second quarter.