


Private Debt Intelligence – 10/03/2016

Strategies Targeted by Private Debt Investors
According to Preqin’s Investor Outlook: Alternative Assets, H2 2016, 56% of investors with an active mandate in private debt are seeking to make at least one direct lending commitment within the next 12 months, the largest proportion among strategies in the asset class. The fundraising landscape reflects such investor appetite; direct lending accounts for the highest number of funds currently in market (120) and the largest amount of capital ($47bn) as a proportion of aggregate capital targeted.
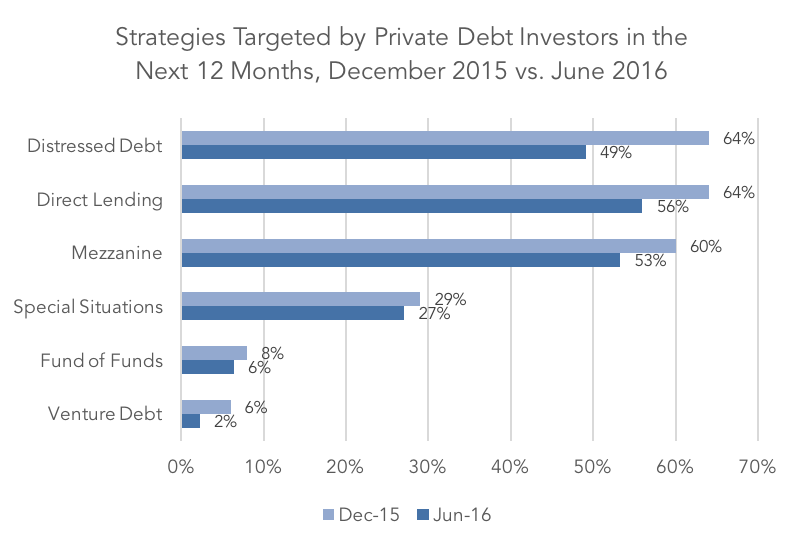
The second largest amount of capital ($45bn) is being sought by distressed debt funds, and the strategy is targeted by 49% of investors in the next 12 months. However, the proportion of the strategy saw the greatest decline of any strategy over the past six months, falling 15 percentage points since the beginning of the year.
Investor demand for mezzanine fund exposure in the next 12 months has declined to 53% as of June 2016 from 60% in December 2015, while special situations funds are currently being targeted by 27% of investors, a slight decrease from 29% at the end of 2015. Moving towards the more niche categories within private debt, the proportions of investors seeking to make fund of funds and venture debt commitments have both decreased in the first half of this year, and currently stand at 6% and 2% respectively.
The decline in the proportion of investors targeting every single strategy points towards investors taking a more singular approach when committing to the industry. The private debt industry is reaching a point of maturity and as such investors are now able to tailor their approach to the asset class, and invest in the fund types that sit most appropriately within their portfolio.
As investor sentiment continues to be the main driver of successful fundraising cycles, direct lending and distressed debt have so far reaped the most benefits from the current global economic climate. Fierce competition for allocations remains within the industry, as more and more vehicles come to market in hopes of successful closings.
With assets so highly contested, the differentiation, scope and terms of a fund will be vital for fund managers looking to secure investor commitments to private debt in 2016.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…