



Sustained High Multiples Contributing to Deal Values in the US Lower Middle Market
In a recent Lead Left column, we observed that median enterprise value/EBITDA buyout multiples for businesses with EVs of under $25 million were quite high, at 6.13x in 2Q 2016. Coupling that with yearly deal flow figures for the US lower middle market—defined herein as transactions between $25 million and $100 million—it’s clear that continued competition for deals and sustained high prices for quality companies is helping elevate transaction multiples and consequently overall deal value even at the lowest ends of the middle market. Currently, the US LMM has seen nearly $28 billion in total deal value in 2016, compared to $30.5 billion last year. Should the volume of dealmaking continue at a pace similar to 3Q, which saw a multiyear low of 117 closed investments, 2016 may well end up with a tally similar to 2012’s $33.8 billion. However, the typical year-end surge may help pick things up a bit, with 2016 then turning out to be the third-highest year of the decade for total LMM value.
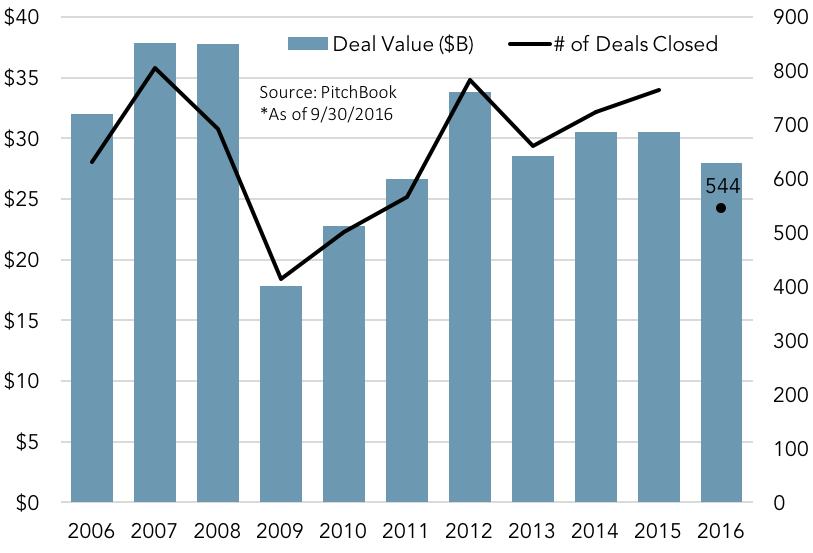
There are further implications beyond the simple observation that the lower reaches of the middle market are quite popular nowadays. Since private equity buyout shops are sourcing so widely, and, moreover, are still firmly staying away from the mega-buyouts of old, then it’s more likely than not that a shrunken supply of worthwhile targets is contributing to the slowing of the buyout cycle. The question then is how much the buyout cycle may slow by, and how long that will take. As long as the cost of borrowing remains low and PE capital overhang so bulky, it really does come down to a matter of supply. Accordingly, the slowing of the cycle still has some ways to go, as a fair degree of consolidation among small-to-medium businesses in certain sectors either due to generational wealth transfers or industry cycles is still ongoing—generating opportunities for financial sponsors—in which the quality of the company in question becomes the primary obstacle.
Contact: Garrett Black
garrett.black@pitchbook.com


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…