


Markit Recap – 10/24/2016

Credit investors, whether in cash or synthetics, often welcome corporate restructurings by distressed firms. Job cuts, rationalisation of operations and, in particular, asset sales are usually regarded as bondholder friendly actions.
But this ‘wasnt the reaction when Banca Monte dei Paschi di Siena (MPS) announced plans to restructure its ailing business. The Italian bank said that it would reduce jobs by 2,500 – cutting 10% of its staff costs – and close 500 of its 2,000 branches over the next three years. MPS also declared that it would sell its payments processing unit for €520 million.
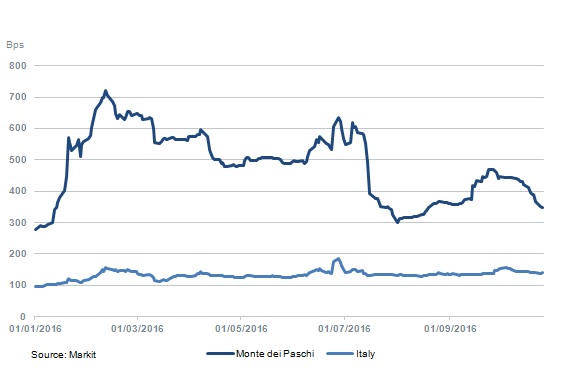
Turnaround plans of this kind would normally result in CDS spreads rallying. But, although there was some initial improvement after the plans were announced, the gains were quickly lost. MPS senior spreads closed on Monday at 351bps; by the close on Wednesday they were a touch wider at 355bps. It was a similar story in MPS’ subordinated spreads, which are a better indicator of likely default. They were trading at 25 points upfront on Monday and were unchanged two days later.
So why were the credit markets underwhelmed by the bank’s plans? Perhaps it was priced in: MPS senior spreads have rallied over 100bps since August and subordinated spreads by 13 points since September (the two tiers don’t always move in tandem due to economic differences under ISDA 2014 definitions). Or it may be down to doubts that the bank can deliver on its promises. MPS will try to implement a debt-for-equity swap in early December as the first stage of its recapitalisation, followed by a rights issue. The bank will require recapitalisation due to its €30bn of non-performing loans, which it is planning to sell into a securitisation vehicle backed by the government and other Italian institutions.
All of this is subject to significant execution risk, and if it fails then a government enforced bail-in will be one of the few options available to MPS. And then there is the Italian referendum in December, which could be another catalyst for systemic volatility. Credit investors may not be as bearish on MS as they were earlier this year, but it faces a long and difficult road back to safety.
Contact: Gavan Nolan
Gavan.Nolan@ihsmarkit.com



Latest news

With inflation running hot, rate hike expectations strengthen
A hotter-than-expected inflation reading has renewed expectations for near-term Federal Reserve tightening. The Consumer Price Index rose 0.6% month-over-month, pushing…

Open Tab
Leveraged loans keep running up a tab. Senior direct lending already knows what it owes.
