


A hotter-than-expected inflation reading has renewed expectations for near-term Federal Reserve tightening. The Consumer Price Index rose 0.6% month-over-month, pushing the annual inflation rate to 3.7%, above consensus expectations and reviving bets on an October rate hike that had moderated in recent sessions.
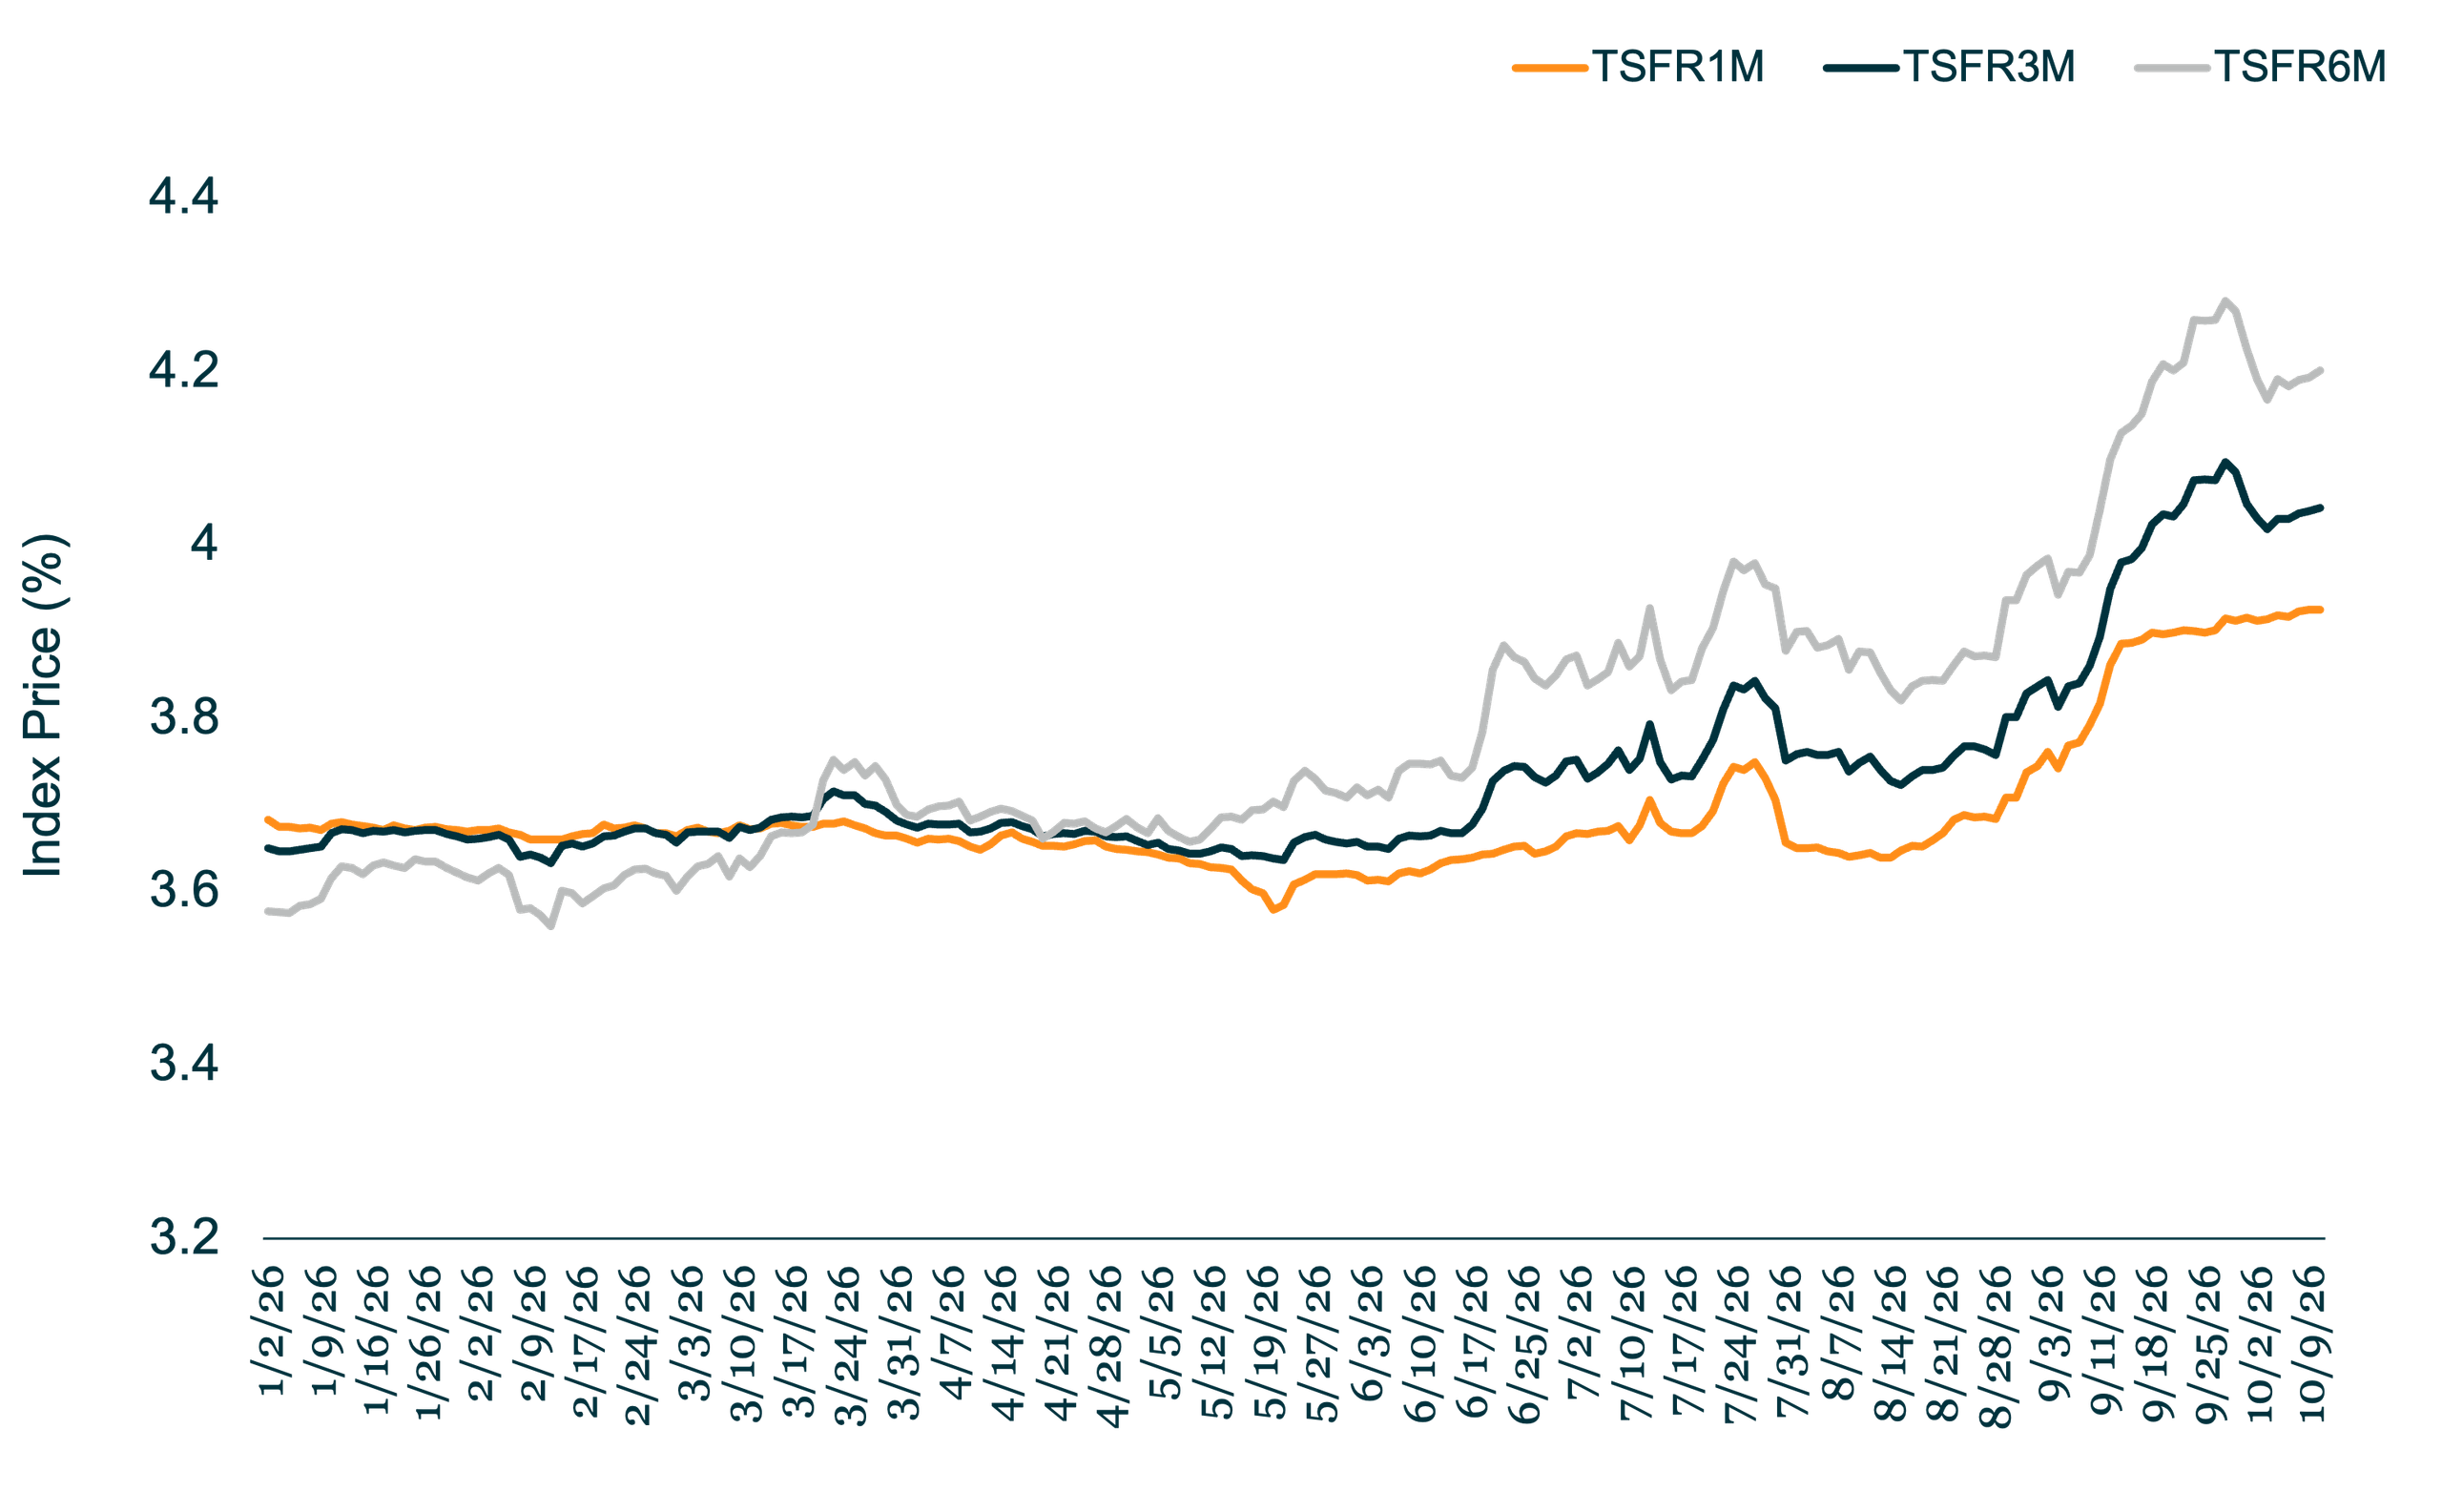
The shift is reflected in the Term SOFR curve, where the spread between three-month and one-month Term SOFR widened to 12.8 basis points from 11.7 bps following the inflation report. Meanwhile, the six-month versus three-month spread remained broadly unchanged at 15.6 basis points. The relative steepening at the front of the curve suggests investors have increased expectations for monetary tightening in the nearer term.
More broadly, the Term SOFR curve has undergone a pronounced hawkish repricing in 2026, shifting from expectations for continued monetary easing at the start of the year toward a higher-for-longer rate outlook. The move accelerated in September, when six-month Term SOFR reached 4.281% and its premium over the one-month benchmark widened to a 2026 high of approximately 37 bps.
While that premium has since narrowed to approximately 28 bps, the curve remains firmly upward sloping. This suggests that although expectations for the magnitude of future tightening have moderated from late-September highs, investors continue to price in elevated rates over the coming months.



Latest news

Open Tab
Leveraged loans keep running up a tab. Senior direct lending already knows what it owes.


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.