



Download PitchBook’s Report here.
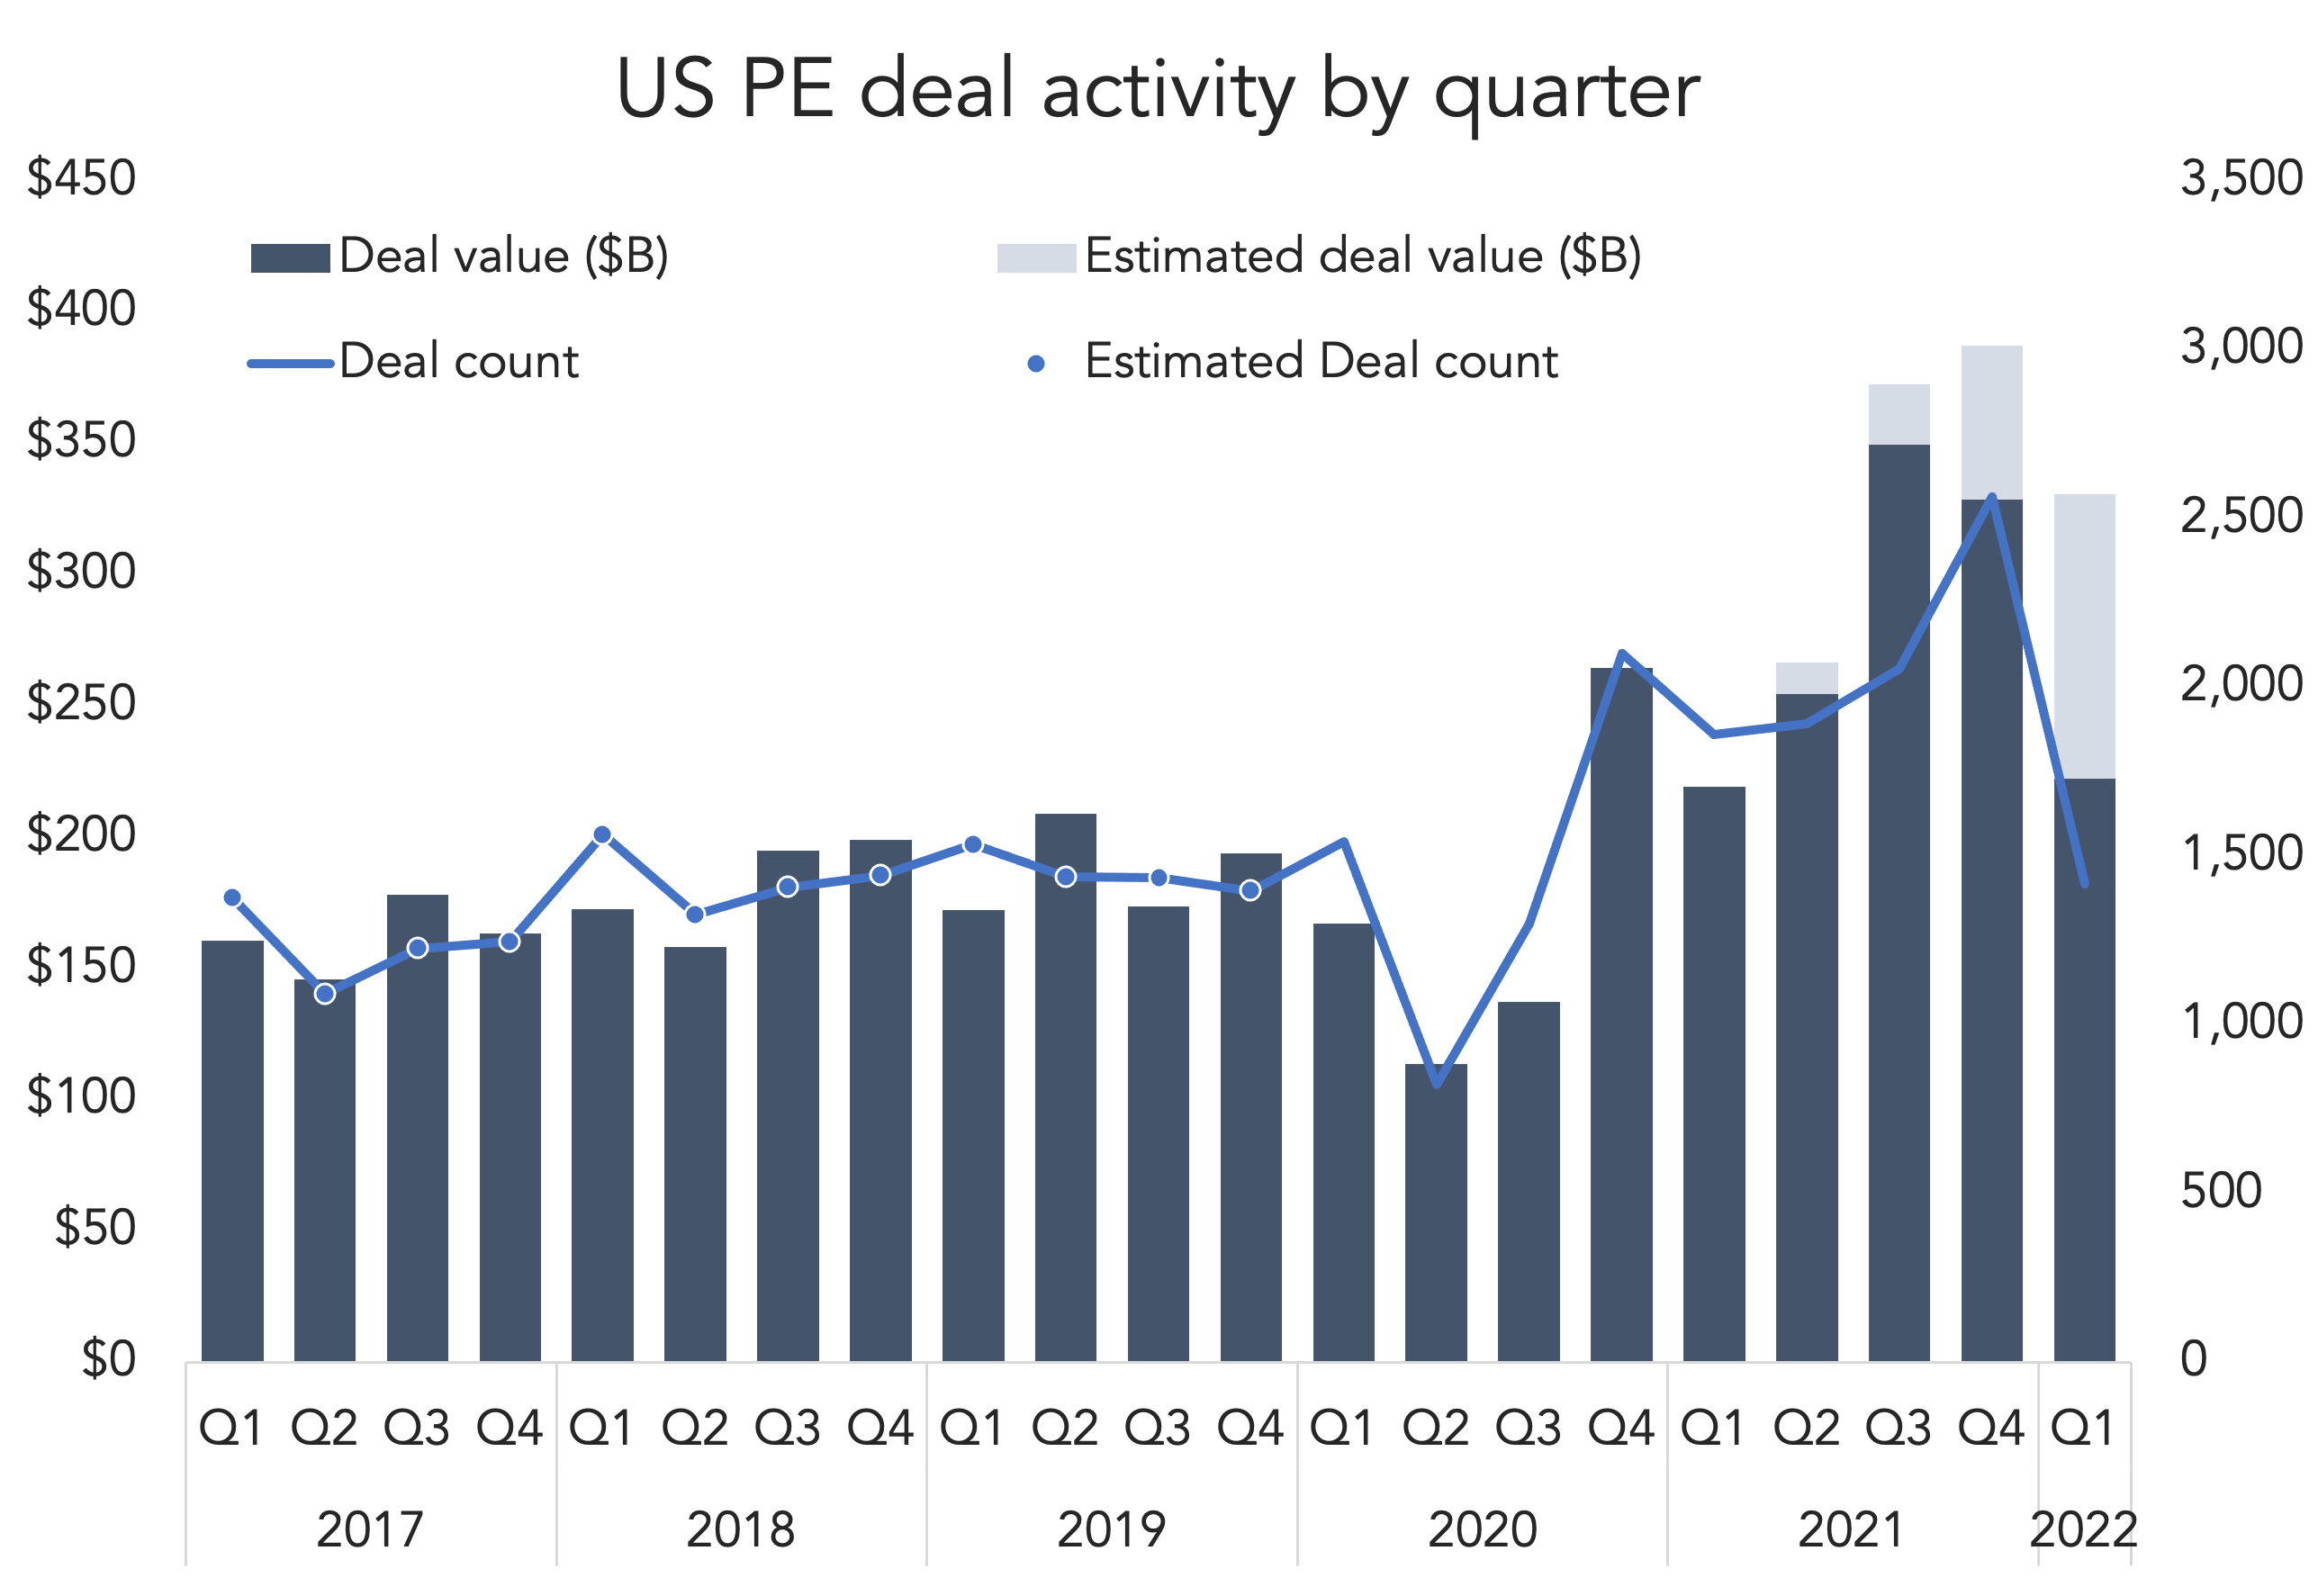
PitchBook’s Q1 US PE Breakdown Report is out. The first quarter saw an estimated $330.8 billion invested, a strong showing and the third highest quarter we’ve calculated. It’s not quite as high as the back half of last year, which saw $372.3 billion invested in Q3 and a record $387.3 billion in Q4. Still, a would-be pace of $330 billion per quarter would catapult 2022 above the $1 trillion mark again. There are reasons to be skeptical this pace will hold, though. The specter of interest rate increases spurred at least some Q1 activity, and rising costs pose a separate risk to portfolio company margins going forward.
One metric that didn’t slow down quarter-over-quarter was buyout multiples. The median four-quarter EV/EBITDA multiple registered at 14.6x in Q1, unchanged from Q4. While multiples have generally been higher under Covid, they’ve also been 13x or lower for most of the pandemic. The reason for the sudden spike, starting in Q4 2021, was because equity contributions surged to more than 8x, up substantially from the typical 6x-7x range in years past. Investors are ponying up more cash to get deals done, a dynamic that might stay with us as rate increases start to make borrowing more expensive.
(Past performance is no guarantee of future results.)


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…