



Median Multiples for U.S. PE Wane Further
Even taken with a grain of salt, the decline in median EBITDA multiples for U.S. private equity buyouts has become more and more pronounced as third quarter numbers roll in. Faced with the headache of high valuations, PE firms have not only been dialing down activity—albeit at a sedate pace – but also paying less. An array of drivers are behind this shift, with the usual suspects a decline in the supply of quality targets after a couple years of heavy deal flow as well as reluctance to overpay and depress future returns. 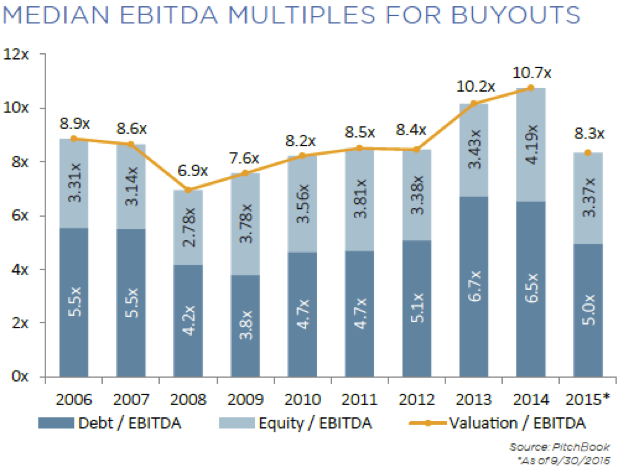 The PE industry’s usage of debt correlates with credit market cycles, too. Even though sponsors are likely to remain active in the middle market, as volatility in lending markets persists, the types of pricey buyouts that spike median multiples are going to be seen less and less. The question is how low of a floor median leverage levels will eventually hit. The Fed increasing interest rates shouldn’t spell too much trouble, mainly because the rate of increase should be slow and steady and, moreover, has been anticipated for some time. Middle-market PE sponsors will likely continue to utilize proportions of debt similar to what we’ve seen for the first three quarters of 2015, adjusting to supply constraints, although that last is a variable factor. Non-bank arrangers are only ramping up middle-market lending, with BDCs scenting opportunity for steady yields as many banks decrease their exposure. Non-bank lenders can push terms more aggressively than banks can in order to capture new business—it’ll be interesting to see how such courting of PE firms will affect lending trends going forward.
To Download PitchBook’s 3Q 2015 Global PE Deal Multiples & Trends Report, please click here.

Contact: Garrett Black
garrett.black@pitchbook.com




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
