


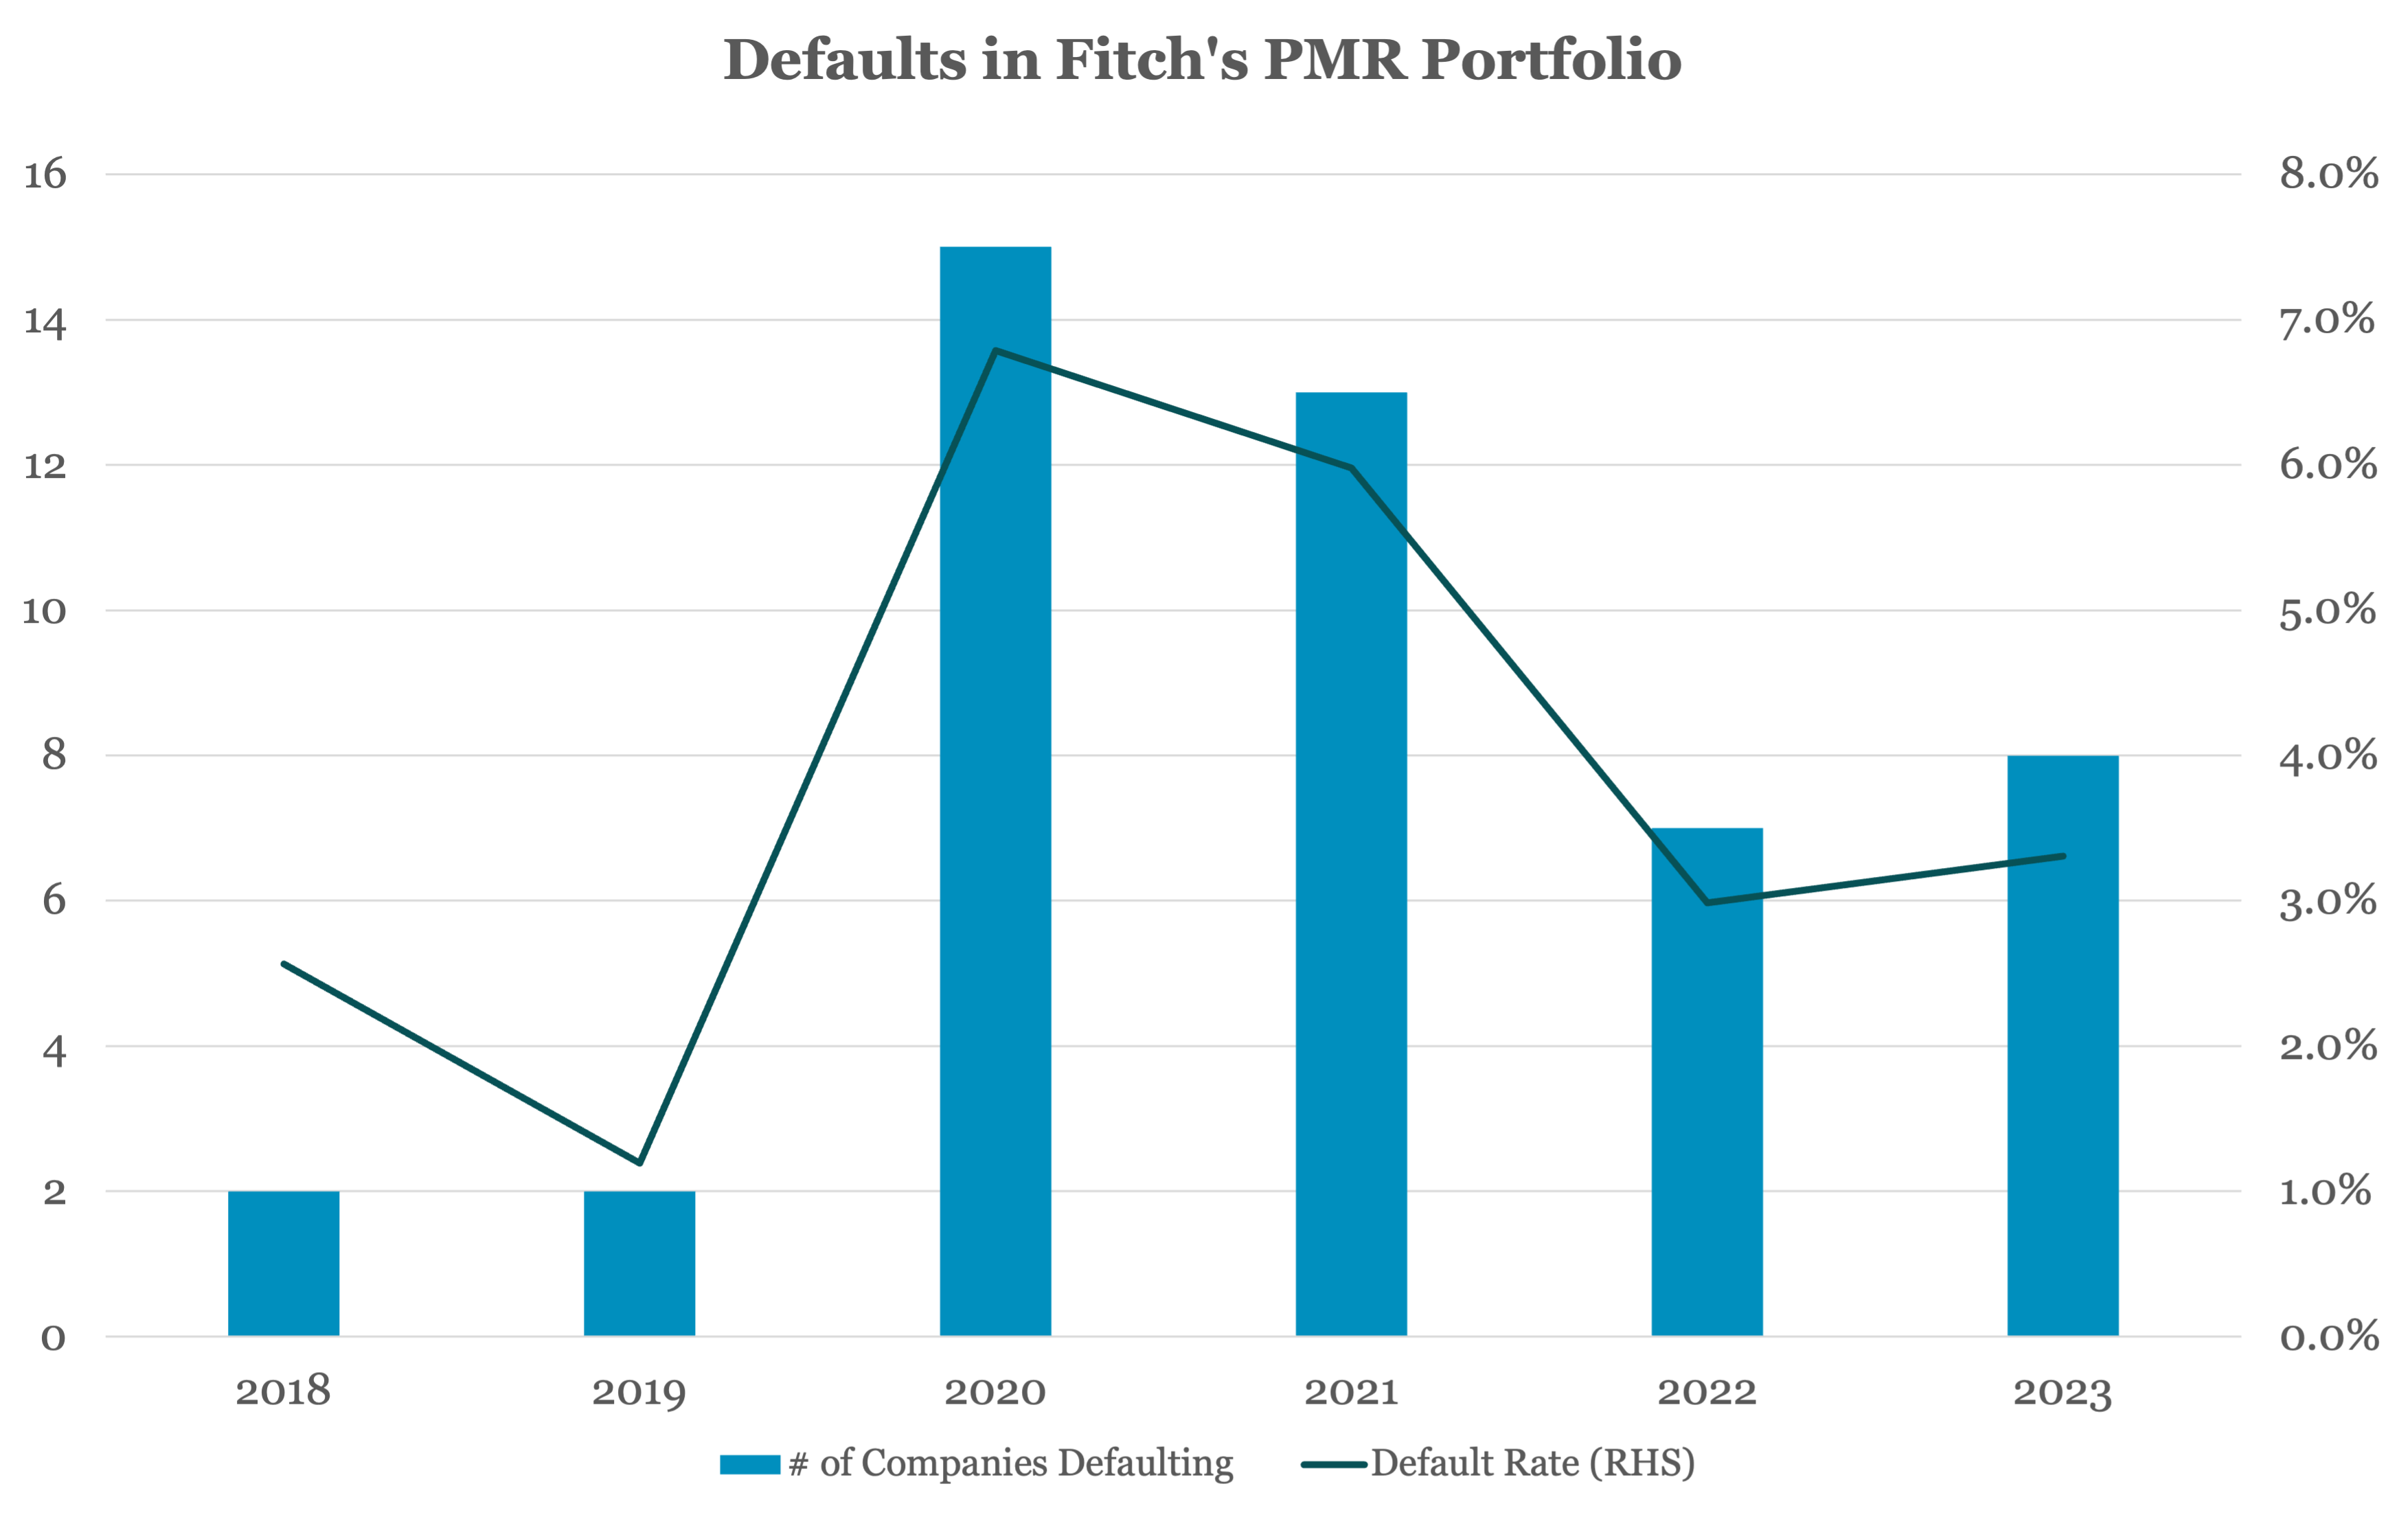
The default data is derived from Fitch’s portfolio of PMRs in the U.S. The ratings are largely of middle market sized companies of around $500 million of debt or less, or $100 million or less in EBITDA. These ratings are generally requested by asset managers that placed the loans with insurance companies requiring ratings for regulatory capital purposes. Fitch’s portfolio in the U.S. totals around 275 issuers, although the data draw from the ratings on more than 500 companies Fitch has rated in this portfolio since 2017. Since the portfolio reached a critical mass of more than 100 ratings in 2018, Fitch has recorded a total of 57 defaults across 37 unique issuers.
(Past performance is no guarantee of future results.)
Contact: Brad Hamner
brad.hamner@fitchratings.com




Latest news

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.
Reading the Board
The story changes depending on which numbers you’re counting.
Private Credit Defaults 101: Different Numbers, Different Stories
In Season 2 of Billions, Bobby Axelrod takes his lawyer Orrin Bach to an empty Yonkers racetrack in the dead of night.