


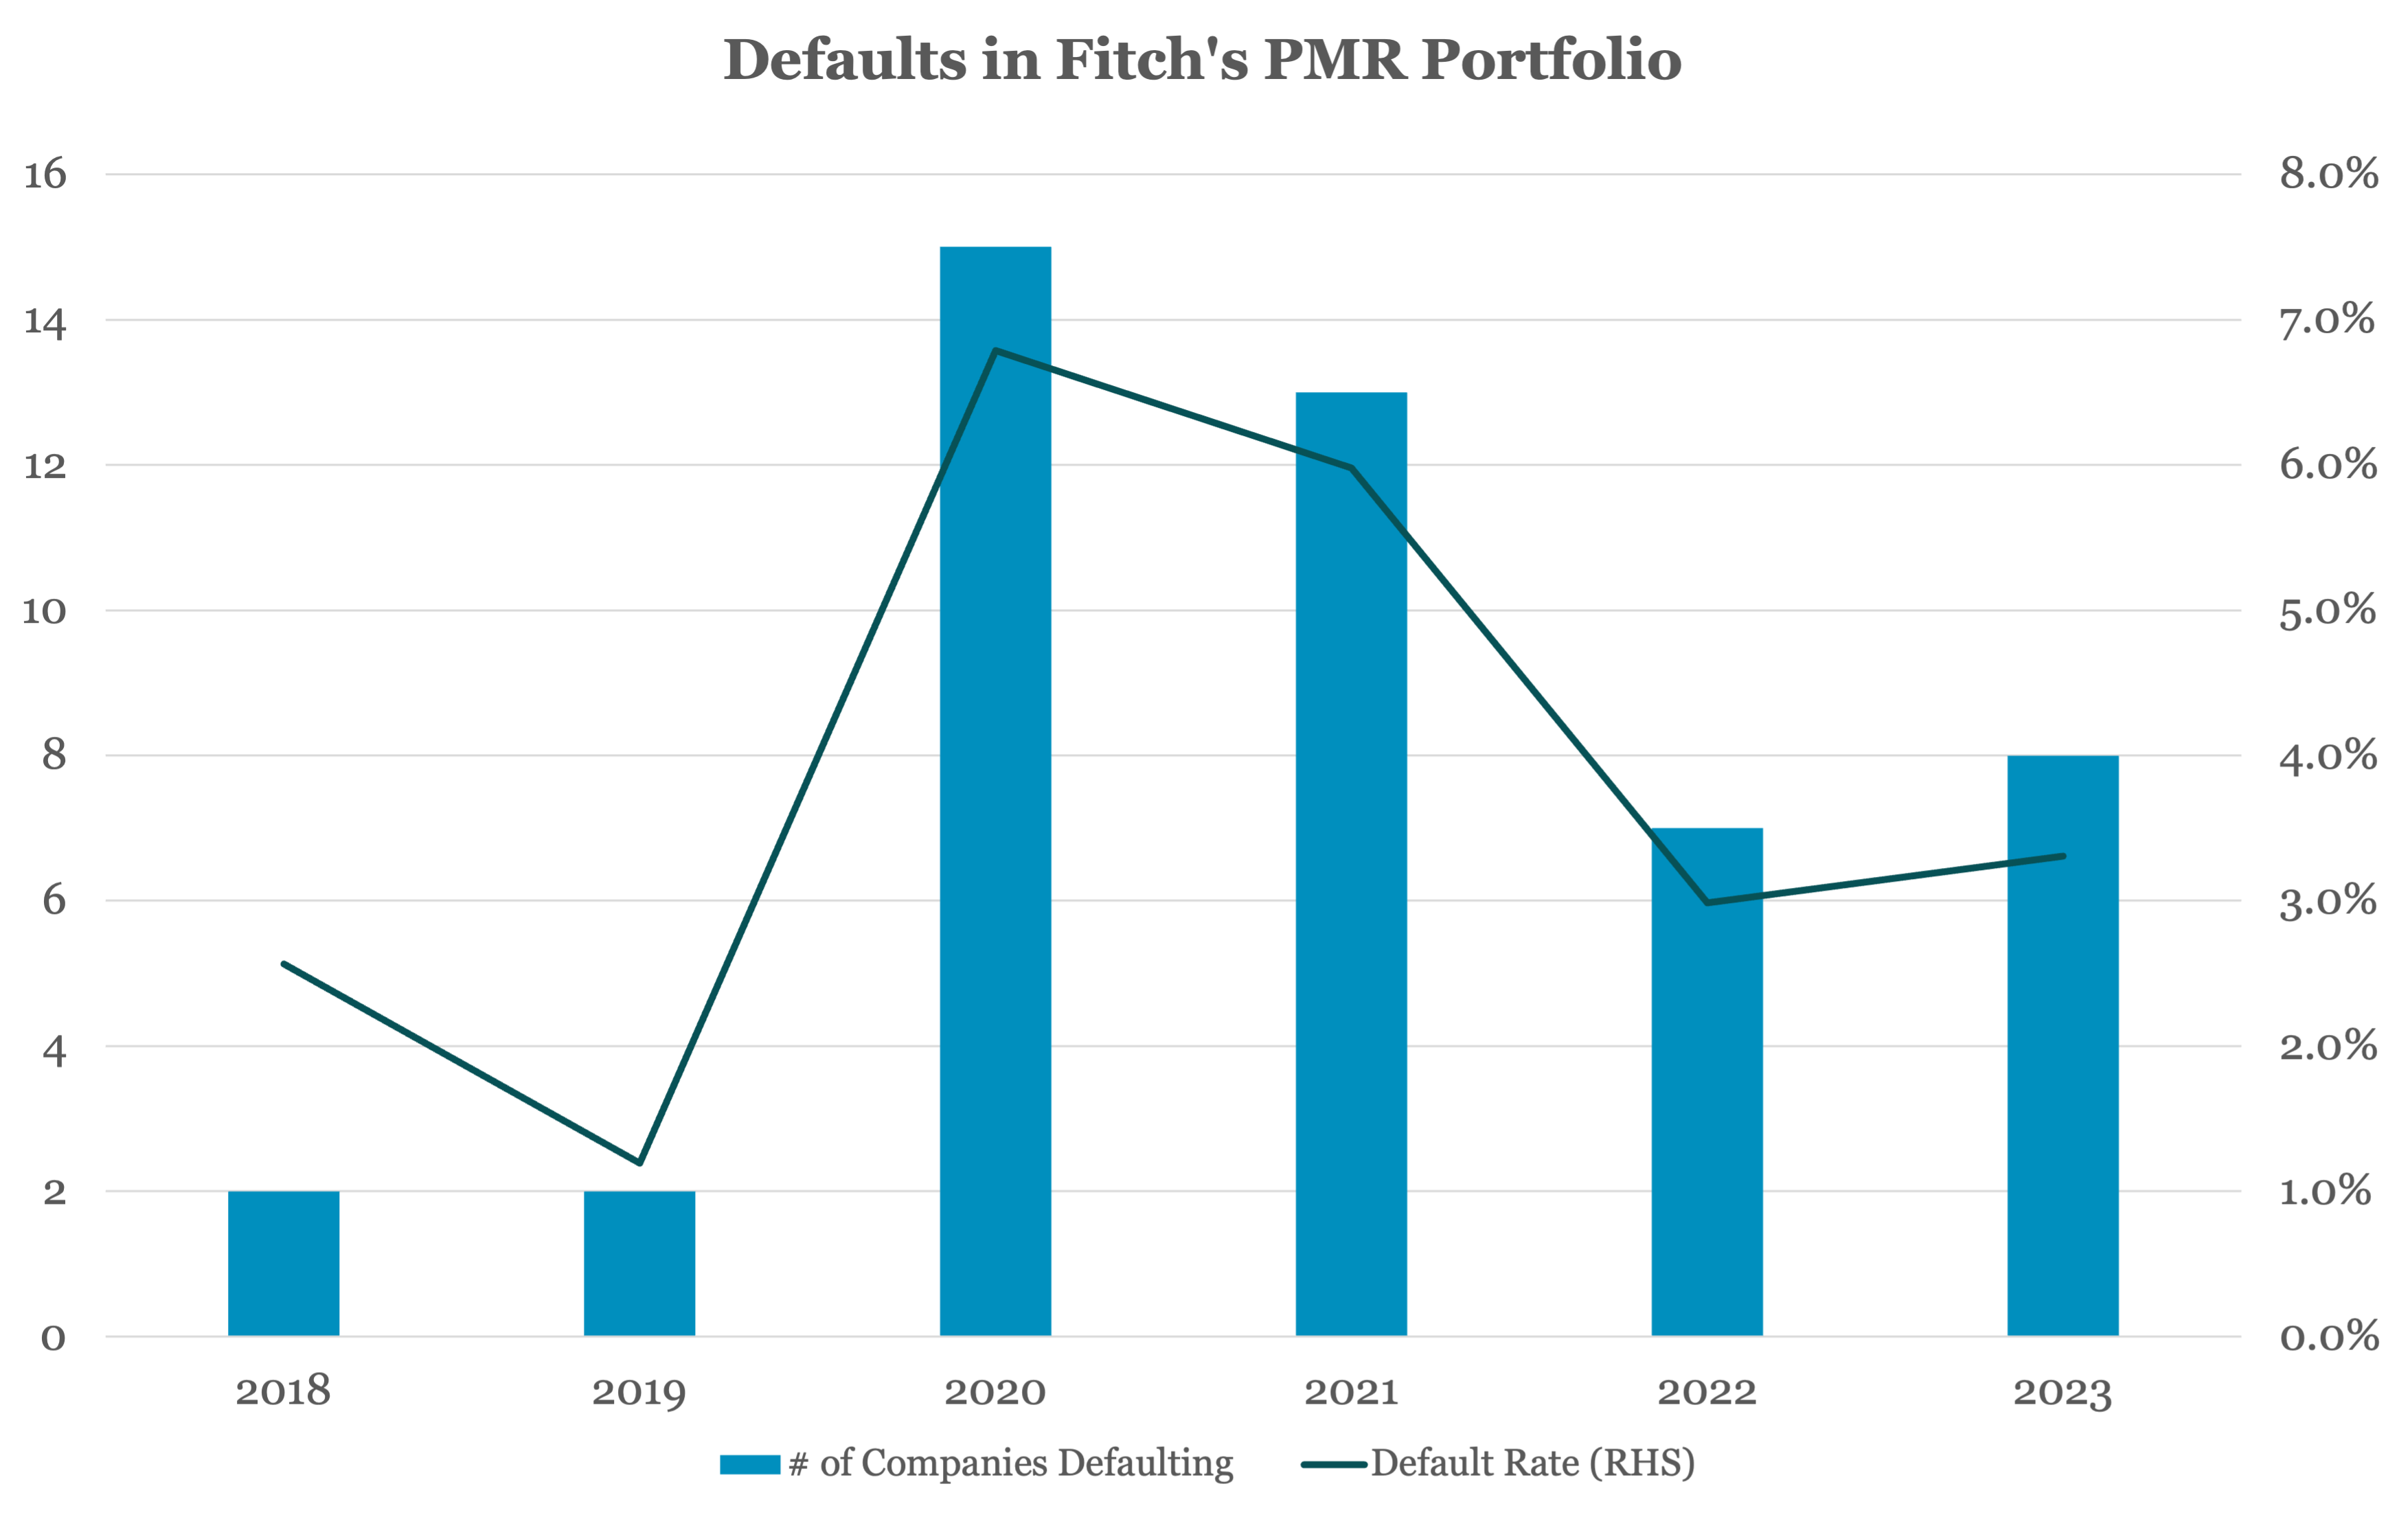
The default data is derived from Fitch’s portfolio of PMRs in the U.S. The ratings are largely of middle market sized companies of around $500 million of debt or less, or $100 million or less in EBITDA. These ratings are generally requested by asset managers that placed the loans with insurance companies requiring ratings for regulatory capital purposes. Fitch’s portfolio in the U.S. totals around 275 issuers, although the data draw from the ratings on more than 500 companies Fitch has rated in this portfolio since 2017. Since the portfolio reached a critical mass of more than 100 ratings in 2018, Fitch has recorded a total of 57 defaults across 37 unique issuers.
(Past performance is no guarantee of future results.)
Contact: Brad Hamner
brad.hamner@fitchratings.com


Latest news
Software, technology and consumer sectors lose deal share in 9M’26
The software and technology sector, the second most active sector in 2025 at 17% of total deal activity, slid to fifth place in the first nine months of 2026.


Leveraged loan investors see gains in November
Following a 0.25% decline in October, the Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned 0.60% this month through…