


All private markets, including private credit, experienced a tough 12 months on the fundraising trail in 2023. Hopes are higher for the year ahead.
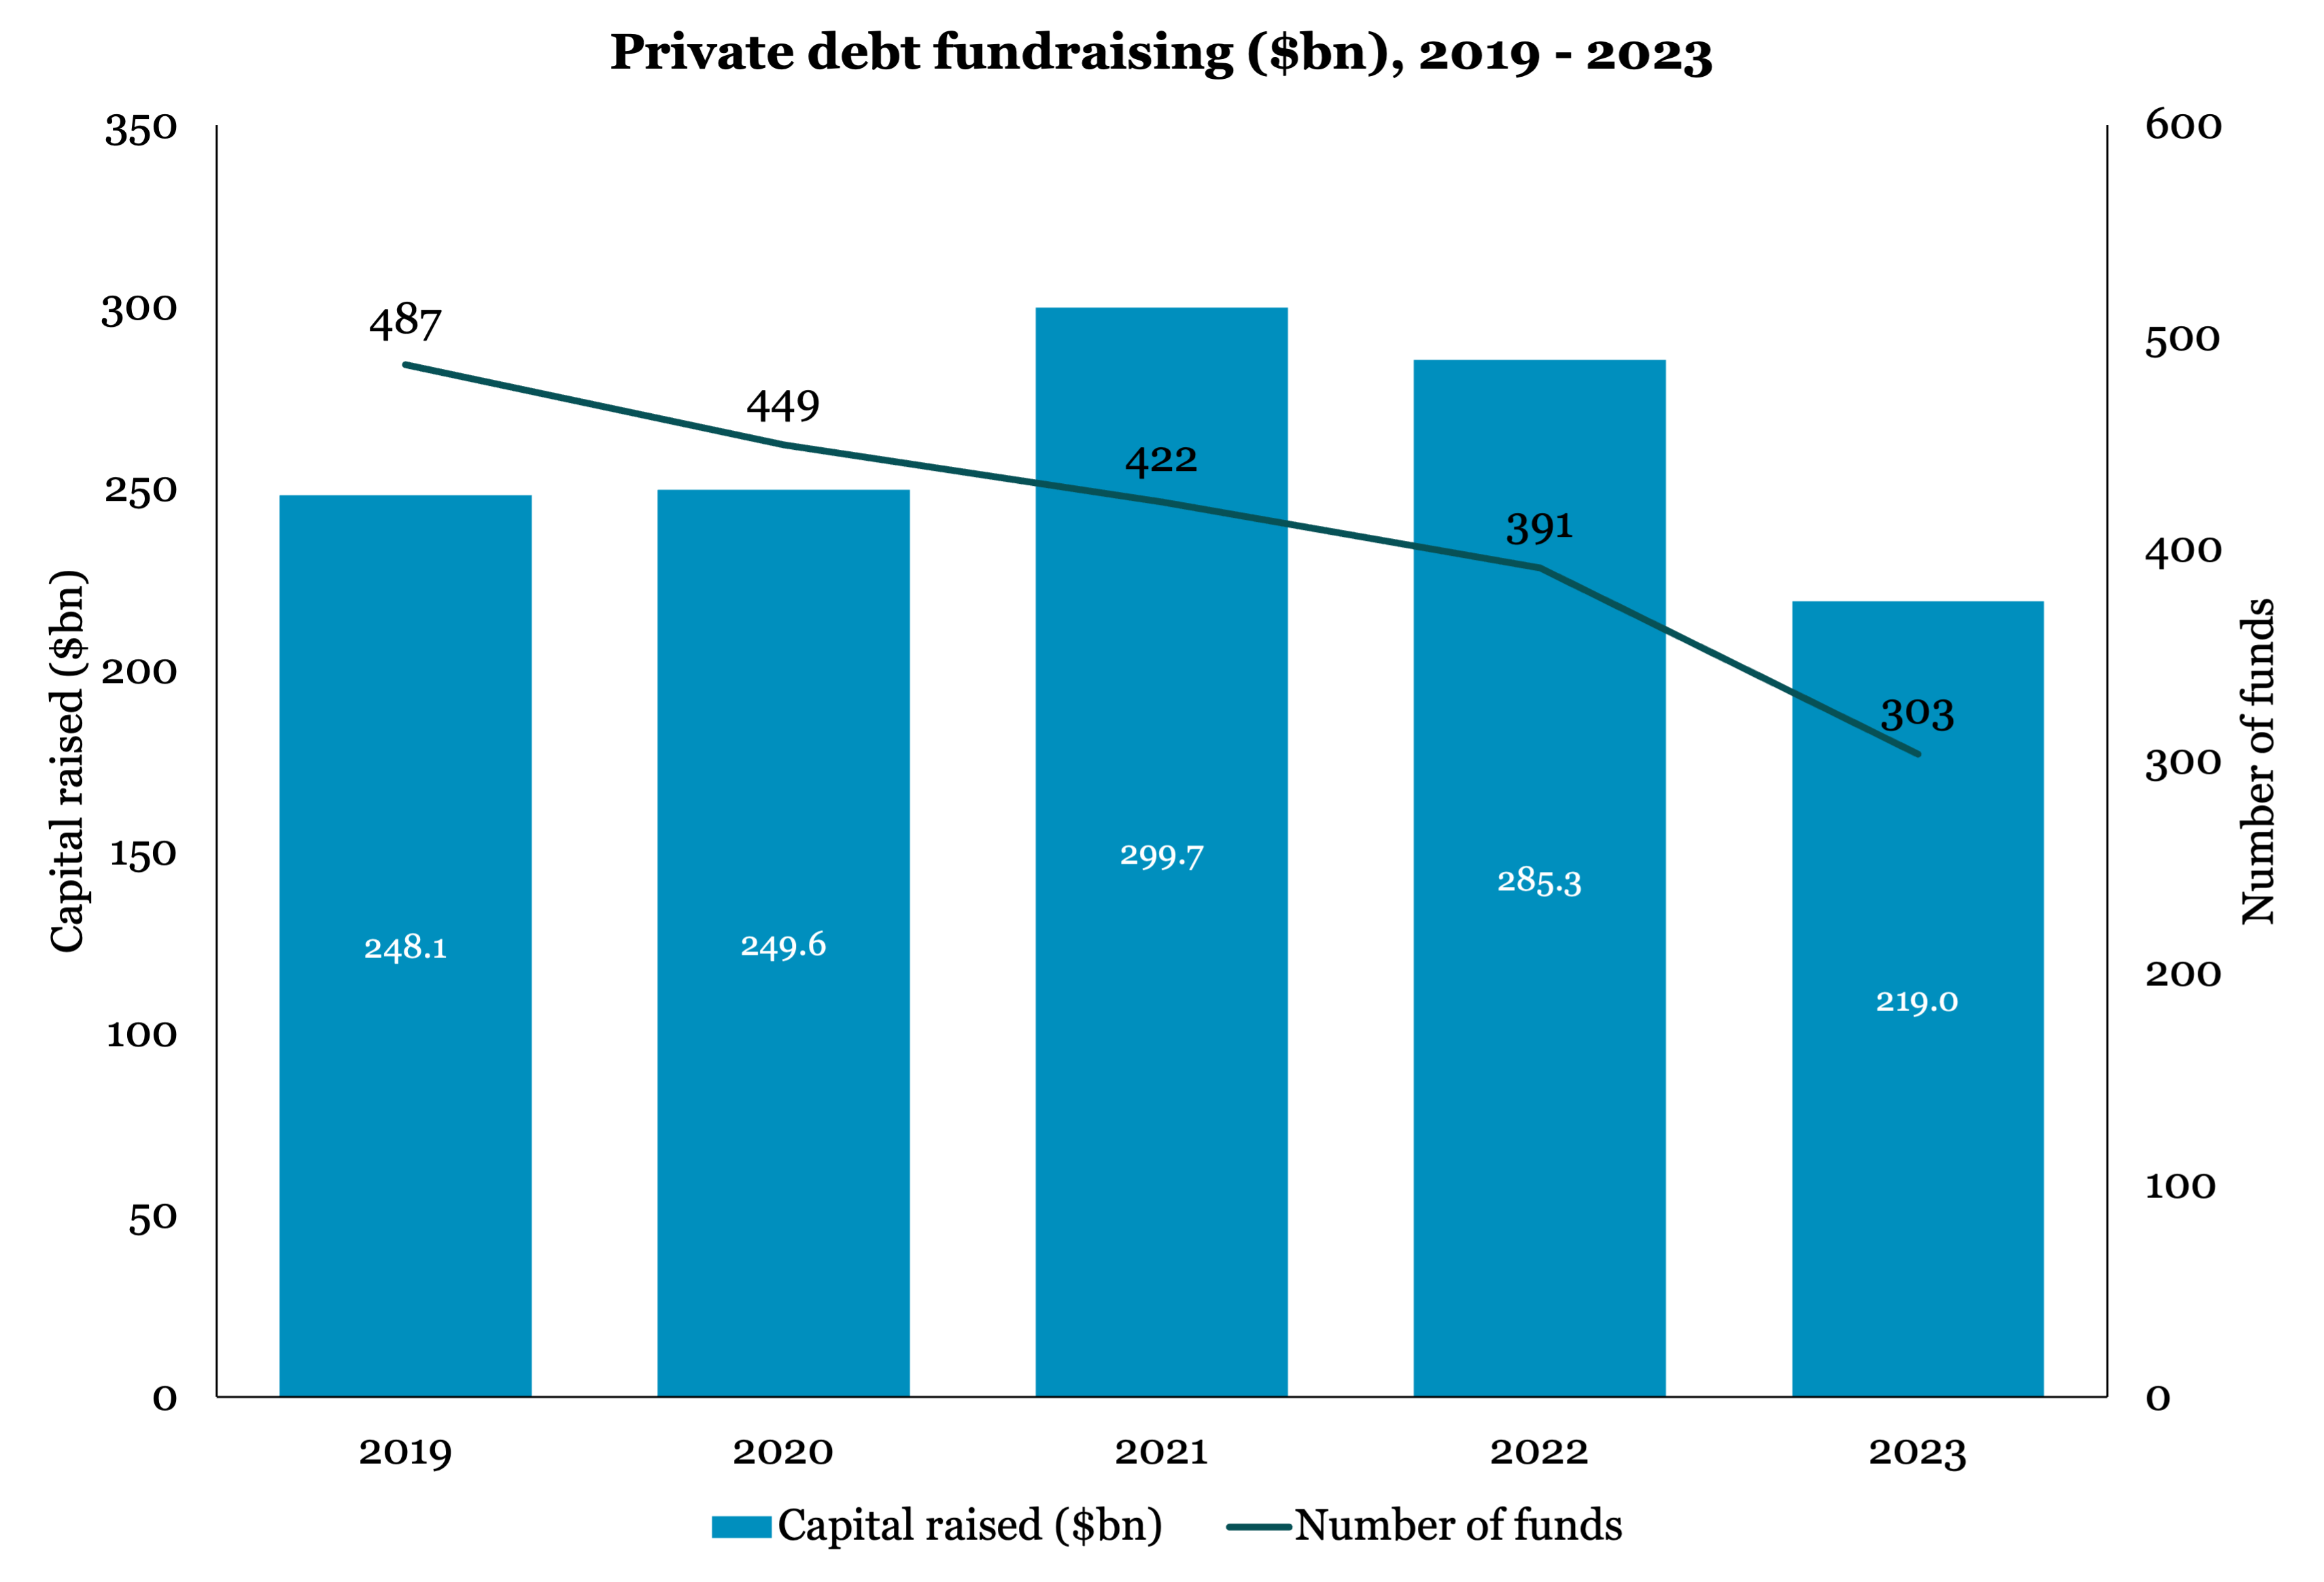
The fundraising figures are in for full-year 2023 and they reveal a drop in global private credit capital accumulation to just $219 billion, the lowest amount seen in a PDI Fundraising Report since 2016 when $180 billion was raised. The number of fund vehicles raised fell to 303, the lowest figure seen since 2012.
This mirrors a similarly difficult fundraising year in other private markets asset classes as LPs looked to rebalance their portfolios after a year of high inflation and sharp interest rate rises.
Despite the lower fundraising volume in 2023, the distribution of strategies remained remarkably stable. Senior debt continued to be the most popular strategy, making up 40 percent of the market followed by junior credit on 36 percent and distressed on 17 percent.
Average fund size sat above $1 billion at the end of the year. Notably, 2023 was the first year where average fund size was over $1 billion in each of our quarterly reports. This reflected a market where the most established fund managers were continuing to raise ever-larger vehicles amid a declining pool of smaller funds.
Perhaps the biggest story of the year was the huge divide between North American fundraising activity and that in Europe. Capital raised in North America still fell substantially, down almost $30 billion compared with 2022, but European fundraising saw a larger proportionate fall, approximately $27 billion lower, with just $39.1 billion raised as fears over energy prices, war and industrial performance came to the fore.
Despite a tough fundraising year, there remain a large number of credit funds actively raising in the market, seeking sums totalling almost $400 billion. If the economy begins to improve in 2024, as many expect, then we could see a rapid bounce-back in private credit fundraising.




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…