


Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
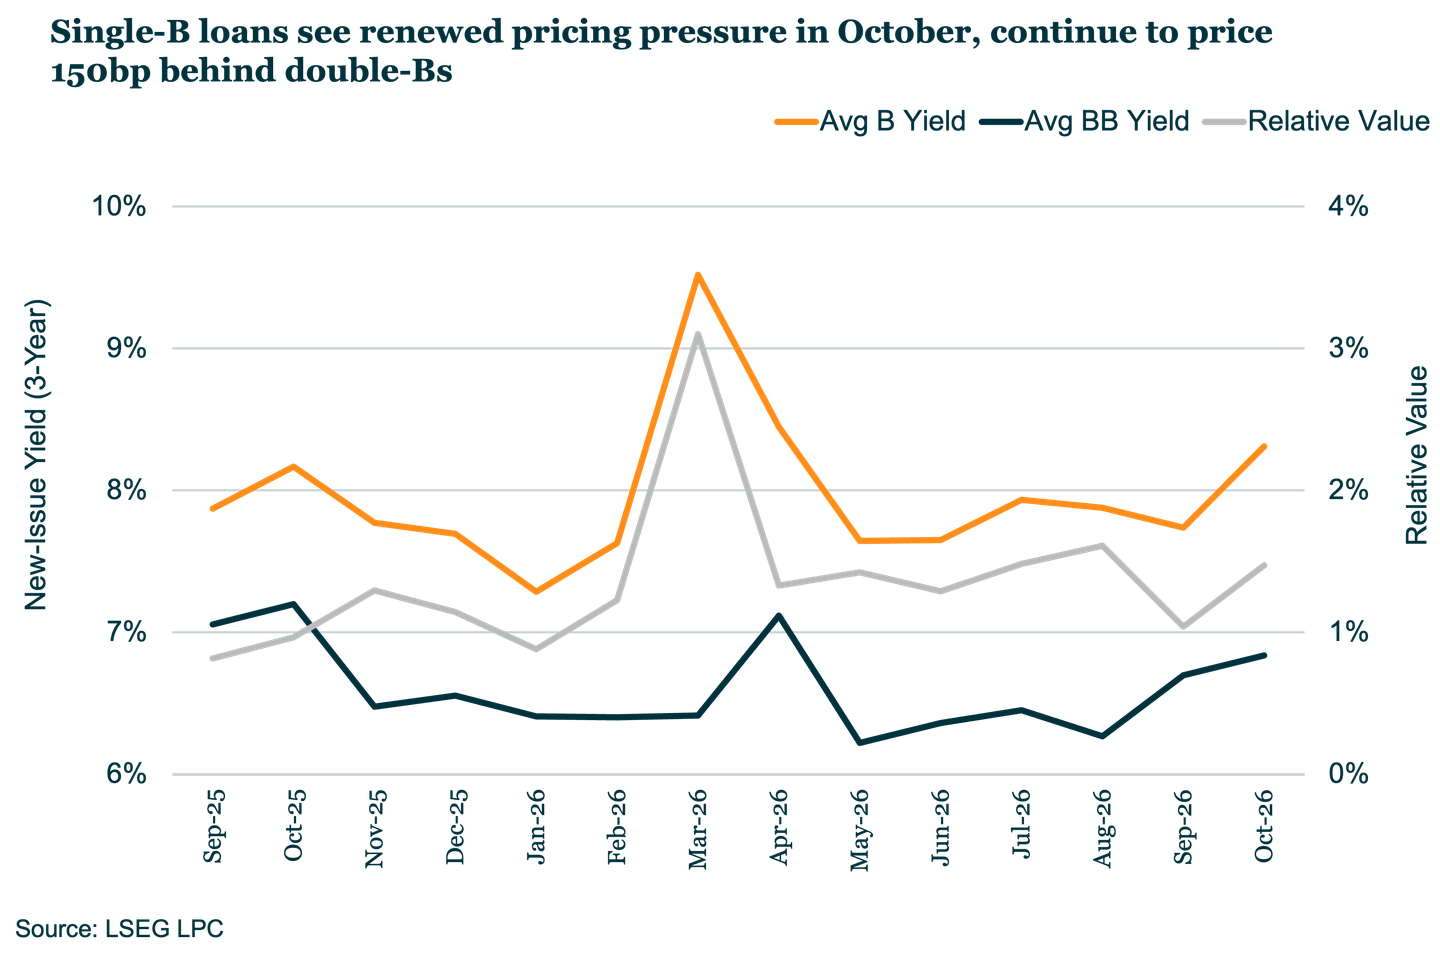
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp to roughly 7.25% in September while double-Bs actually widened 43bp to 6.20%. These convergent moves tightened the implied new-issue pricing premium for single-B credit risk to about +100bp, its tightest reading since January – although largely consistent with the delta we observed throughout all of last year. Fast forward through October and you can see how this pricing dynamic has largely reversed course: although new-issue yields widened across ratings segments – with single-Bs expanding 57bp to 7.81% and double-Bs adding another 14bp to 6.34% – the parallel but disproportionate moves brought that new-issue pricing premium right back to 150bp, essentially where it’s been anchored throughout all of this year. But here’s the kicker: single-B yields have hardly moved over the past 12 months, which suggests the following: (1) the 50bp MoM move in relative value was driven by a more normalized market, where single-Bs required disproportionately more yield premium; and (2) the 50bp YoY move was testament to a more bifurcated market, where double-Bs required disproportionately less.




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…
Private debt cashflows ($B)
Looking at the wider private markets funds landscape, private debt can be seen as a bright spot—for now—among individual strategies.