


Download FitchRating’s Report here.
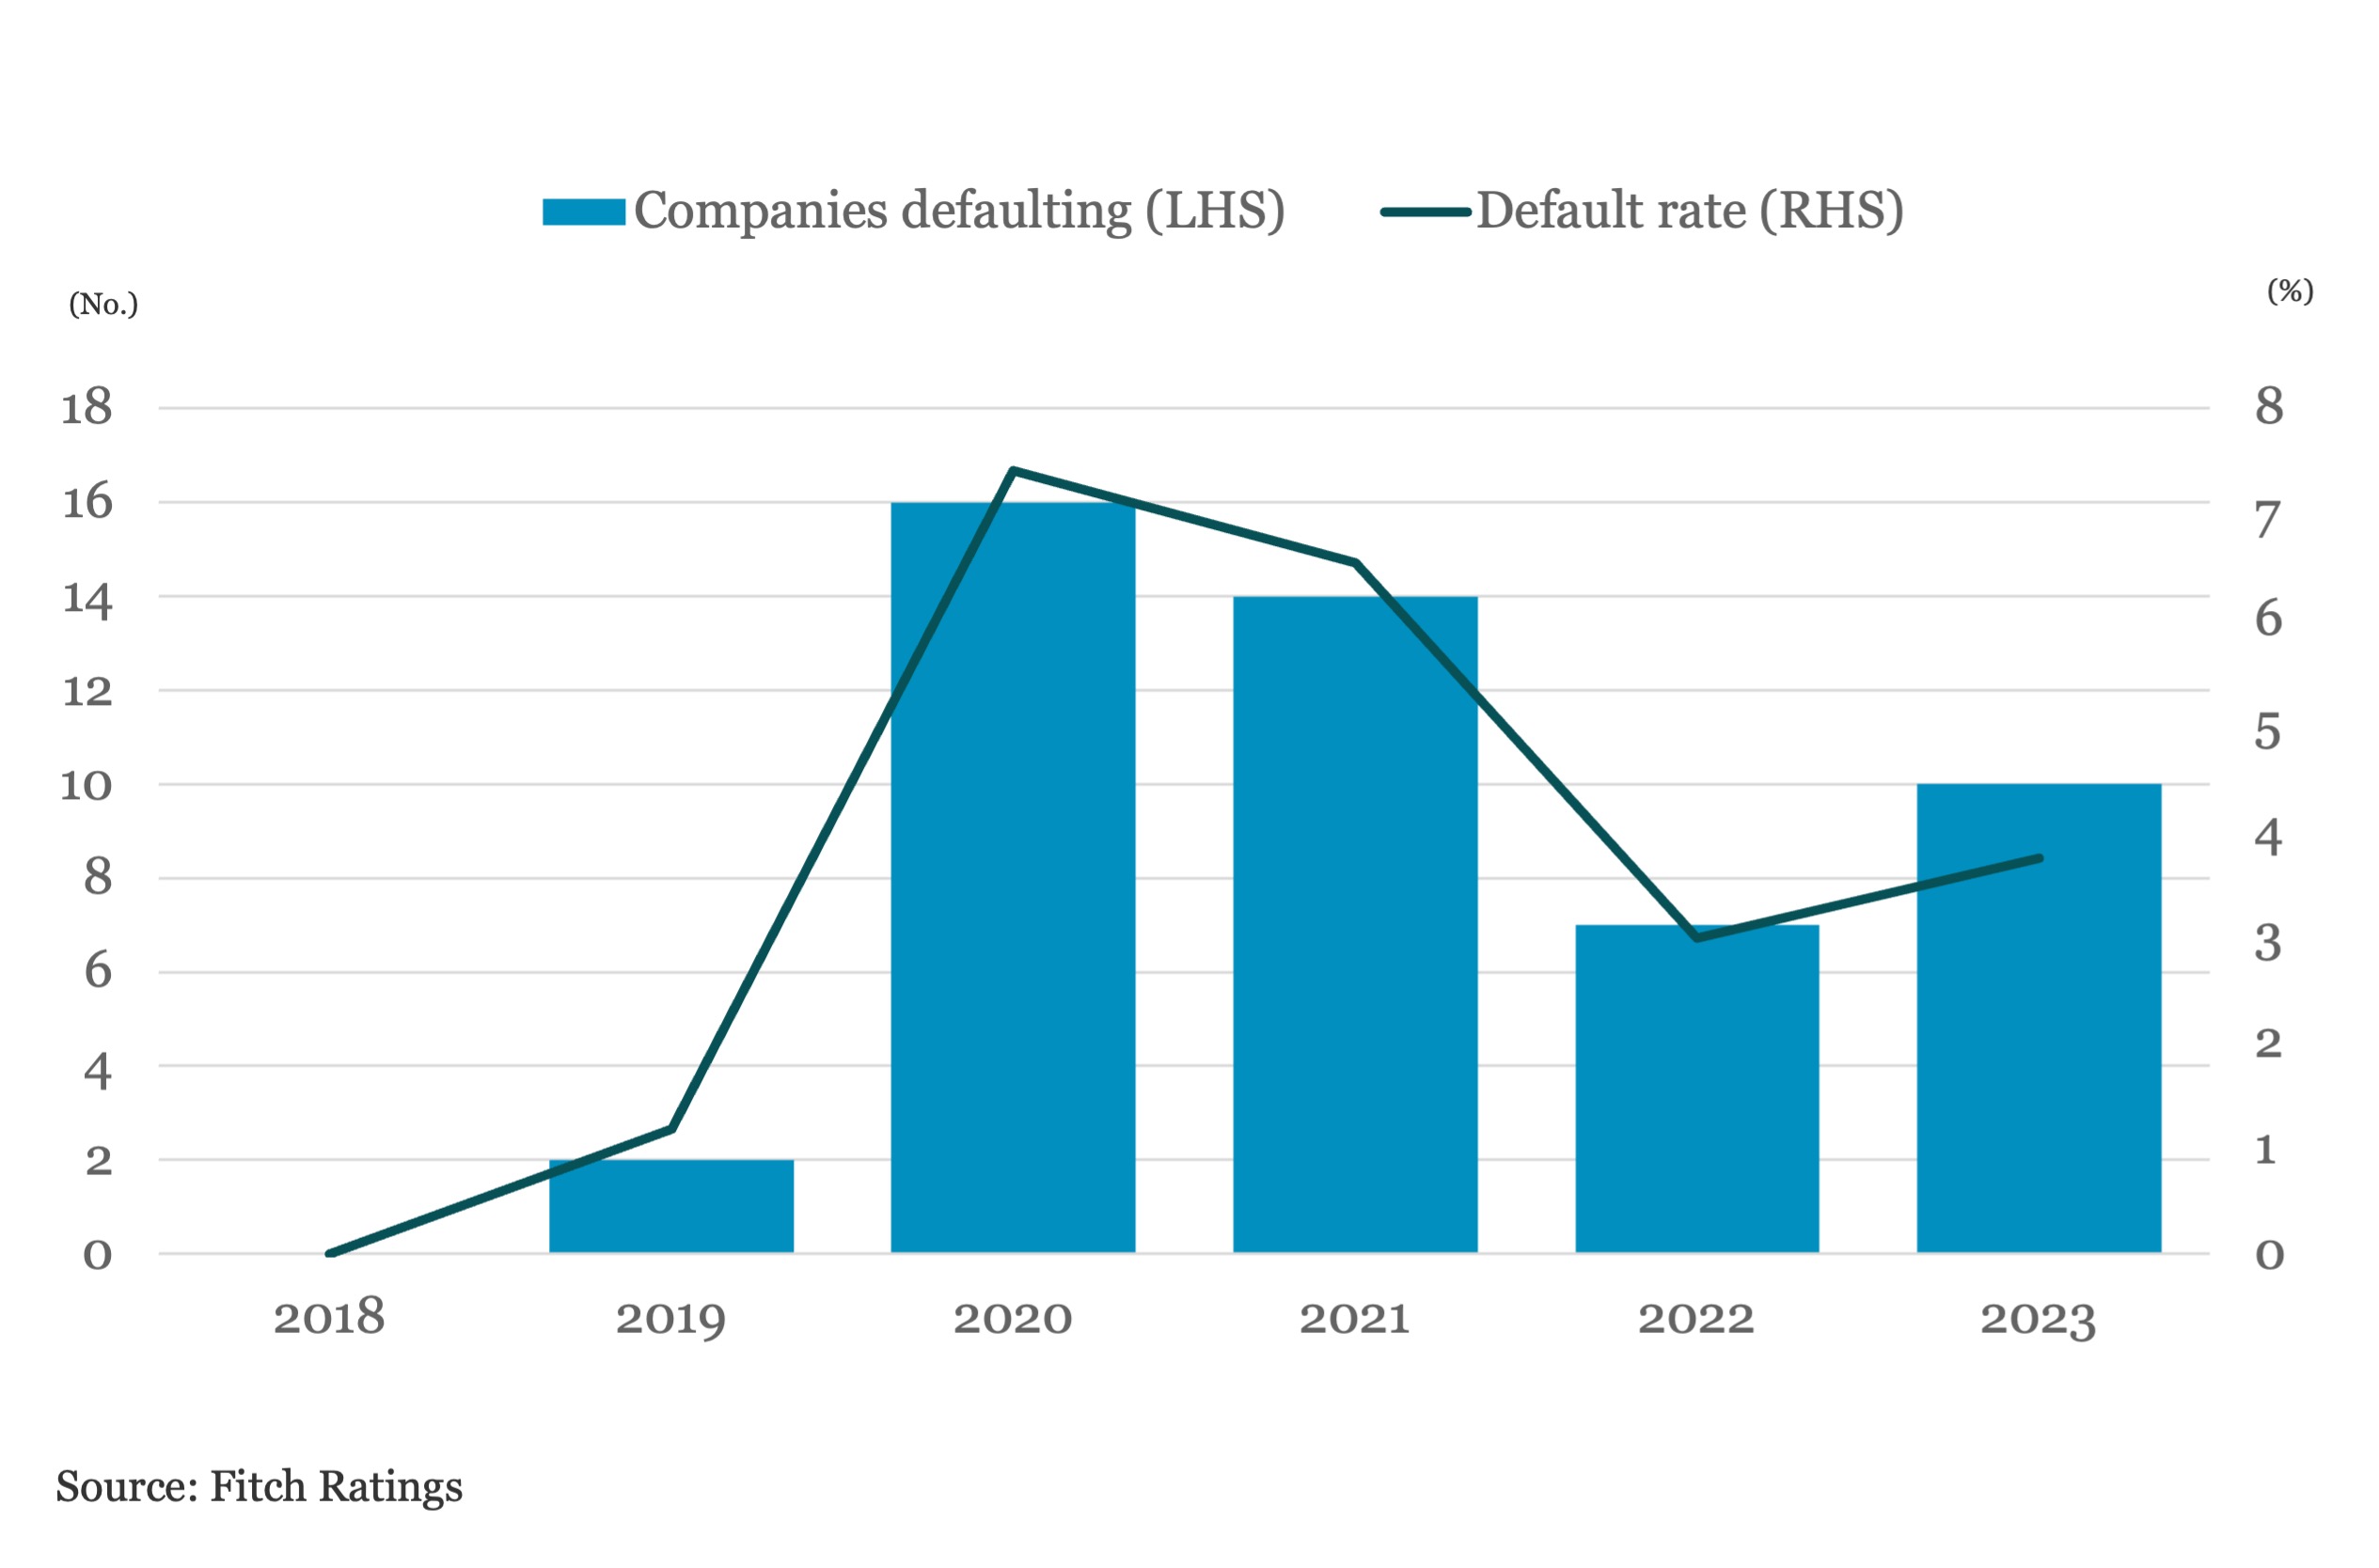
Fitch tracks defaults in our portfolio of about 300 middle market loans that we rate privately for asset managers. The default rate in this portfolio was about 3.7% in 2023, up from under 3% in 2022, also primarily due to rates. While the default rate was higher yoy, it still outperformed the LMM portion of Fitch’s Leverage Loan Universe by nearly 200bp.
Fitch attributes this outperformance to the sponsor-lender partnership that prevails in direct lending, supporting better outcomes than the syndicated market. While Fitch expects a similar rate of defaults in our privately rated portfolio in 2024 as in 2023, the severity of defaults is likely to be greater as sponsors walk away from companies with impaired business models and untenable capital structures.


Latest news
Software, technology and consumer sectors lose deal share in 9M’26
The software and technology sector, the second most active sector in 2025 at 17% of total deal activity, slid to fifth place in the first nine months of 2026.


Leveraged loan investors see gains in November
Following a 0.25% decline in October, the Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned 0.60% this month through…