Download FitchRating’s Report here.
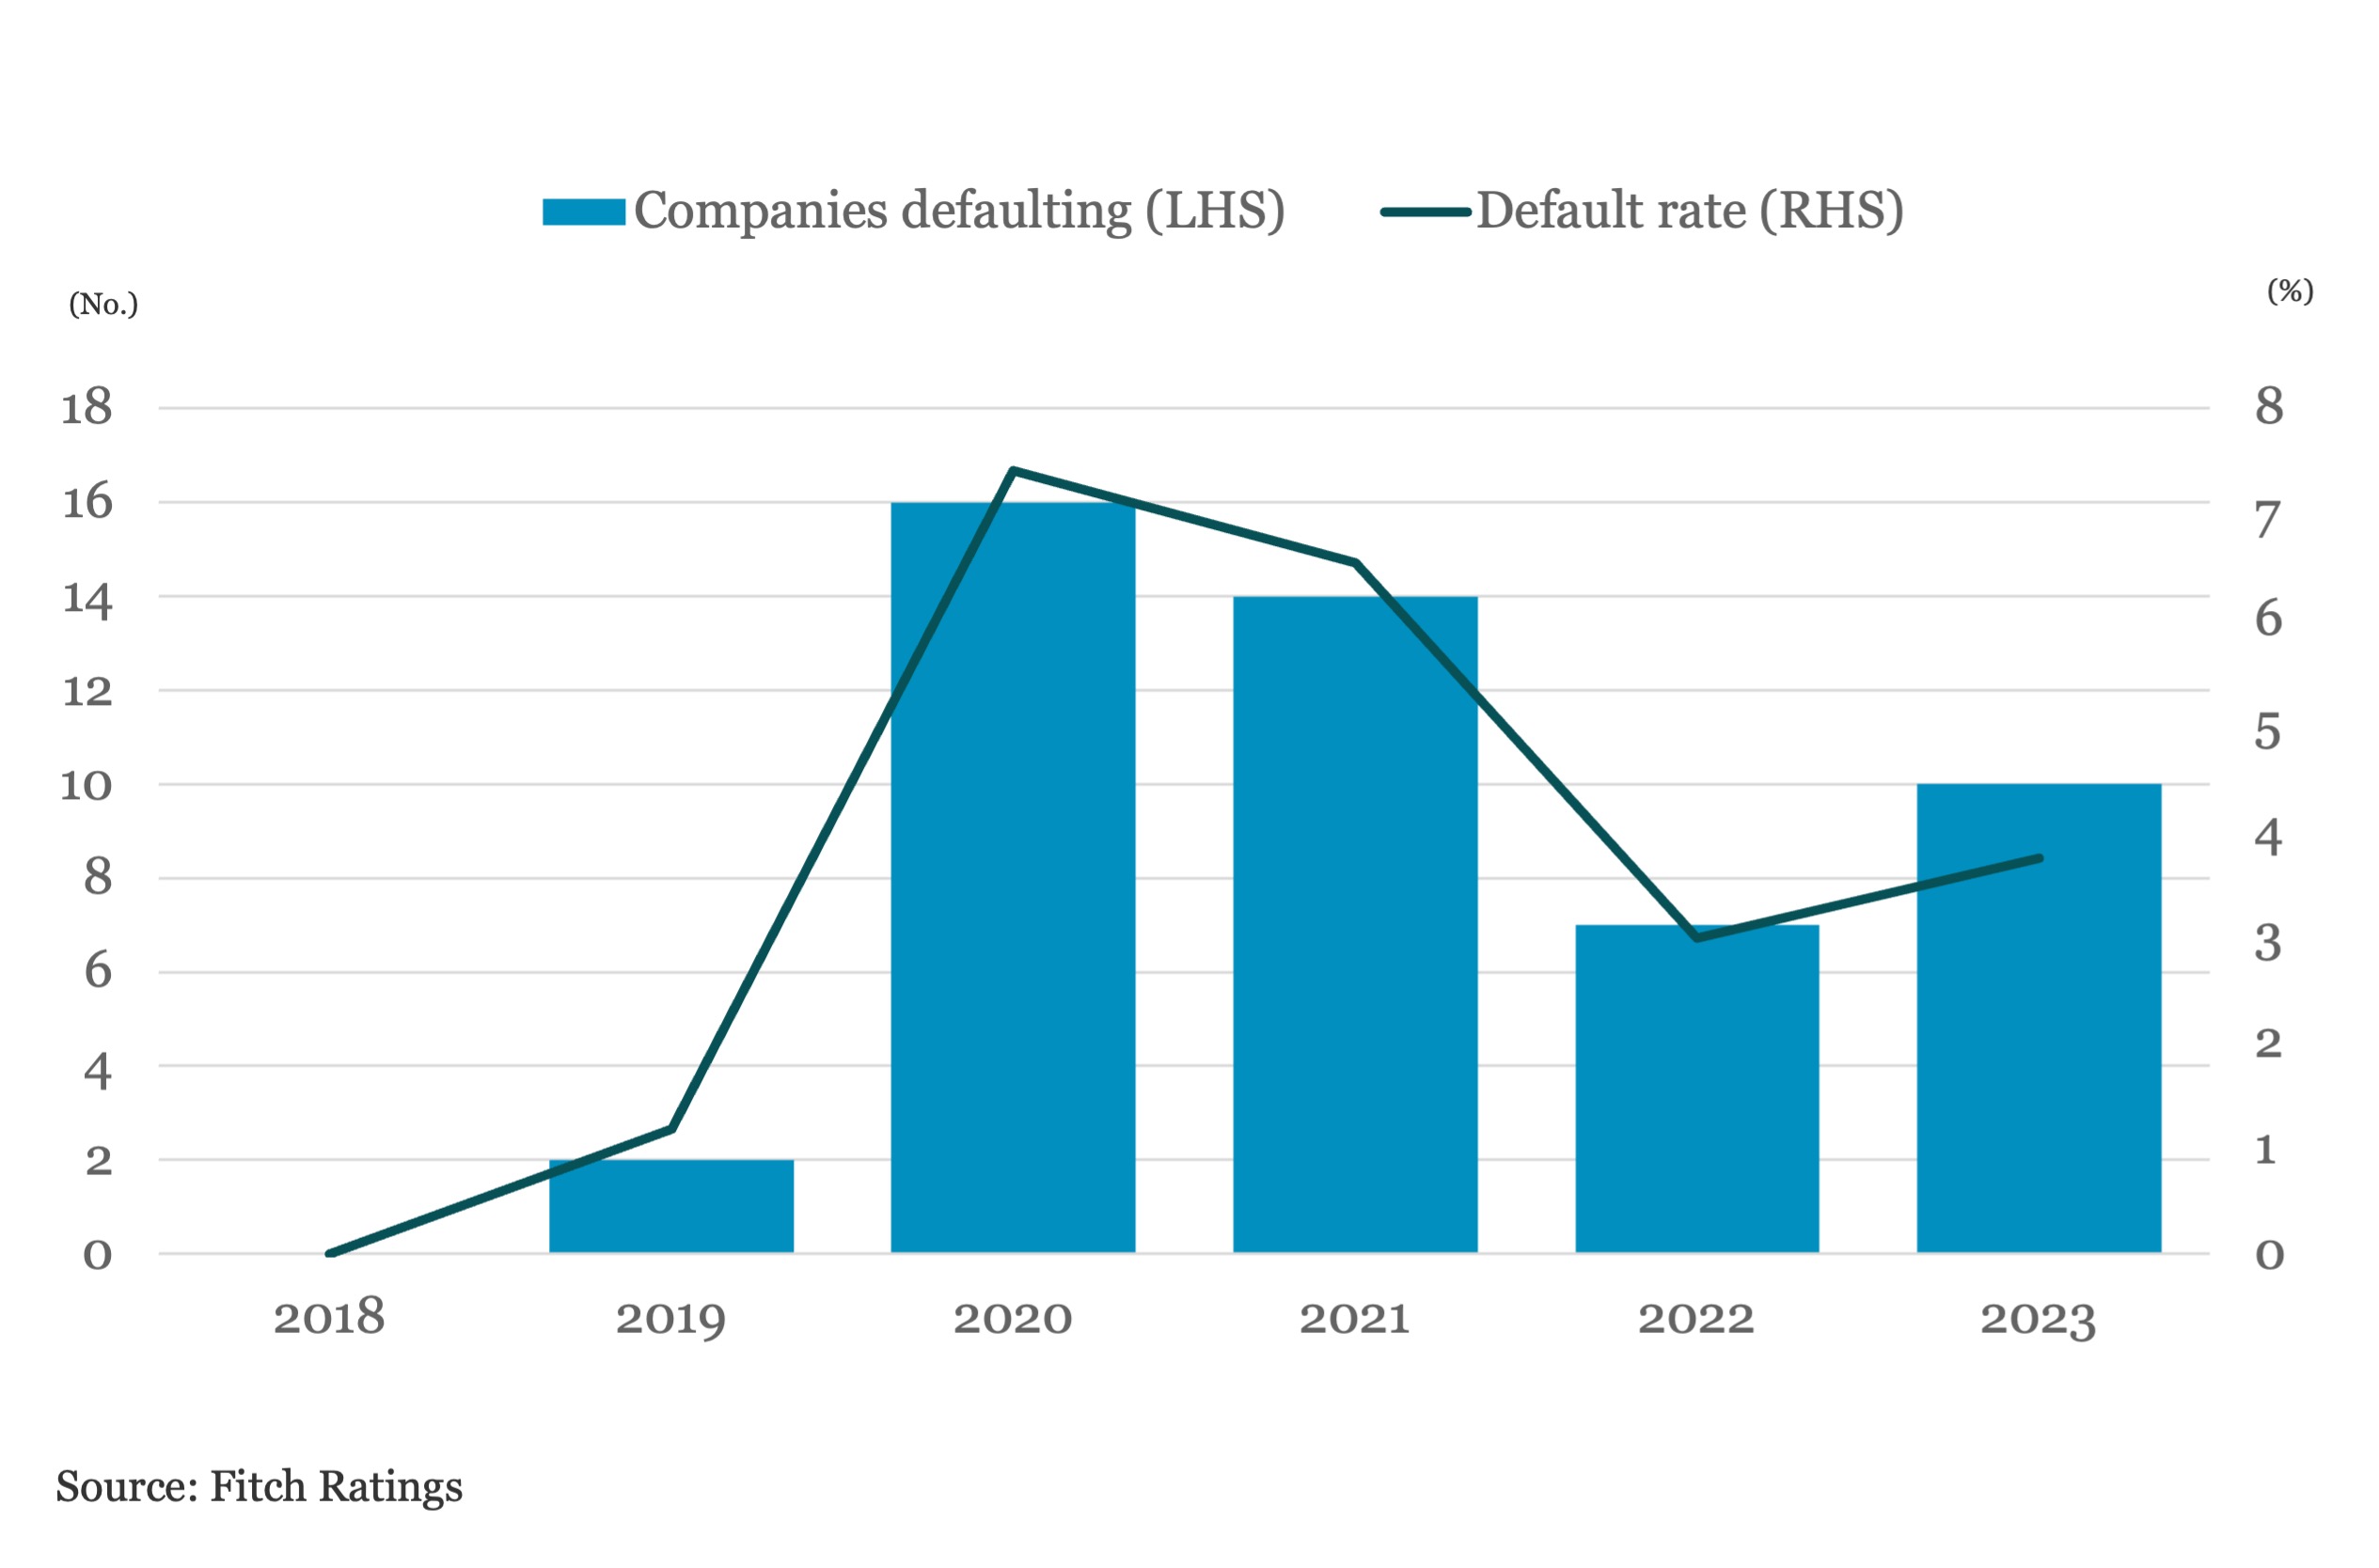
Fitch tracks defaults in our portfolio of about 300 middle market loans that we rate privately for asset managers. The default rate in this portfolio was about 3.7% in 2023, up from under 3% in 2022, also primarily due to rates. While the default rate was higher yoy, it still outperformed the LMM portion of Fitch’s Leverage Loan Universe by nearly 200bp.
Fitch attributes this outperformance to the sponsor-lender partnership that prevails in direct lending, supporting better outcomes than the syndicated market. While Fitch expects a similar rate of defaults in our privately rated portfolio in 2024 as in 2023, the severity of defaults is likely to be greater as sponsors walk away from companies with impaired business models and untenable capital structures.



Latest news
Number of smaller funds dwindles
Analysis of fund-close data found that vehicles valued at under $250m have seen a rapid decline since 2024.While PEI Private…

US Private Credit Transparency Highlights Uneven BDC Performance
Credit performance across business development company (BDC) portfolios remains uneven, although reported losses and non-accruals were broadly stable quarter over quarter, according to Fitch Ratings’ Private Credit Transparency Monitor for 2Q26.