


Fitch-rated U.S. business development companies (BDCs) face persistent headwinds in 2024, with rising paid-in-kind (PIK) income and continued markdowns of investments during 1Q24 signaling additional credit issues and resultant net investment income (NII) pressure. However, increased utilization of supplemental dividend policies will support dividend coverage, with BDCs well positioned for new originations as M&A activity picks up given relatively low leverage and strong funding profiles.
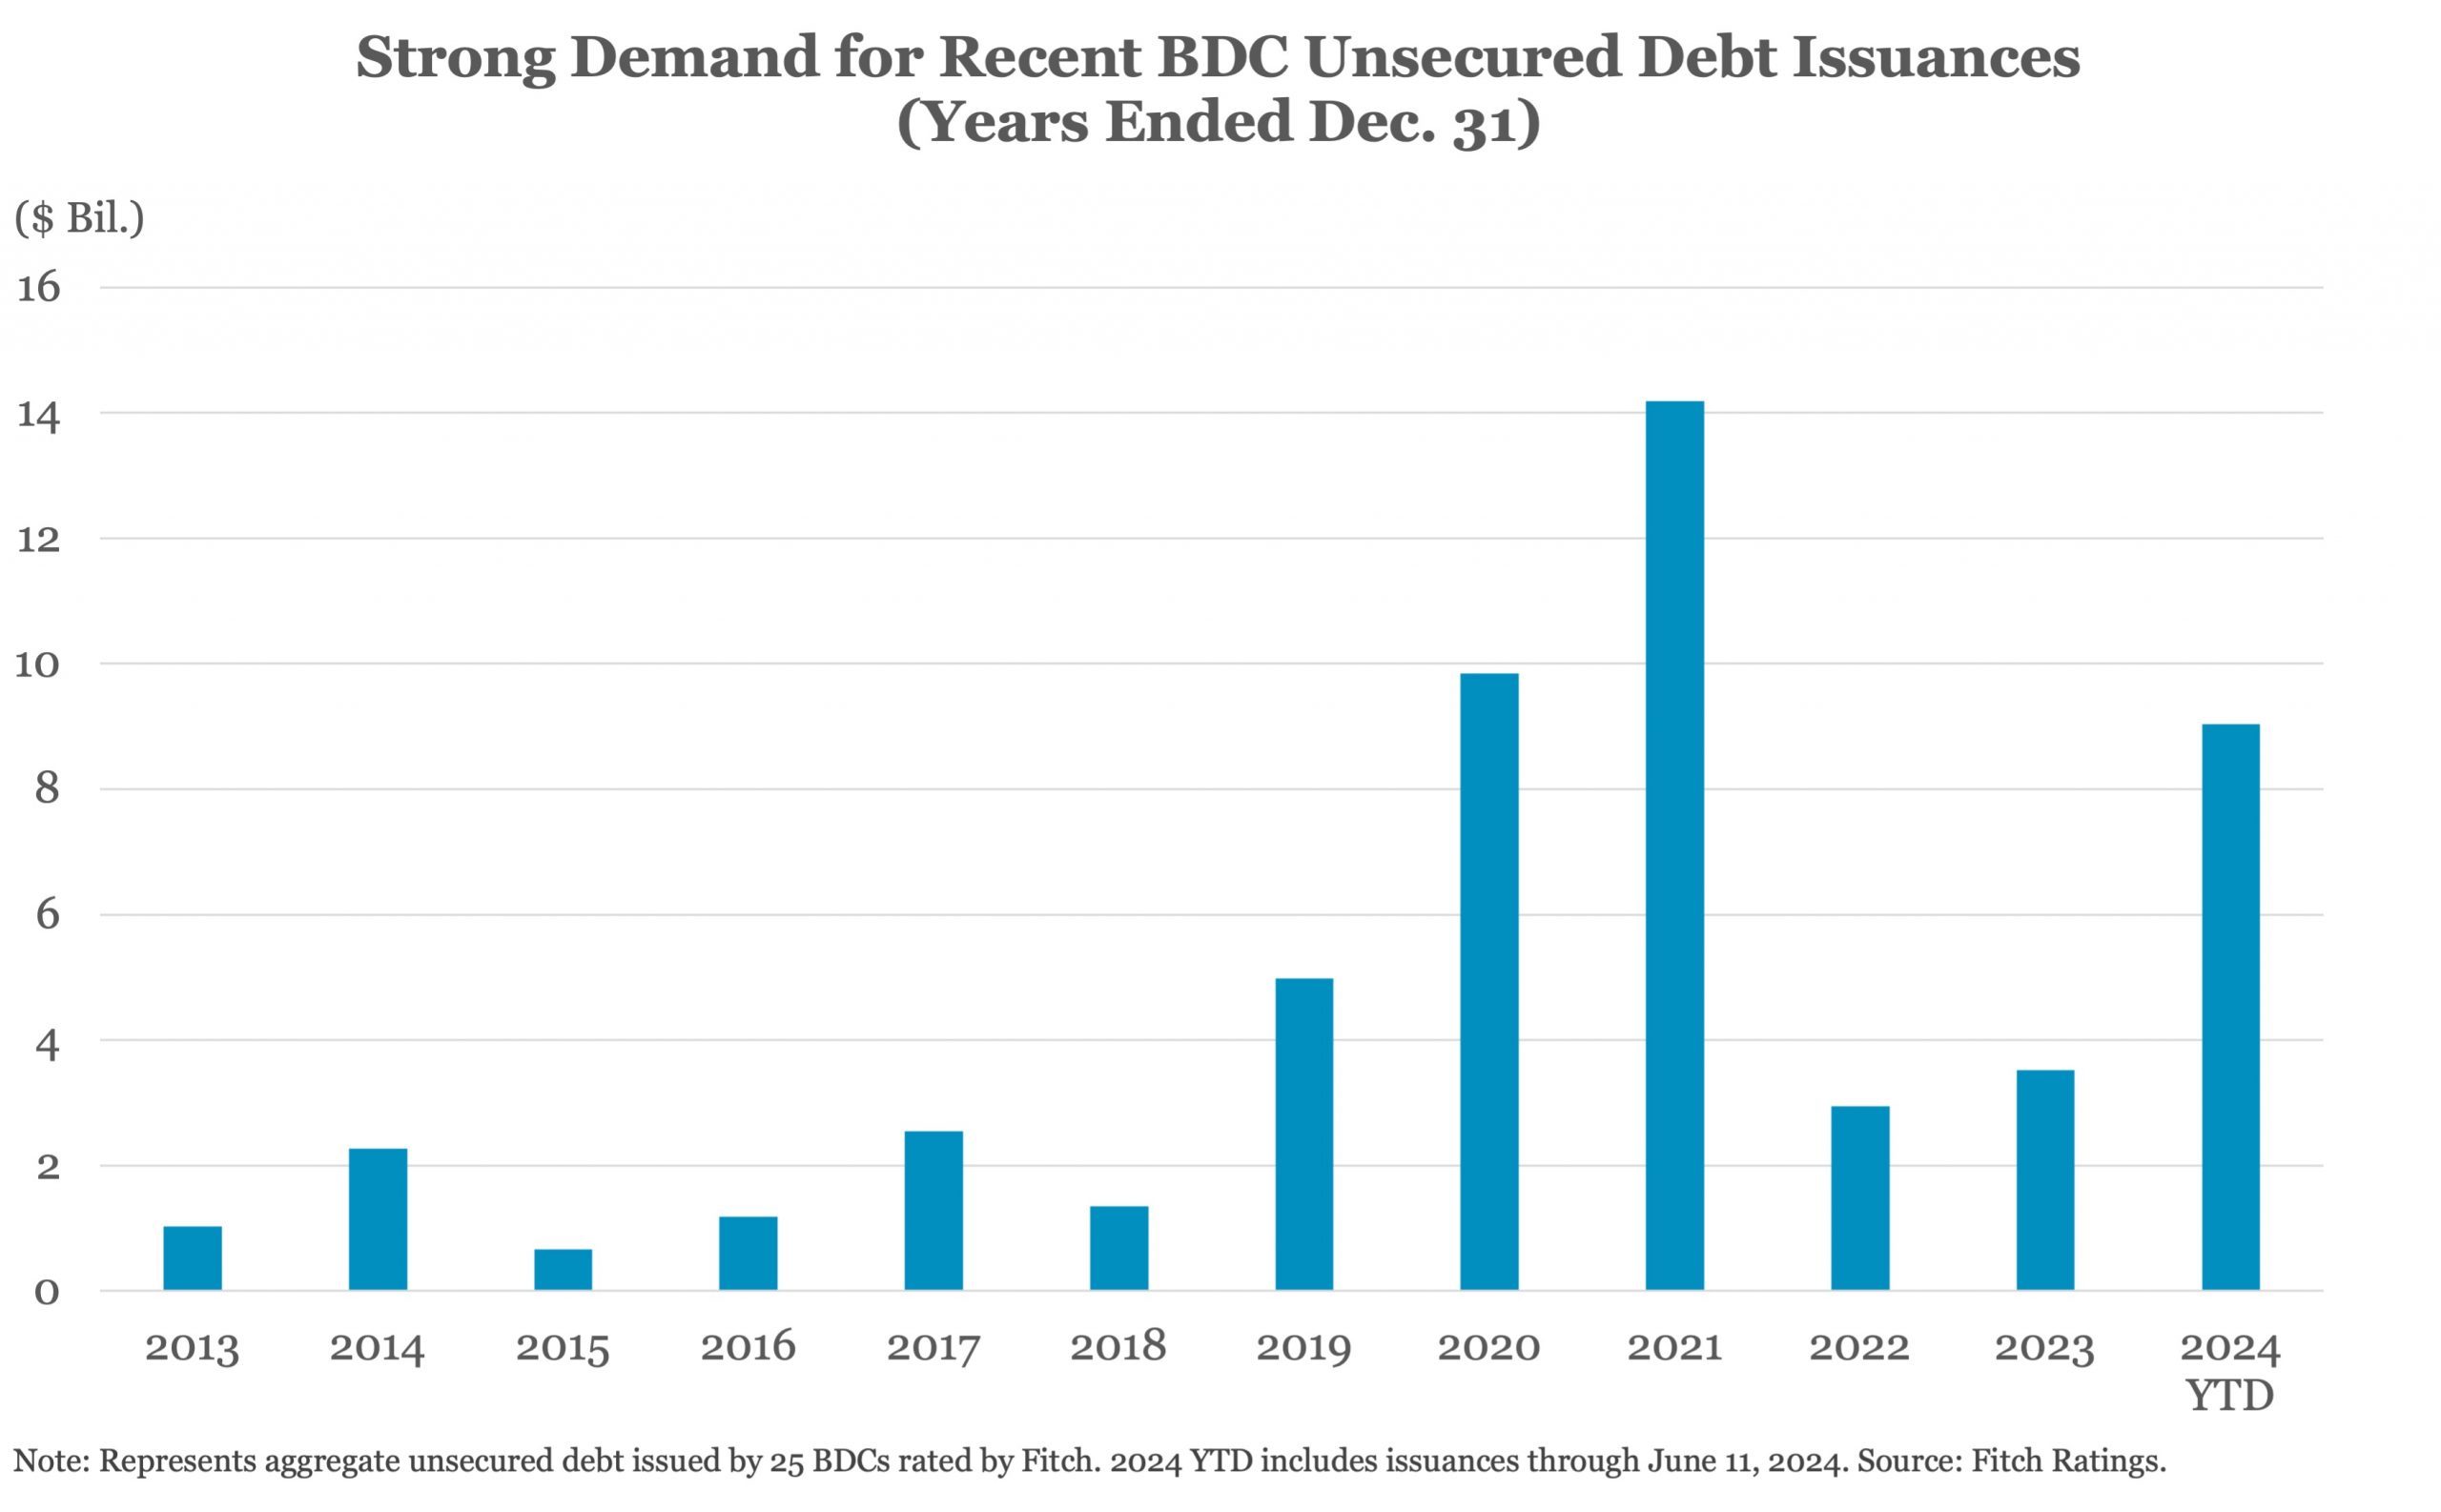
BDCs continue to tap the unsecured debt markets, with four rated BDCs issuing $1.9 billion in May to-date, bringing the year-to-date total to $7.1 billion, more than the $6.5 billion issued in 2022 and 2023 combined. Elevated rates have driven higher coupons on recent issuances compared to upcoming maturities, but BDCs have been increasingly utilizing interest rate swaps to prepare for eventual rate cuts. Unsecured debt averaged 52.0% of total debt at 1Q24 and secured debt averaged 23.1% of assets, providing solid funding flexibility.




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…