


Click here to learn more.
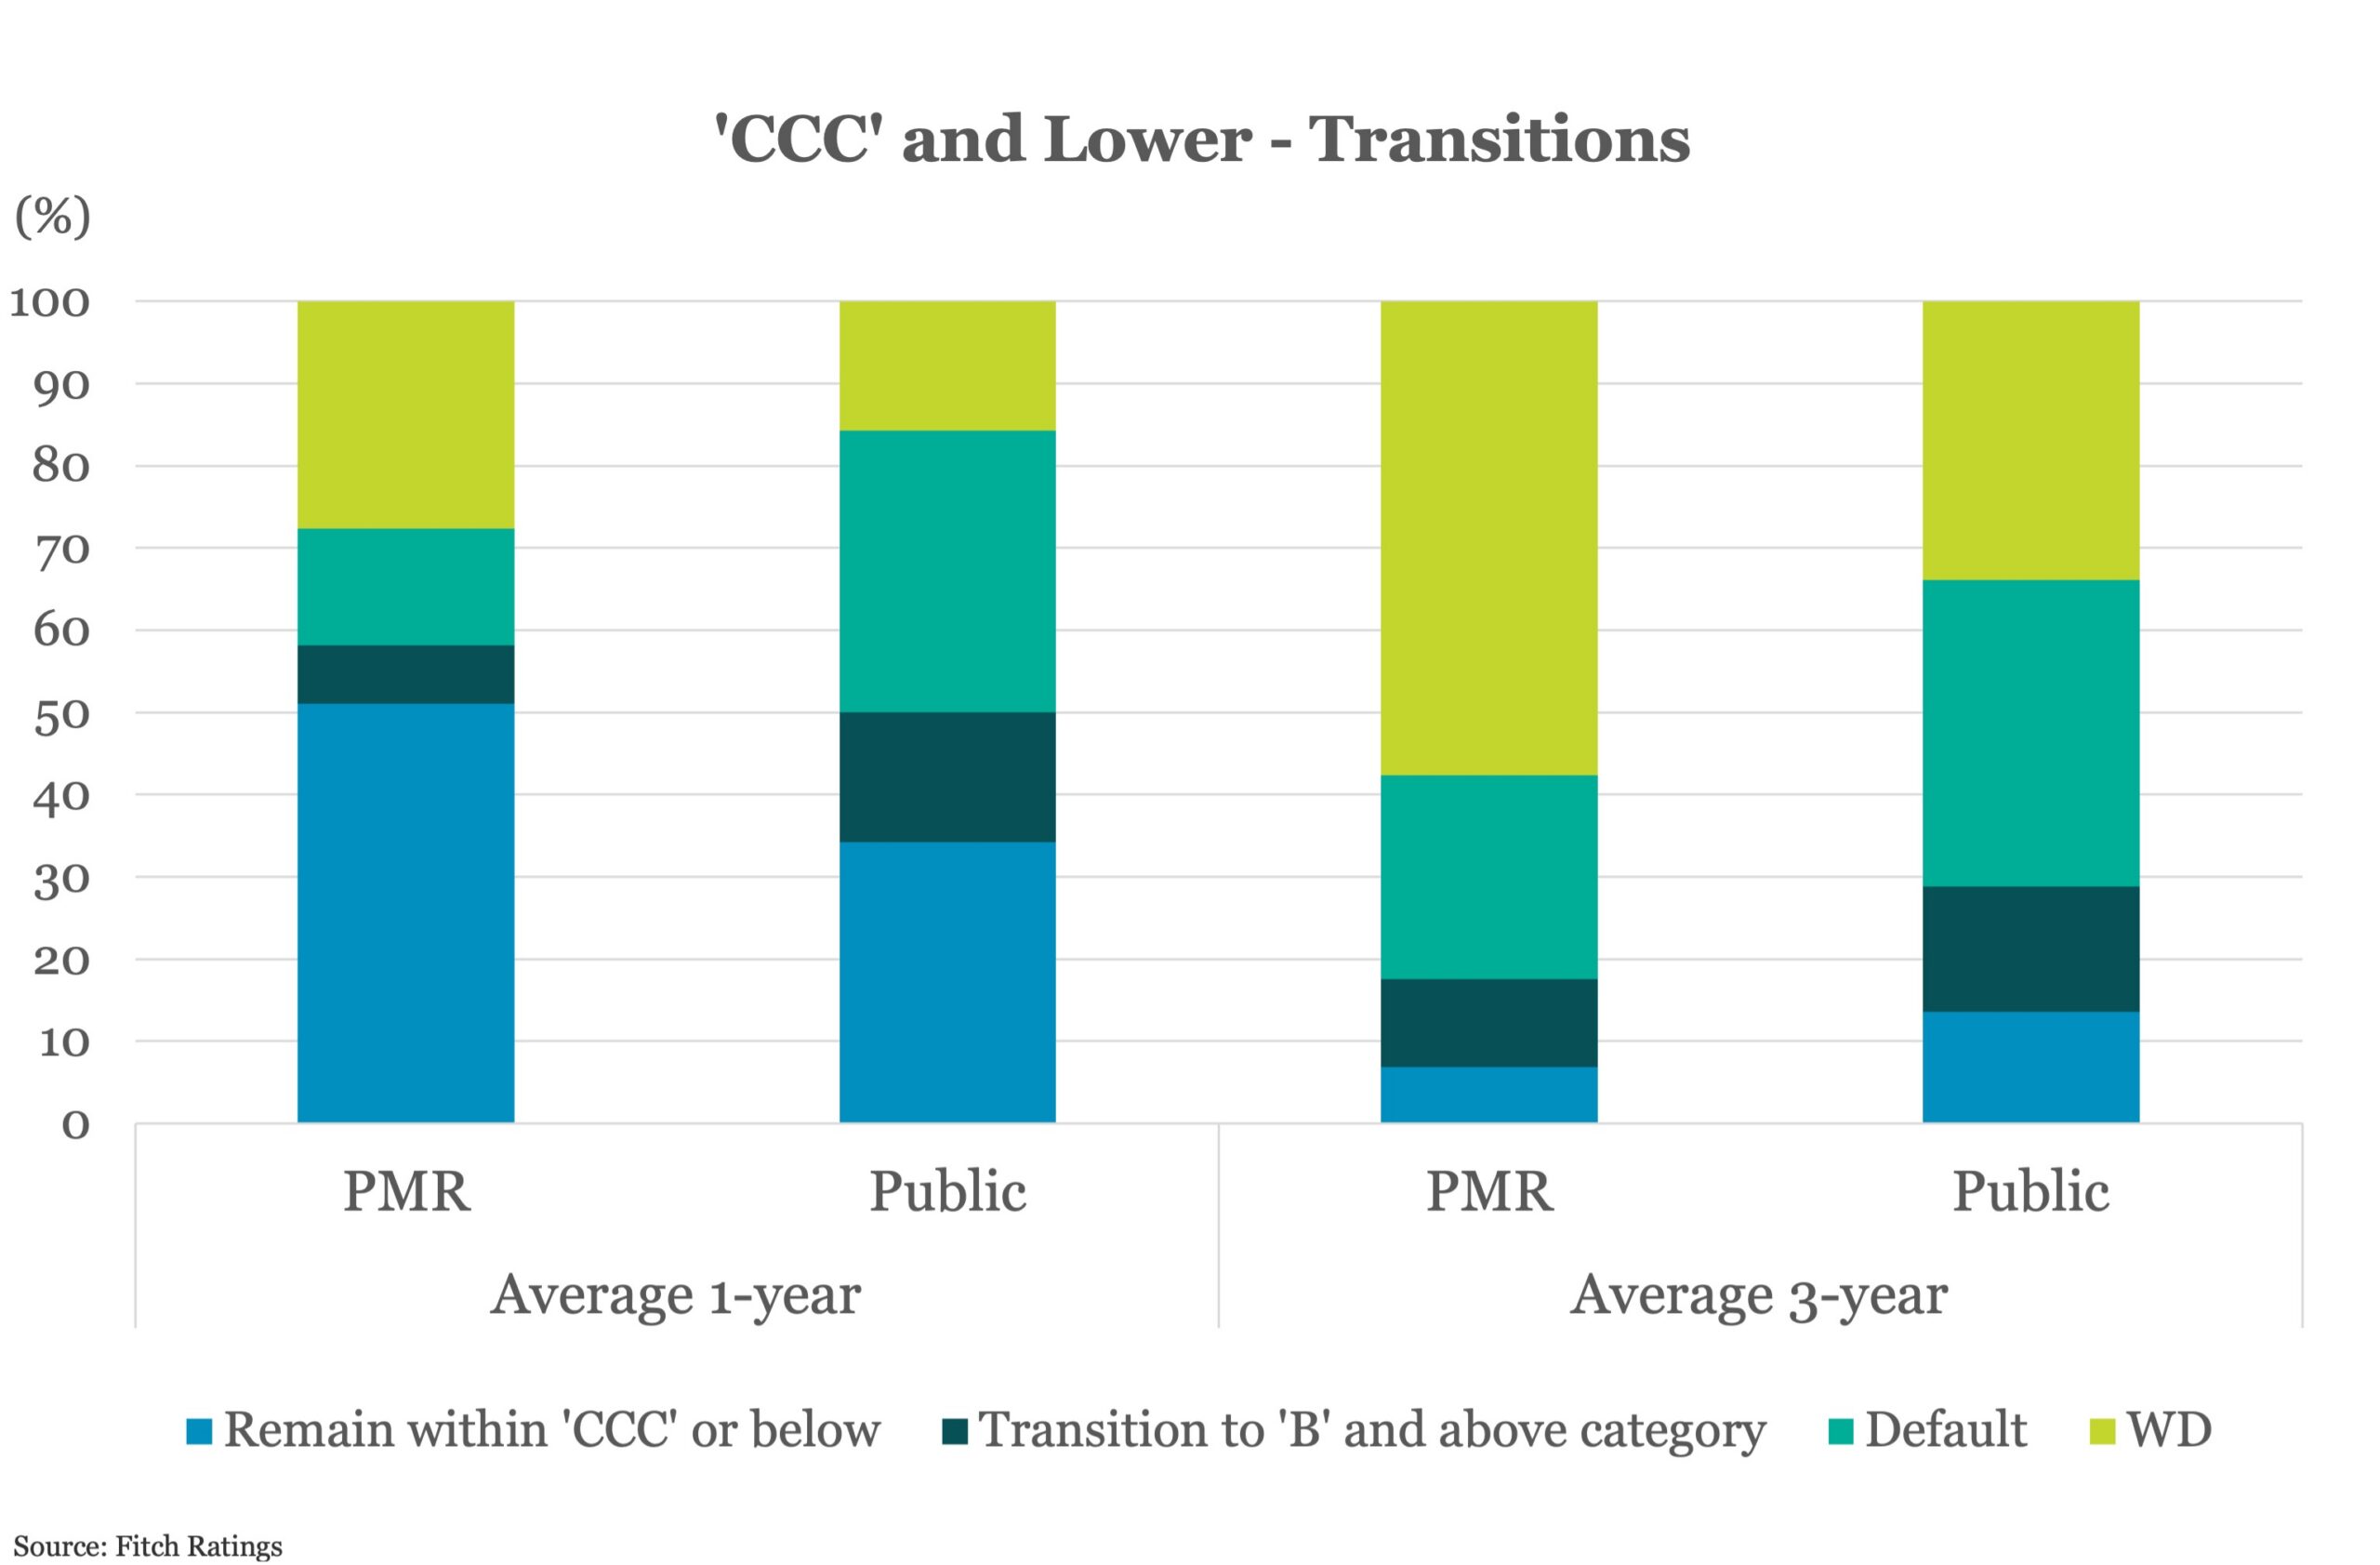
Once in the ‘CCC’ category, fewer issuers in the PMR portfolio ascend to the ‘B’ category than public peers. The AAT% of ‘CCC’ category issuers that reach the ‘B’ category is just 11% in the PMR portfolio compared to 18% for Fitch’s public rating portfolio.
When ratings are public, companies may feel greater urgency to take steps to improve their credit ratings given the stigma and economic drawbacks (lack of CLO eligibility leading to weaker pricing) attached to the CCC rating. Companies with private loans, on the other hand, may feel less urgency, and often may not even be aware of the ratings provided to the lenders or the sensitivities governing upgrades on their loans, so may be less inclined to take specific steps to improve their credit profile for ratings purposes.




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…